
The big discussion: can local first-home buyers in New Zealand still get on the property ladder?
To encourage and support first-home buyers entering the market, the New Zealand Government recently proposed a shared-equity home ownership scheme (click to read). Since then, as major banks have raised fixed mortgage rates, BNZ has also introduced a new debt-to-income (DTI) policy to limit applicants’ borrowing. Experts say lower-income first-home buyers may be the group most affected by tighter lending.
YIJU noticed that data analysis website dotlovesdata.com recently released its latest findings: how long does it take New Zealanders living in different regions to save a deposit for their first home?
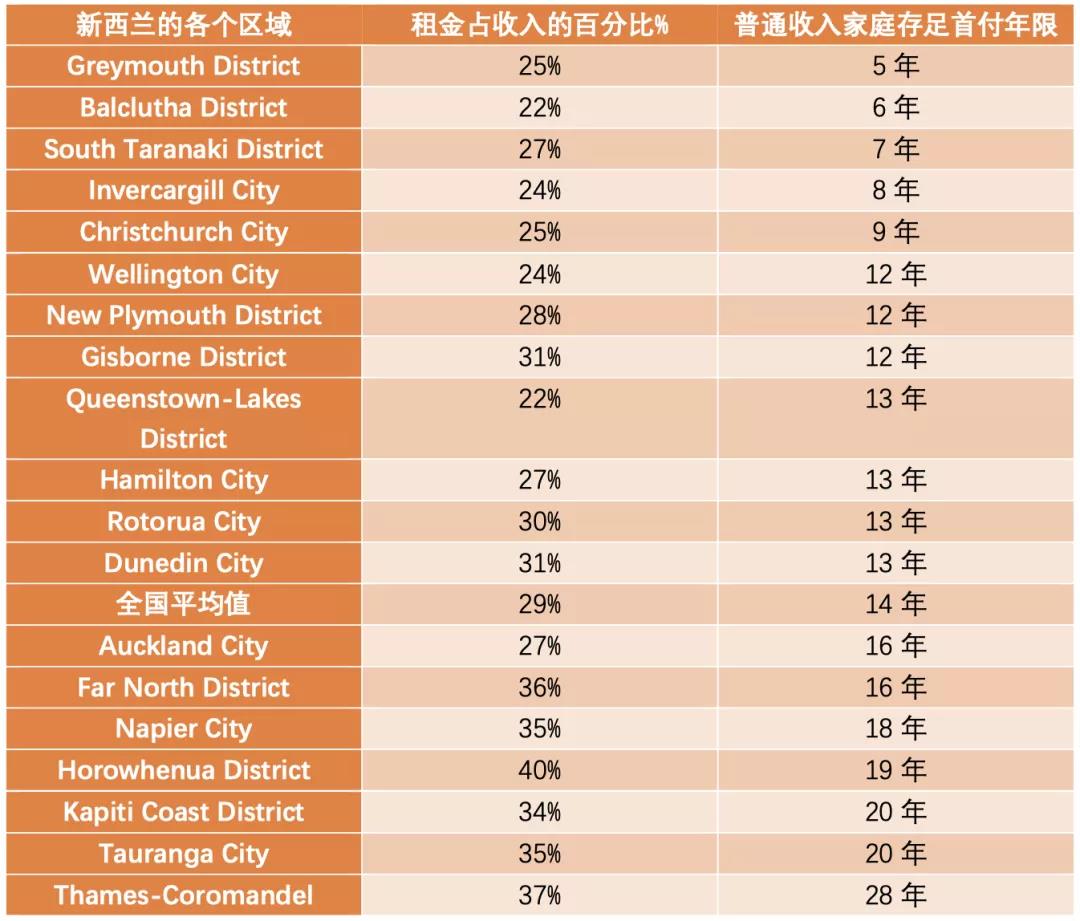
Table: years an ordinary household needs to save a home deposit in different New Zealand regions
(Source: Dotlovesdata on LinkedIn)
The figures above are based on property values and median incomes in October 2021. The deposit-saving calculation uses 20% of household income in each area after deducting average local rental costs. Wellington City residents could save the most towards a deposit each year, at NZ$19,433, while households in Horowhenua District could save the least, at just NZ$6,632. At current house prices, rents and income levels, the average household in Thames-Coromandel would need 27 years to save a deposit. In Tauranga City or Kapiti Coast District, it could take 20 years. Rent takes up more than 35% of income in these areas, while house prices are rising faster than savings. By comparison, the situation is much better in Greymouth, Balclutha, South Taranaki and other provincial towns in New Zealand.
Dotlovesdata’s analysis of rents and house prices suggests New Zealanders’ home ownership dream is rapidly becoming a nightmare for prospective owners. New Zealand’s home ownership rate peaked at 74% in 1991, falling to 64.5% in 2018. YIJU believes one possible reason is that, during a sustained cycle of rising house prices, many people sold their homes but could not buy another for the same price.
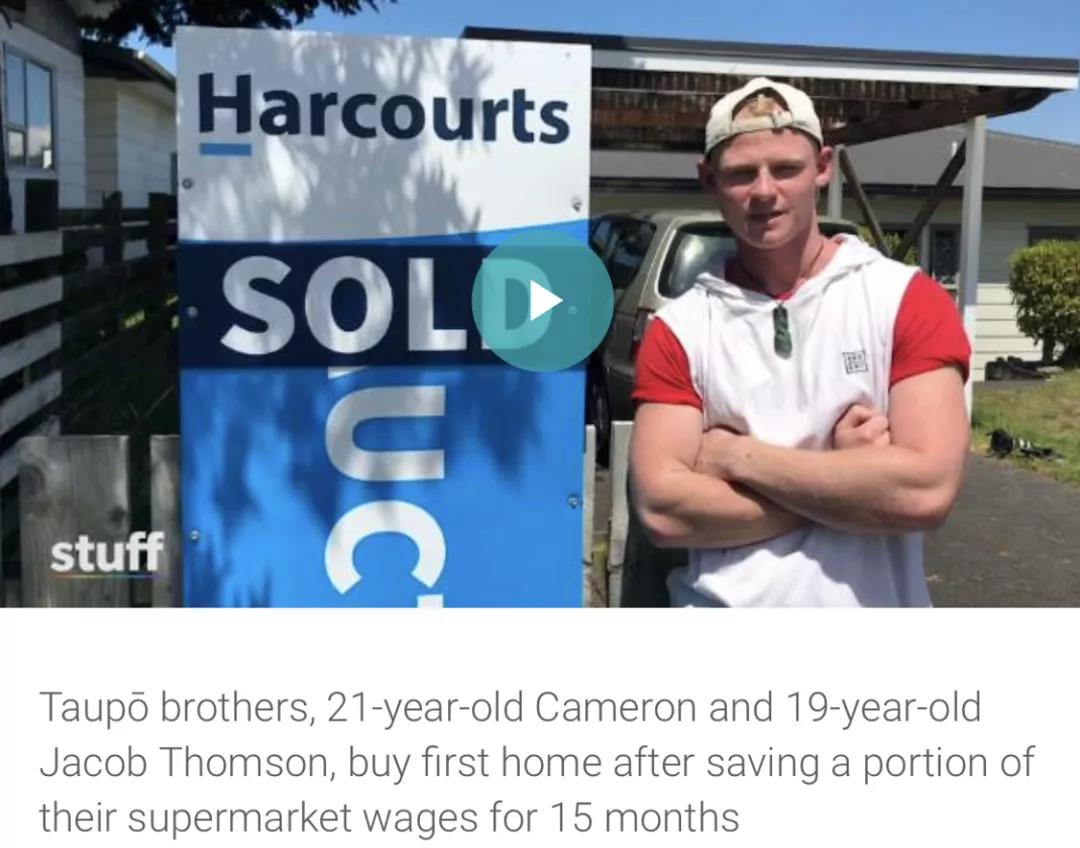
Image source: Stuff
But is the reality really as difficult as the data suggests? Stuff recently reported on how two young brothers in Taupō bought their first property without any financial help from their parents, covering their living costs and saving for a home on wages from working at a local supermarket.
The brothers saved a deposit over 15 months on wages of NZ$21 an hour, buying a three-bedroom home at a recent auction for just over NZ$600,000.
They are not alone. Readers Kevin Zhang and Amy Deng, a young Chinese couple, recently told YIJU New Zealand how they successfully bought their first Auckland home three years after starting work, without turning to the “bank of Mum and Dad”.
Focus on the ultimate goal
When the couple, both under thirty, decided three years ago to buy their own home, they realised they would have to make compromises to achieve their dream. Over the following years, they saved the deposit they needed, then actively searched for a home they liked within their price range.
Starting from scratch and with no plans to seek help from parents or other family members, they needed to restrain spending across all areas of life to increase their savings. As Kevin is self-employed, his variable income made it essential to plan and stick to a monthly budget. The couple planned their grocery shopping each week, buying only what they needed and avoiding impulse purchases.
At the end of each financial year, they also reviewed fixed annual expenses such as insurance to ensure costs stayed within a range they could afford.
Actively explore KiwiSaver and other
first-home assistance schemes
They had always intended to stay within Auckland’s price caps for government first-home assistance: NZ$600,000 for an existing home and NZ$650,000 for a new home. Their initial deposit target was NZ$50,000, including their available KiwiSaver withdrawals and other first-home assistance. A year and a half later, however, they had to raise their target to NZ$100,000.
Find a home you are happy with
Finding a home they liked within Auckland’s price cap was no easy task. They had to limit their search to parts of South and West Auckland. South Auckland was initially their preference, as similarly priced properties could offer more land. But one condition of their government assistance was that they could not buy at auction, so they narrowed their search to West Auckland. Finally, late last year, they found a 2.5-bedroom townhouse they liked near Westgate and recently completed settlement. Its price was also just within the limit for their grant.
Find the right mortgage
Kevin says the mortgage application was far from straightforward. Their relatively small deposit and the effects of the pandemic left him uncertain about securing a loan. After comparing fixed mortgage rates at major banks, he eventually chose a bank they were happy with.
YIJU has collected the latest mortgage rates from different banks for your reference:
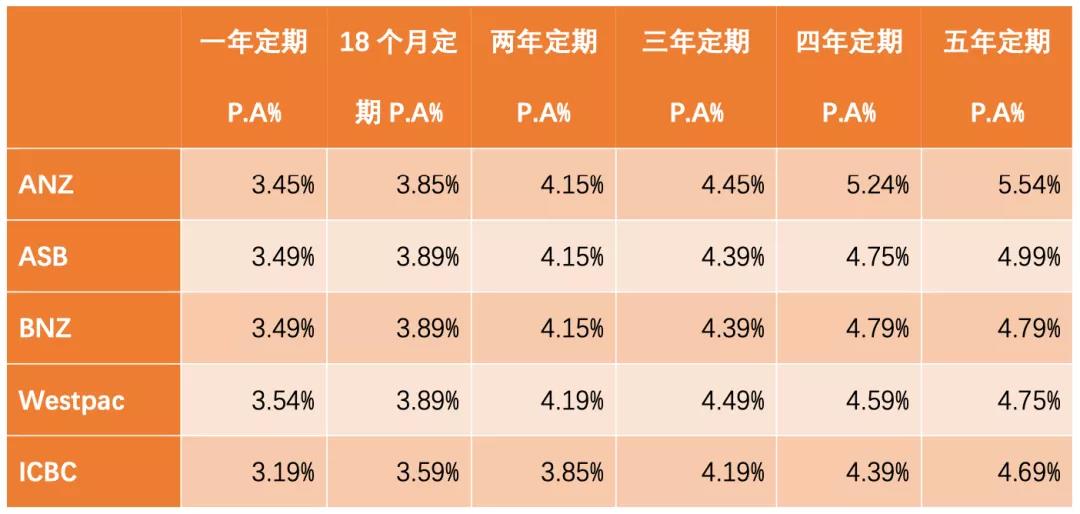
Latest annual fixed mortgage rates at major New Zealand banks as at 15/11/2021
Disclaimer: the views above are for reference only. YIJU and the interviewees accept no related liability.