
Mortgage holders, take note! These tips will keep your finances on track throughout the year
How can you get through the toughest period before interest rates fall, while improving your finances in the new year as much as possible and preparing for future investments? In this article, we round up some suggestions that we hope will help homeowners facing difficulties.
Total Wealth financial adviser Katrina Studholme said homeowners struggling with rising mortgage repayments should review their finances promptly. This helps ensure borrowers can cover rising living costs in an environment of high inflation. The review should cover current personal income, debt levels, budgeted spending, risk management, insurance, retirement savings and estate planning.
She said that, viewed another way, a financial health check tests a person's financial resilience to unexpected events. Developing and reviewing a long-term financial plan is very worthwhile for homeowners. As well as consulting a professional adviser for a financial health check and tailored plan, people can use the tools on sorted.org.nz to assess their own position.
EasyStreet mortgage adviser Gareth Veale said it is important to speak with a mortgage adviser or bank early. As mortgage interest rates continue to rise, homeowners can prepare to refinance. He said a borrower with a NZ$500,000 mortgage who secured a new loan from another bank at a lower interest rate through refinancing could easily be NZ$5000 better off after a year.
Veale also advised mortgage holders to get their everyday spending in order. Banks generally want to see prospective customers spending sensibly, without deliberately overdrawing their accounts or falling behind on utility bills. People can obtain copies of their credit reports from credit reporting agencies such as Experian and Centrix to check for defaults that need resolving. He suggested borrowers start applying to refinance around 80 days after their loan matures, allowing them to lock in a lower rate once approved.
National Capital director Clive Fernandes said the hardest part of buying a first home in New Zealand was putting together a sufficient deposit. Being able to use KiwiSaver towards a first-home purchase was a valuable opportunity. He believes it is never too late to actively manage your KiwiSaver account. He advised first-home buyers to understand KiwiSaver's basic rules and the eligibility criteria for first-home withdrawals. Those who can afford it should increase their KiwiSaver contributions and keep an eye on their spending habits. They could also ask their employer to increase its contribution rate, or negotiate a higher rate in their next job.
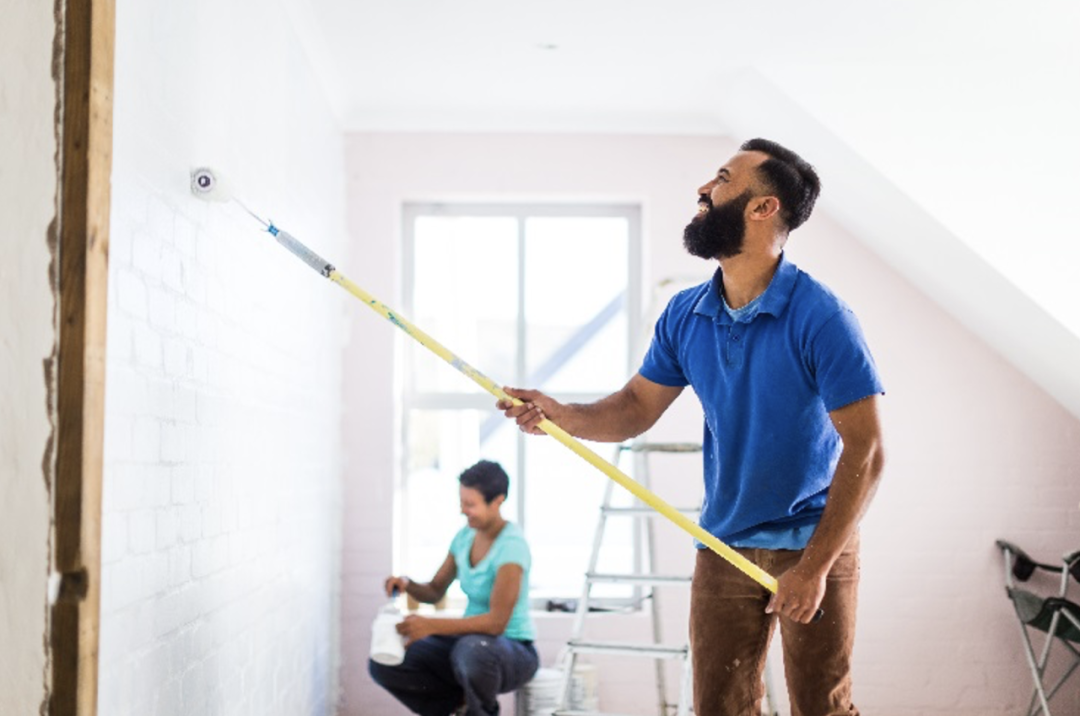 Homes that do not need major upgrades or repairs are easier to sell
Bayleys real estate agent Linda Simmons said well-maintained homes were easier to sell and could achieve better prices. If a more appealing home came onto the market or a homeowner's financial circumstances changed and they needed to sell, keeping up with maintenance would help them sell quickly. Simmons said these urgent sales were not uncommon. If a home was not ready for sale and repairs had been deferred, its owners might miss out on the best price the market could offer.
Simmons stressed that maintenance did not mean homeowners needed to undertake a complete renovation or install a new kitchen. It was more about addressing problems buyers would immediately notice, through relatively simple jobs such as repainting the roof or windows. Gardens deserved the same attention; she likened good garden maintenance to having a regular haircut.
New Zealanders who lived through 2023 will appreciate the importance of preparing for the unexpected: homes can flood, while interest rates and living costs can soar to unimaginable levels. Rival Wealth financial adviser Tim Fairbrother offered this advice: diversifying investments can reduce investment risk and keep a portfolio flexible,which is the familiar principle of never putting all your eggs in one basket. He said that, for homeowners, this could mean setting aside some money in an emergency fund, maintaining minimum KiwiSaver contributions and making mortgage repayments, while directing spare money that might otherwise go towards repayments into other investments, such as diversified funds or other properties.
Property investment may not suit everyone, but it can be a good way to build capital. Its biggest advantage is leverage. Opes managing partner Andrew Nicol explained that property investors were effectively investing with the bank's money. For example, if you put in NZ$1, the bank might lend you another NZ$4. Nicol added that he recommended investing in property in 2024 because the market had fallen substantially from earlier levels. High interest rates meant fewer investors were active in the market, potentially allowing buyers to secure better deals than before. Although investing in property was currently difficult for most people, that did not prevent them from preparing for future financial success.