
Breaking: major CCCFA lending reforms on the way as FMA takes over oversight and personal liability is removed
Major changes are coming to the lending market as the Government gradually scales back consumer protections criticised for making borrowing more difficult. Cabinet has recently agreed to further amendments to the Credit Contracts and Consumer Finance Act (CCCFA) to prevent lenders from getting into difficulty over mistakes.
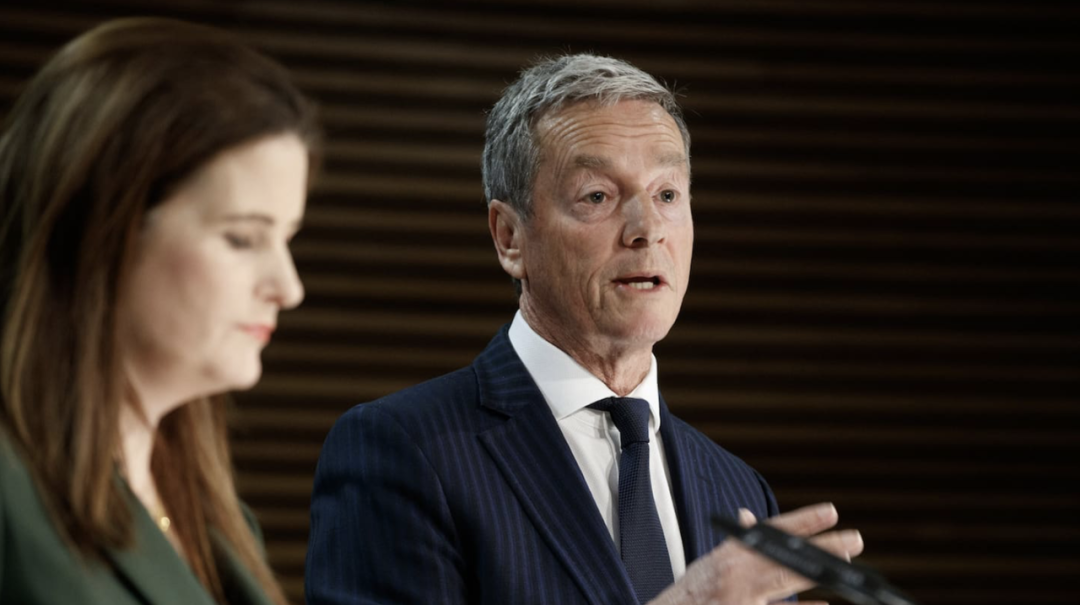
Finance Minister Nicola Willis and Commerce and Consumer Affairs Minister Andrew Bayly say changes to the CCCFA rules will make borrowing easier.
Personal liability to be removed
Once the legislation changes, directors and senior managers of entities lending to consumers, rather than businesses, will no longer be personally liable for CCCFA breaches. This means that if a bank or finance company fails to ensure its lending is reasonable, its chair will no longer risk a fine of up to NZ$200,000. The amendment aims to reduce risks for lenders. Commerce and Consumer Affairs Minister Andrew Bayly explained: “While it is entirely appropriate to hold lenders accountable for poor lending practices, extending these requirements to individuals is overly harsh.”
Lenders with inadequate disclosures
to receive more lenient treatment
The second CCCFA change agreed by Cabinet will prevent lenders from being penalised for inadequate or inaccurate product disclosures, provided these cause no harm to borrowers. Lenders will also no longer have to prove their mistakes caused no harm. Instead, the burden will shift to consumers to prove they suffered harm. Bayly said the move aims to ensure penalties are proportionate to breaches. “This will reduce lenders’ administrative burden, lead to more common-sense decisions and reduce instances where lenders are penalised despite no harm having been caused.”
So far, a small number of banks have had to compensate customers for inaccurate disclosures. For example, in 2020, ANZ paid customers NZ$29,000,000 in compensation after admitting that coding errors in its loan calculators had resulted in incorrect interest payment calculations.
A new licence will be created
While these changes will scale back consumer protections, Cabinet has also agreed to require consumer credit lenders to obtain a licence from the Financial Markets Authority (FMA). As previously signalled, the FMA will take responsibility for overseeing the CCCFA. Permanent staff currently working at the Commerce Commission will be offered opportunities to work at the FMA.
Dispute resolution schemes
Bayly has also turned his attention to the industry dispute resolution schemes consumers can approach when disputes arise with financial service providers, including the Banking Ombudsman and the Insurance and Financial Services Ombudsman. He wants to set targets to better measure these schemes’ performance. At an industry event hosted by the Financial Services Council on Wednesday evening, he announced plans to work with the industry to create a single entry point where consumers can seek help if they do not know which dispute resolution scheme their provider belongs to.
Conduct licensing process to be simplified
Bayly confirmed that Cabinet had agreed to other previously signalled reforms to simplify conduct regulation for financial service providers: banks, insurers and non-bank deposit takers. These adjustments will accompany the introduction in March of a new regime arising from the high-profile 2017–19 Australian Royal Commission inquiry into financial services. The Conduct of Financial Institutions regime has been years in the making and aims to ensure financial service providers treat customers fairly. Following complaints from some institutions that the rules are too cumbersome, Bayly has promised to remove some of the more prescriptive requirements. He also confirmed that once the regime takes effect, conduct licences held by existing financial service providers will automatically transition to a new single conduct licence issued by the FMA.
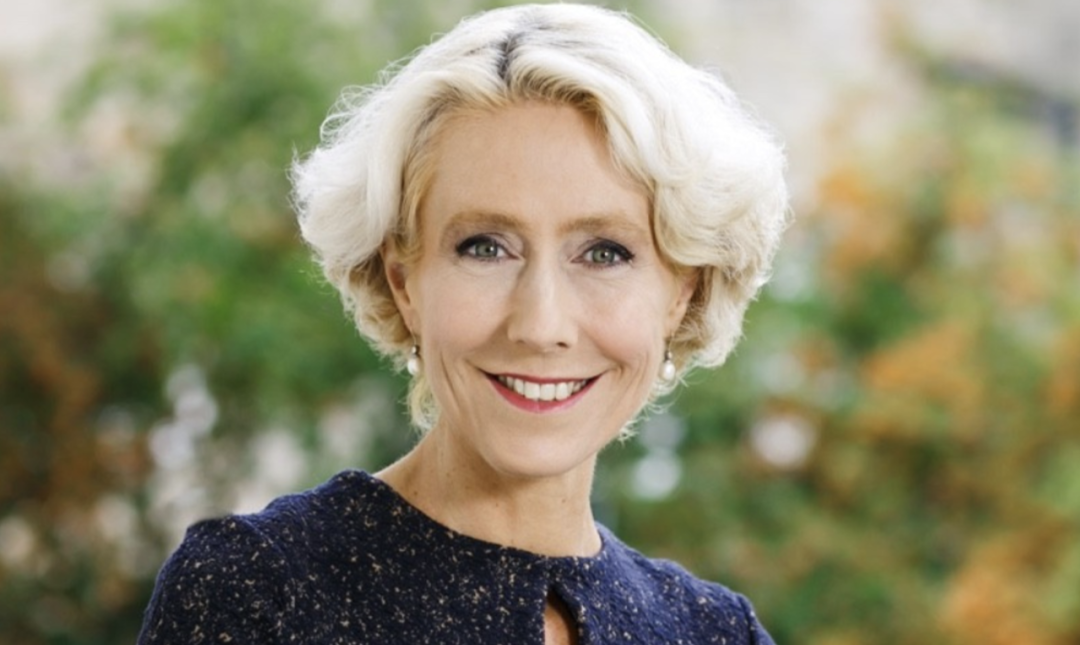
Financial Markets Authority (FMA) chief executive Samantha Barrass
The FMA’s regulatory philosophy
The FMA will receive greater powers, including the ability to conduct unannounced on-site inspections when necessary and review businesses before a change of control. At the 2024 Financial Services Council (FSC) conference, Financial Markets Authority (FMA) chief executive Samantha Barrass spoke about the FMA’s regulatory approach as it takes over oversight of the CCCFA. The CCCFA is important legislation governing responsible lending, and the speech followed the Government’s announcement that the Act would no longer be overseen by the Commerce Commission (ComCom).
Speaking on the theme of “consumer resilience and prosperity”, Barrass outlined the FMA’s regulatory philosophy, saying that “regulation cannot exist for its own sake” and should support economic growth through innovation and reducing unnecessary burdens. “We submitted a list of recommendations to ensure our time and resources are used more effectively while protecting the interests of consumers and investors.”
The history of the CCCFA: debate over the regulatory burden
The CCCFA was first introduced more than twenty years ago, but policy changes in 2021 reignited widespread debate. Those changes aimed to tackle predatory lending practices, but many felt the requirements were too strict and made the lending process cumbersome, treating all borrowers as posing the same risk whether they were applying for a small overdraft or a large mortgage. After the National Party won the 2023 election, CCCFA reform became a priority. By April 2024, Commerce and Consumer Affairs Minister Andrew Bayly had removed some lending affordability requirements and proposed changing the Act’s regulator.
Cooperation between the FMA and ComCom
The Commerce Commission currently remains the CCCFA regulator, but the FMA is working closely with it to gradually transfer credit-related functions. Barrass said the agencies had already undertaken several joint activities to ensure a seamless handover of responsibilities, pending Parliament’s passage of the legislation. The reforms mark a significant turning point in New Zealand’s financial regulation. Barrass concluded: “Our Government clearly recognises that debt is part of life. These reforms aim to simplify access to finance while ensuring good lending practices are upheld.”