
New Zealand home sales are falling, but can homes in one city sell in just 10 days? Interest rates, living costs and migration are reshaping the market
With national home sales falling by more than 20% and prices beginning to retreat, New Zealand’s property market appears to be entering a cooling cycle.
With national home sales falling by more than 20% and prices beginning to retreat, New Zealand’s property market appears to be entering a cooling cycle.
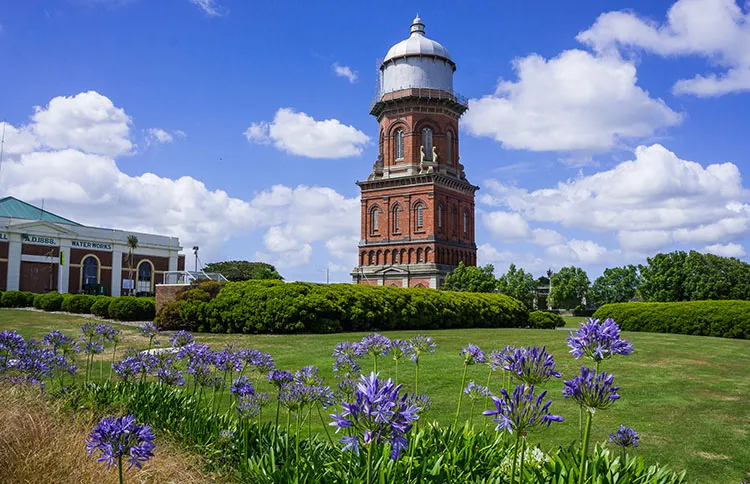
But in Invercargill in the South Island, a different picture is emerging: homes sell in an average of 10 days, and prices have even returned to record highs.
This contrast is redefining how people understand the current housing market.
According to April figures released by the Real Estate Institute of New Zealand, 6262 homes sold nationwide, down 21.2% from the previous month and 7.9% from a year earlier.
Prices are also under pressure. The House Price Index (HPI), which tracks market trends, fell 1.2% month on month and 0.9% year on year in April. The national median price slipped to NZ$775,000, down 1.9% from March.
Auckland was particularly weak: sales fell 29.5% month on month and 14.8% year on year, while its house price index dropped 2.0% in a single month, making it a key drag on the national market.
Heading into winter, this performance is difficult to explain as a short-term fluctuation.
Yet shifting the focus from national figures to individual regions reveals a completely different picture.
In Invercargill, the property market is moving at a different pace.
The latest figures show that local homes take an average of just 10 days to sell, compared with 23 days nationally, making sales more than twice as fast.
Prices are strengthening too. Local house prices rose 3% over the past three months and 9.5% year on year. They have returned to their post-pandemic peak, making Invercargill one of the few cities still at peak prices.
While the national market is slowing, this southern city is accelerating, with supply and demand playing a key role. In April, local listings fell 1.4% year on year, while demand grew 7.7%, leaving demand clearly outstripping supply.
Transaction behaviour suggests the market has not truly cooled; it is adjusting.
Independent economist Tony Alexander’s latest survey shows that first-home buyers remain active, but are becoming more cautious. Previously, 54% of mortgage advisers reported a decline in first-home buyers; that proportion has now fallen to 16%.
In other words, these buyers have not left the market, but they are no longer buying blindly.
Meanwhile, investor participation remains noticeably weak. Around 48% of advisers say investor numbers are still falling, which also helps explain why overall sales volumes are struggling to recover.
However, the picture differs in areas such as Invercargill. Figures show that first-home buyers account for 30% of sales, above the national average, while owners of multiple properties, or investors, account for 28.7%. With yields reaching around 5.7%, above the national figure of roughly 4.6%, some investors are beginning to return.
Taking a wider view, this market divergence is no coincidence.
First, interest rate expectations have shifted. The market is moving from a rate-cutting cycle towards an environment of possible rate rises, directly weakening a key driver of the housing market’s recovery in 2025.
Second, living costs continue to exert pressure. Rising fuel, food, insurance and council rates costs are reducing purchasing power and making buyers more cautious.
At the same time, however, another force is providing a counterweight.
Data shows that New Zealand recorded a net migration gain of 12,178 people in the first quarter of this year, up a substantial 182% year on year and the largest quarterly gain in two years. This included a net inflow of 21,667 non-New Zealand citizens.
The population is growing, so housing demand is theoretically rising. Yet even as demand grows, purchasing power is being constrained. This is the central tension in the current market.
Observations and reflections: the market is being redistributed
Looking only at national data, it is easy to conclude that the market is cooling. But when different regions, buyer groups and the underlying macroeconomic variables are considered together, that conclusion starts to look incomplete.
Market conditions are diverging: some areas are slowing while others accelerate. Capital flows are changing too. Some people are leaving because of interest rates and costs, while others are returning in search of yields and opportunities.
What pace is your local market moving at?