
Bernald’s Property Picks: a rare opportunity! A large, subdividable site in a sought-after suburb goes to auction — golden rules to help you choose land with confidence!
Natural beauty, tranquillity and harmony… In coveted Mission Bay, this could be the last site to fulfil your dream of a luxury home on a large section.
Who is Bernald?
In 2021, Liang Lixing (Bernald Leung) bought his first New Zealand property at the age of 21. He has since been active in the property market for 20 years and is a well-known property investment expert and experienced residential and commercial property manager.
Bernald believes success and good fortune come to those who persistently seek opportunities. For 20 years, he has personally attended open homes every week, viewing countless properties.
YIJU has teamed up with Bernald to launch “Bernald’s Property Picks”, a column sharing properties worth investing in as they become available. Alongside case studies, it shares with YIJU readers the “golden rules for choosing property” that Bernald has distilled from years of practical experience. We believe this column can help you become a clear winner in property investment too!
- Views of the site
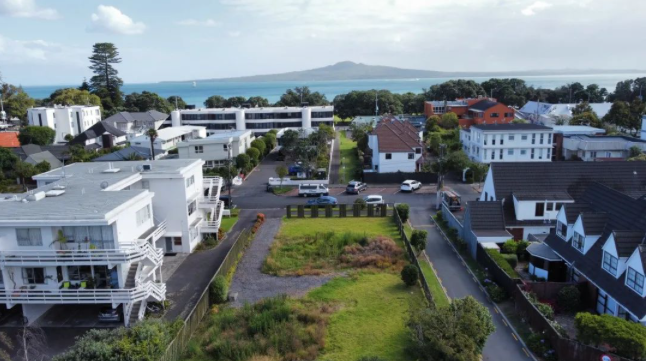
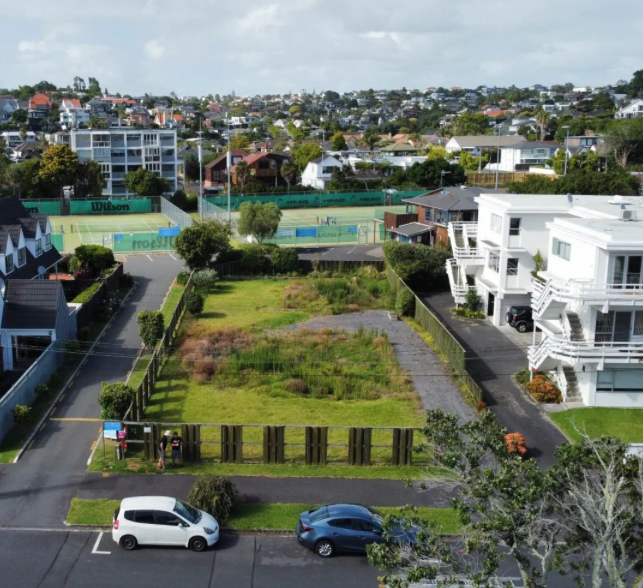
Location: 11 Marau Crescent, Mission Bay
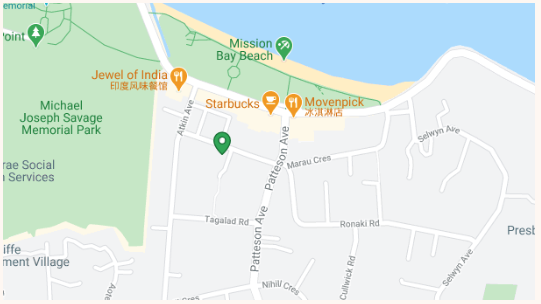
Land area: approximately 683 m2
Proposed zone: H5 Residential – Mixed Housing Urban Zone (H5 Residential – Mixed Housing Urban Zone)
Land use: fully detached or semi-detached residential houses
Capital value (CV): NZ$1,700,000 (2017?)
Last sale price: NZ$2,480,000 (2019.12.12)
Auction time: 8 April at 10am
Auction venue: 50 Remuera Road, Remuera
- Site highlights
Mission Bay is a premier seaside lifestyle haven, combining a boardwalk, water sports, swimming, diverse restaurants, bars, cafés and a cinema. With excellent school zones and convenient transport, it has always been a dream location for developers, builders and home-buying families. Within walking distance of the Mission Bay waterfront and just one street back from Tamaki Drive, this is the closest and only undeveloped site to Mission Bay beach — an excellent choice for enjoying a rural-style lifestyle property while living in the city.
- 2 sections are being sold together, covering approximately 683 square metres.
- Freedom to plan a standalone home or multiple residential units.
- Just 15 minutes’ drive from Britomart and the CBD.
- Convenient public transport to the Eastern Bay suburbs.
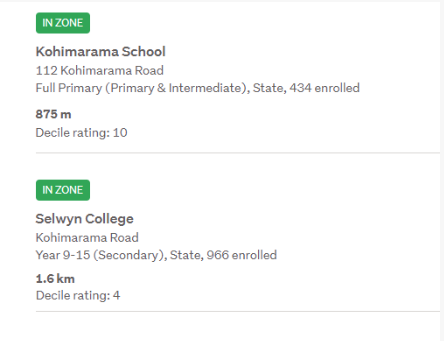
- Zoned for Kohimarama School, St Thomas’s School and Selwyn College, with well-known early childhood centres nearby.
Bernald’s golden rules
— Location and subdivision potential determine land value
What should you look at when deciding whether land has investment value and is worth buying?
The most important factor is, of course, location, location, location — it bears repeating three times. In this case, Mission Bay’s outstanding location is beyond question, and this site is an exceptionally rare find. Rather than discussing location further, let us look specifically at how zoning affects land value — in other words, how to profit by building more homes in a prime location.
The Mixed Housing Urban Zone covering this site is central to the Unitary Plan’s aim of increasing Auckland’s overall residential density. Housing in this zone was originally low-density; now, more homes can be built on the same land. Under the current Unitary Plan, homes in the Mixed Housing Urban Zone that meet all relevant standards can turn a single existing site into up to four homes without applying for resource consent. They can also be built higher! The zone allows buildings up to 3 storeys, with an average height limit of 11 metres.
In other words, provided building scale and outdoor space are sensibly balanced, this Mission Bay site has the potential to turn a single home into four, with specific plans tailored to requirements. Creating five homes or subdividing further would require resource consent.
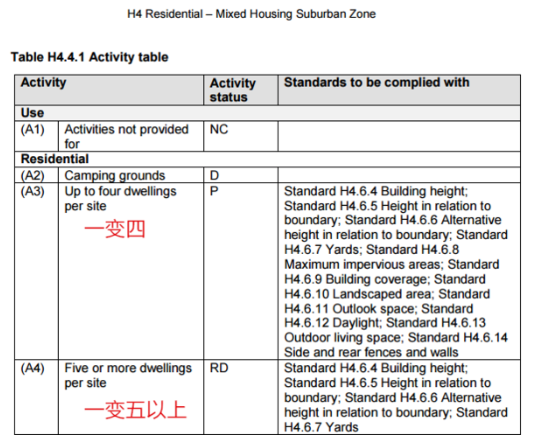
The Mixed Housing Urban Zone currently covers around 30% of Auckland, near townhouse and apartment areas and public transport facilities. It offers enormous development opportunities because it permits a range of housing, from low-rise apartments of 2–3 storeys to standalone houses.
Before deciding to buy and develop, however, I recommend thinking carefully about the following questions:
- What do I want to build?
- What type of development do I want to create?
- Where do I want to build?
For more information about the Mixed Housing Urban Zone, visit:
Beyond the recent enthusiasm for subdivision and development, a “buy and hold” strategy also applies to land, just as it does to shares and similar investments. Buying this site now and holding it for 20 years could very well deliver a substantial return when it is sold.
To generate cash flow, land held under a buy-and-hold strategy can also be leased as a car park, with rental income offsetting bank loan repayments.
— Nearby property sale prices help gauge the eventual selling price
Several properties on the same street sold last year at the following prices:
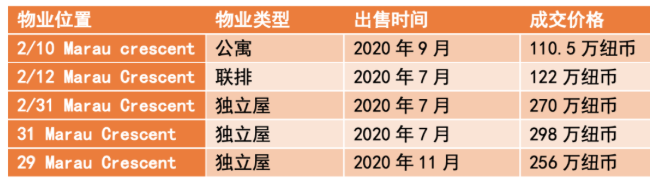
Based on the figures above, I believe a reasonable selling price for this site would be NZ$2,500,000–3,000,000. If you intend to buy land, build and then sell for a profit, remember to consider land and construction costs together.
— Assess the risks thoroughly before buying
Of course, investing in land brings both opportunities and risks, just like investing in shares:
Unlike buying a house and renting it out to generate cash flow, buying and developing land means allowing for the fact that it will produce no income until the homes are completed. Running out of cash is a potentially major risk.
If you need a bank loan to buy the land, you may also face financial risks:
• Interest rates may rise, reducing your property profits.
• Circumstances beyond your control may force you to sell during a housing downturn, leaving you with debt after the sale.
• If the same bank holds the loans on your investment property and your own home, it may sell both properties if you face a debt crisis.
• In particular circumstances, a lender may demand early repayment when the property cannot be sold or its sale value is less than the loan.
{ad}