
New Zealand has the world’s second-highest natural disaster risk! Is your business insured?
Many YIJU readers are successful entrepreneurs based in New Zealand. How to make the most of business insurance to manage risks and prepare for the unexpected is an enduring concern for our business readers. YIJU has therefore invited respected local business insurance advisers to share their knowledge.
Vincent Hsu and Kelvin Ho, senior insurance advisers at New Zealand insurance brokerage Rothbury
YIJU [Q1】:The latest survey data shows that 99% of New Zealand businesses are small or medium-sized enterprises, yet relatively few local Chinese-owned businesses purchase business insurance. Could you briefly explain business insurance?
Vincent is a business insurance adviser and Asian insurance advisory team manager at Rothbury. With more than a decade in the insurance industry, he has provided professional, high-quality insurance broking services to countless local small and medium-sized businesses. He is committed to delivering excellent service to every client, treating each with care and tailoring the best business risk solutions to their needs.
Vincent: Business insurance includes commercial property insurance, business interruption insurance and statutory liability insurance, among other types of cover, which can protect your interests. Vero’s survey data shows that almost a quarter of New Zealand’s small and medium-sized businesses have never purchased any business insurance. In fact, even if your business is performing well now, you still need to plan ahead and arrange insurance for the unexpected.
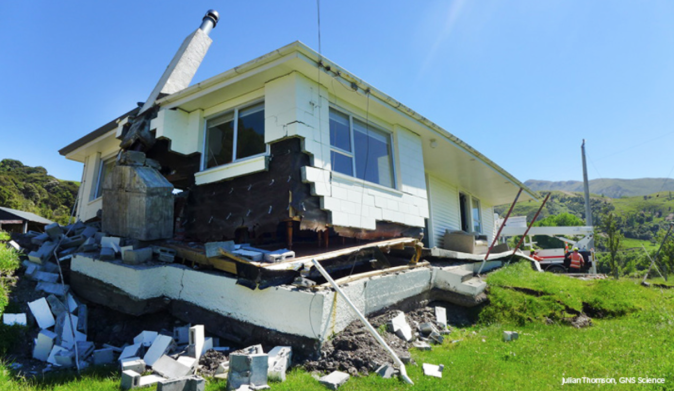
A major issue for business owners is that natural disasters such as fires, floods and earthquakes can prevent normal operations for a period of time. The effects may last weeks, months or even longer, directly affecting every employee and potentially the survival of the whole business. Business interruption insurance is an essential form of business cover that can effectively minimise owners’ losses when this happens.
YIJU [Q2】:New Zealand has the world’s second-highest natural disaster risk, yet a survey of small and medium-sized businesses last year found that only 47% of owners said they had insured against the risks posed by natural disasters. What is your view of these findings?
Vincent: Generally, if equipment needed to run your business is damaged by a natural disaster or accident, preventing normal operations, business interruption insurance compensates you for lost expected gross profit and essential expenses that remain payable during the interruption, such as staff wages and other overheads. Here are two representative examples:
Company A is a hotel with a very high occupancy rate. A sudden flood during the peak tourist season forced it to cancel all bookings. Business interruption insurance compensates for lost gross profit based on the owner’s usual turnover until the business reopens, helping the owner through the disaster.
Recently, a Chinese-owned scaffolding company suffered a theft at a construction site. All its scaffolding was stolen, bringing the project to a halt because the builders could not work normally without it. After a claim was lodged, business interruption insurance promptly compensated the company for its lost gross profit.
Every business has its own characteristics, so insurance recommendations will vary. However, owners of small, medium and large businesses alike should consciously choose suitable business insurance to protect themselves and their companies from unexpected events. Other types of business insurance are also available. We recommend discussing your circumstances with your business insurance broker to understand the different options.
YIJU note: Our editorial team has compiled explanations of the different types of business insurance at the end of this article.
YIJU [Q3】:What specific benefits do small and medium-sized business owners gain from purchasing business insurance through a broker?
Kelvin has worked in the insurance industry for 7 years and is currently a business insurance broker at Rothbury. His extensive underwriting experience helps clients assess risks more accurately and find suitable insurance solutions. Kelvin places great importance on building strong relationships of trust with clients and takes pride in his highly regarded service.
I would say the specific benefits of purchasing business insurance through a broker include the following:
- A thorough understanding of each client’s circumstances, with 1:1 service
Before offering insurance advice, we take time to understand your business carefully, identify what it needs, and tailor an insurance solution.
Extensive resources
We have relationships with a wide range of insurers, enabling us to select policies from many insurance products that suit your circumstances.
Extensive knowledge to minimise risk
Drawing on our detailed understanding of business insurance and extensive knowledge, we recommend cover options and any necessary changes to help minimise your risks.
According to Vero’s latest 2021 survey, New Zealand small and medium-sized business owners value brokers’ services in finding the best policies and value-for-money cover, promptly communicating policy changes, and providing guidance on policies and the scope of claims. These findings affirm the importance of insurance brokers.
73% of small and medium-sized businesses say they have established a relationship of trust with their broker and expect advice on risks specific to their business and the most suitable policies. The survey also shows that businesses working more closely with their brokers are more satisfied with claims outcomes. Among small and medium-sized businesses reporting a good relationship with their broker, 82% of owners believe their insurance offers a strong return.
{ad}
Reference information
Business insurance basics
Commercial property insurance: Protects business assets such as fixed assets and equipment, tools, furniture, cash and stock. It provides protection when these assets suffer sudden damage or are stolen through theft or robbery.
Business interruption insurance: Damage to business premises or equipment, such as buildings and machinery, caused by a natural disaster or accident can interrupt or halt operations, resulting in substantial indirect losses. Business interruption insurance compensates for lost expected gross profit and essential expenses that remain payable during the interruption, helping your business through the disaster.
Public liability insurance: Your business activities may unintentionally harm other people or their property, for example by damaging your landlord’s building, injuring a customer in your shop or causing food poisoning. If a court finds you liable, public liability insurance helps compensate others for their losses.
Statutory liability insurance: If you unintentionally breach certain New Zealand laws or regulations, such as the Fair Trading Act, Consumer Guarantees Act or Privacy Act, statutory liability insurance covers the resulting fines and legal defence costs. However, fines arising from breaches of workplace health and safety legislation are excluded.
Employers’ liability insurance: If an employee suffers physical or mental harm while working for you, ACC does not cover it and a court finds you liable, employers’ liability insurance covers the associated costs.
Looking for professional advice on business insurance?
Scan the QR code below
Contact Rothbury’s Asian insurance broking team
Hassle-free claims
Insurance brokers represent clients, rather than insurers. Experienced brokers handle thousands of claims for clients each year, and their extensive claims experience and knowledge help them secure the best outcomes for clients. Rothbury has dedicated claims advisers, and brokers work with this specialist claims team. When you need to make a claim, a claims adviser provides detailed assistance throughout the process to ensure the insurer settles your claim as quickly as possible.
Disclaimer
The examples cited and all insurance-related content in this article are for reference only.
Please consult a professional insurance broker before arranging cover.
Neither YIJU nor Rothbury accepts any liability.