
Shops and building sites keep being burgled during Level 4 lockdown. What can you do? An expert insurance adviser shares practical advice
Over the past few days, our editorial team has noticed that, alongside the increasingly serious pandemic, many criminals are exploiting the fact that most businesses cannot open under Alert Level 4 to loot their premises! This adds to the hardship of businesses already without trading income because of the pandemic. More infuriating still, many victims are businesses in our Chinese community!
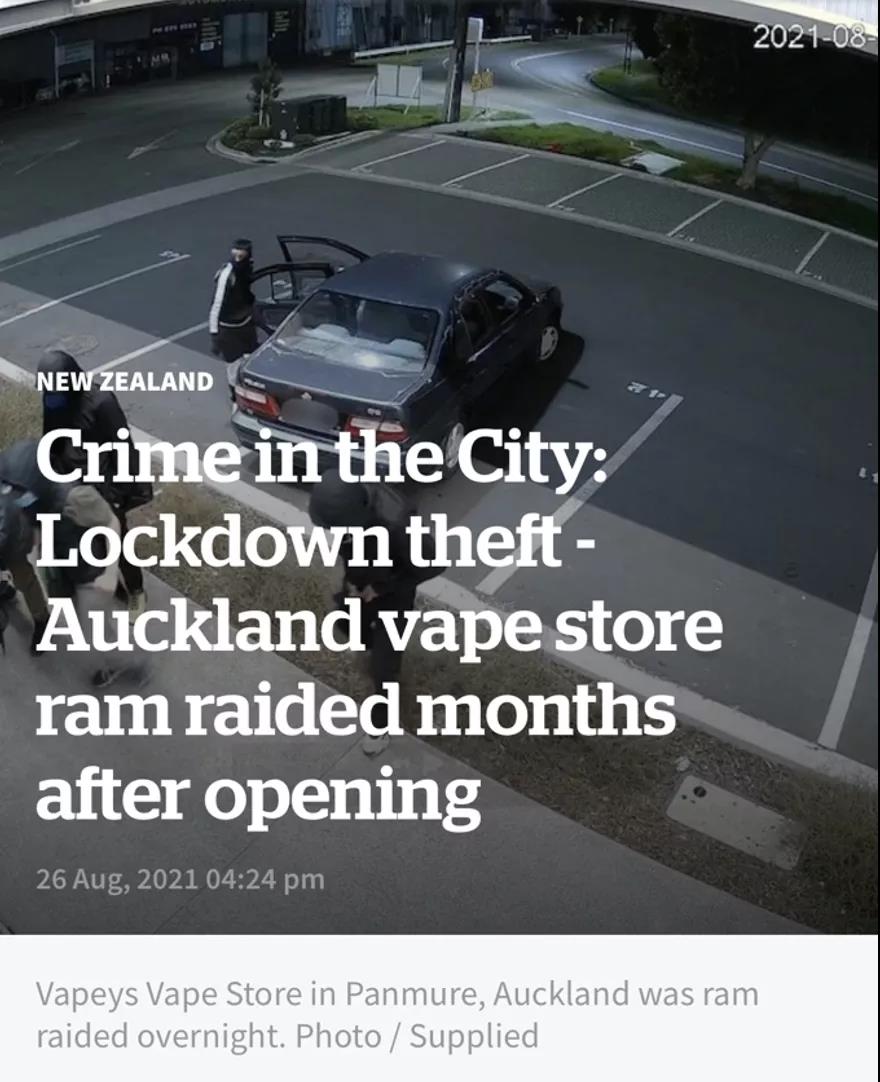
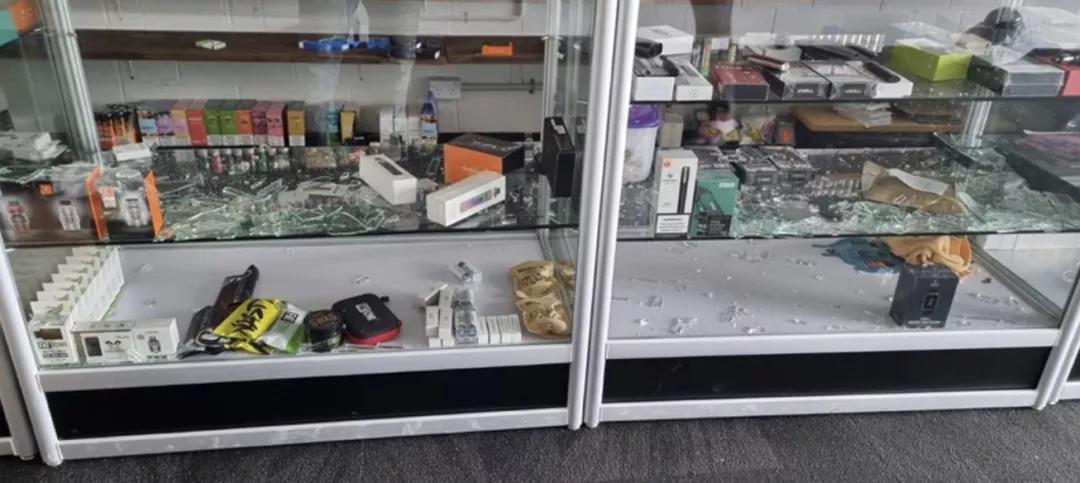
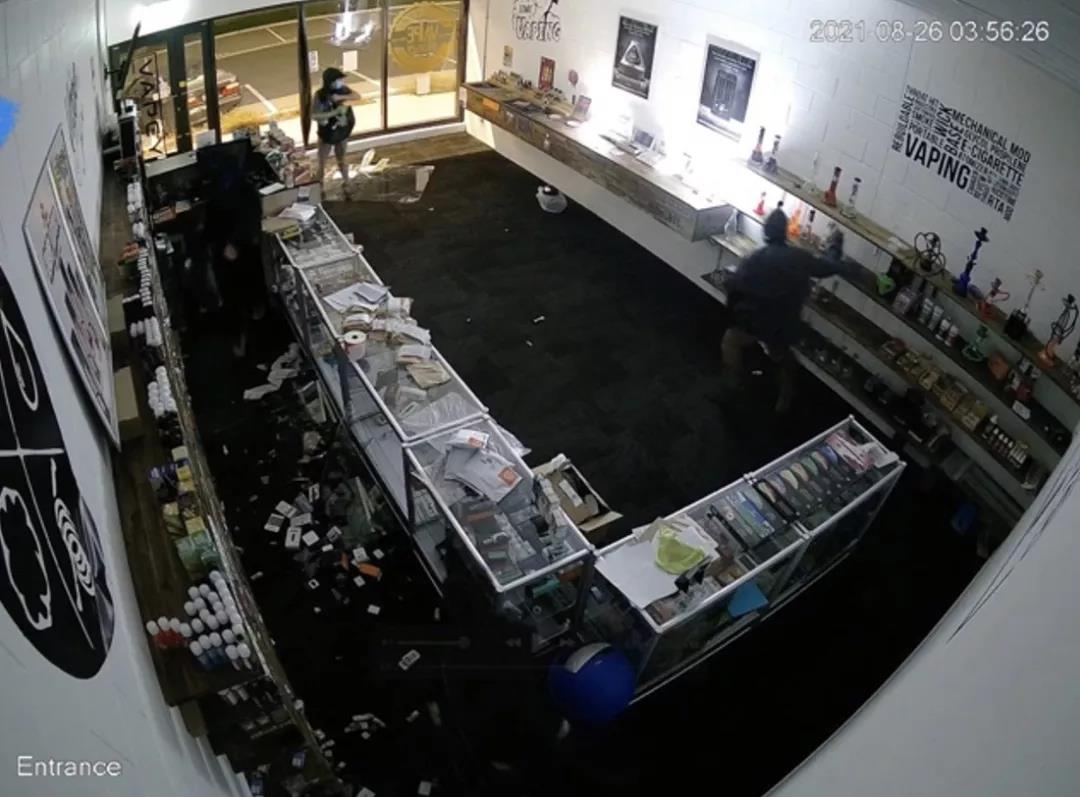
Image credit: NZ Herald
As shown above, an Auckland vape shop that had been open for less than three months was recently ransacked overnight. CCTV footage shows five people wearing hoodies and black clothing driving through the glass entrance before stealing hundreds of products and an unknown amount of cash from Vapeys Vape in Panmure. The owner complained that, with the incident occurring during Level Four lockdown, even finding someone to carry out repairs afterwards was difficult.
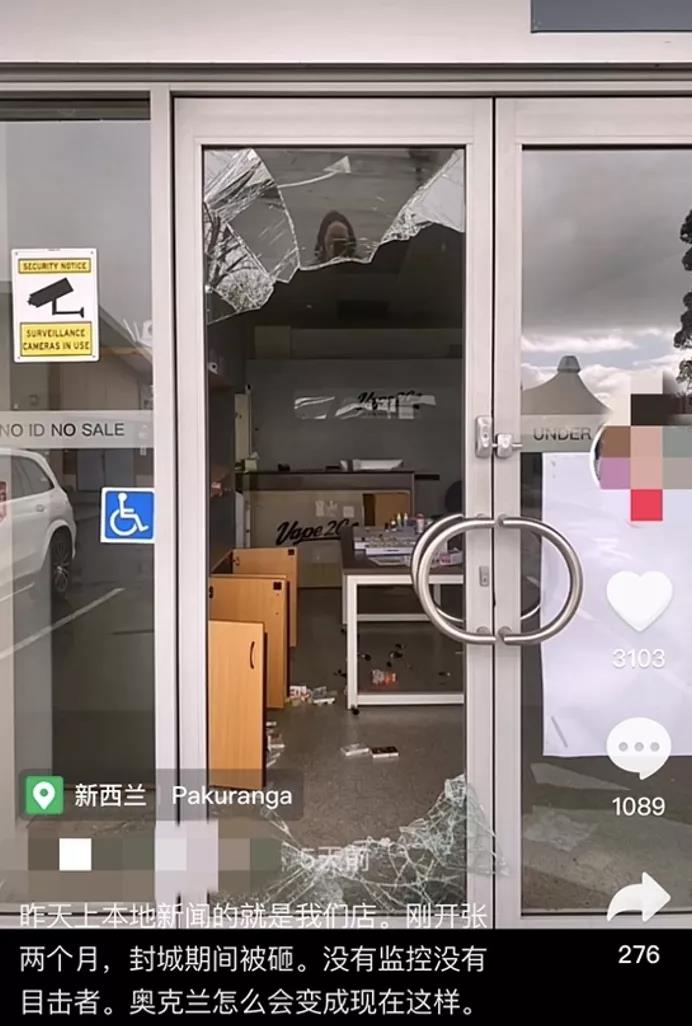
Image credit: Douyin
This was no isolated occurrence. Just a few days earlier, a Chinese-owned Vape2go shop in Pakuranga, which had been open for only two months, was broken into during Level Four lockdown, with no surveillance footage or witnesses. For a business ransacked so soon after opening, this was a devastating blow! We believe these are not isolated cases: a post we have just seen on WeChat Moments shows that building sites run by members of our community have also fallen victim during lockdown.
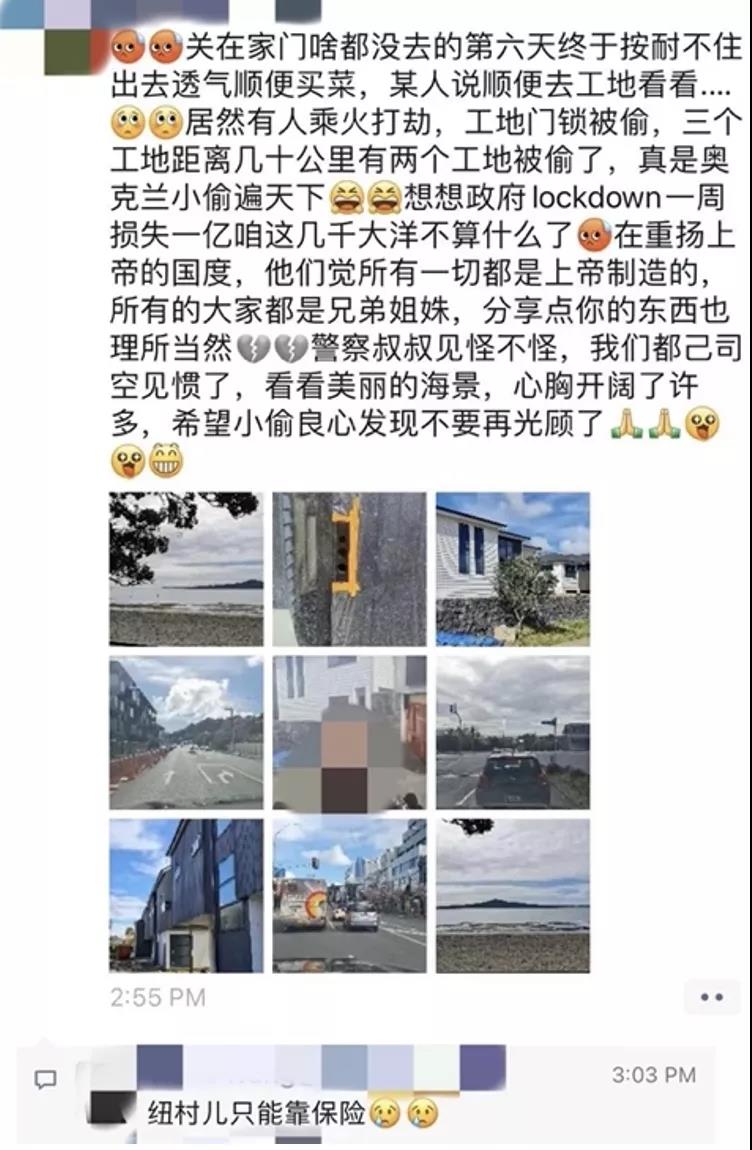
Image credit: WeChat Moments
Under Alert Level Four, it is time for everyone, especially businesses in our Chinese community, to become more vigilant! We spoke to Vincent Hsu, Commercial Insurance Adviser and Asian Division Insurance Adviser Manager at well-known New Zealand commercial insurance brokerage Rothbury, for advice on protecting business property during the pandemic and minimising financial losses after a theft.
Q1: Hello, Vincent. With another Level Four lockdown, we have recently heard of numerous thefts from shops and building sites. What advice can you offer to minimise builders’ losses in these circumstances?
Prevention is always essential! I recommend making sure insurance is in place, with appropriate sums insured, before starting any business activity. Business premises and building sites should both have adequate security measures, such as security locks and CCTV cameras at entrances and exits and along site fencing. I strongly recommend taking this opportunity to reread your policy wording carefully, so you understand which security measures are conditions of cover, what is covered and what is excluded. These measures help reduce the likelihood of theft. If the cover is insufficient, you need to broaden your insurance coverage. One point to emphasise is that theft resulting from personal negligence, such as leaving tools or machinery on site, is not covered by construction insurance. Builders need to arrange other relevant insurance for these items, such as commercial tools insurance (Material Damage) and commercial vehicle insurance that can cover excavators and other machinery.
Q2: You have just discussed insurance for builders. Many builders have faced project delays this year, both because of severe building material shortages and because of the pandemic. Is there any commercial insurance that can provide cover?
Material and labour shortages are common problems in construction. Even before the COVID pandemic, they could cause construction projects to run behind schedule.
As insurance brokers, we regularly remind clients to plan ahead and ensure their insurance period is long enough to accommodate unforeseen events, including material and labour shortages. Other causes of delay can include public holidays, weather, and unexpected problems or delays involving third parties, such as councils, electricity provider Vector, water services provider Watercare or other government agencies.
Our experience with a large number of past clients shows that a very similar construction project that clients could previously finish in four months now takes an additional 3–4 months to complete.
Our best advice is therefore to allow for unforeseen circumstances and make sure you purchase insurance that covers the entire construction period. You could consider business interruption insurance as protection against construction being interrupted by fire or an earthquake, but business interruption insurance does not cover material shortages.
Q3: How do you make a claim when a problem arises? How long does a commercial insurance claim usually take, and what can you do to speed up the process?
I recommend contacting your commercial insurance broker first whenever you have a question about policy wording or claims. The time needed to settle a claim varies according to the circumstances. In principle, the more information you can provide to the insurer assessing your claim, the faster it can review it and settle it promptly and efficiently.
It is particularly important to keep detailed records of all loss or damage, including where and when the incident occurred, and to take photographs on your phone if necessary. Rothbury has put considerable effort into speeding up claims. Most of our clients have already started using the My Rothbury app to send photographs and submit claims quickly.
The type of claim and whether further evidence is required also affect how quickly it progresses. The insurer’s claims handler may ask you for additional supporting documents, such as a police report or proof of purchase.
At Rothbury, whenever we handle a claim, you, your dedicated insurance broker and your claims adviser work together to complete the claim form and provide all necessary supporting documents. This helps achieve the best possible claim outcome and ensures a faster, more efficient process.
Q4: What makes the insurance service offered by Rothbury Insurance Brokers different?
As a local specialist insurance brokerage with a 70-year history, Rothbury has more than 200 experienced staff nationwide providing highly professional service to clients. Every branch has dedicated insurance brokers and claims advisers, while the professional brokers in Rothbury’s Asian Division can provide a fully Chinese-language service. Your broker tailors the most suitable and cost-effective insurance package to your needs. When you need to claim, a claims adviser works closely with you alongside your broker, providing professional support throughout to ensure payment is completed as quickly as possible.
Vincent Hsu is Rothbury’s Commercial Insurance Adviser and Asian Division Insurance Adviser Manager. With more than a decade in the insurance industry, he has provided high-quality, professional insurance broking services to countless local small and medium-sized businesses. He is committed to delivering excellent service to every client, treating each with care and tailoring the best commercial risk solutions to their needs.
Looking for professional advice on commercial insurance?
Scan the QR code below
to contact Rothbury’s Asian insurance broking team
Disclaimer
The examples and all insurance-related content in this article are for reference only.
Please consult a professional insurance broker before arranging cover.
Neither YIJU nor Rothbury accepts any liability.