
Can you still get a bank loan under level 4? With uncertainty over the Reserve Bank’s OCR, where are mortgage rates heading? An industry expert answers your questions
With New Zealand house prices continuing to rise in recent years, ordinary people need to save at least a million New Zealand dollars to buy an average-priced Auckland home outright—equivalent to more than a decade of an ordinary wage earner’s income without spending anything on food or drink. Combined with the recent uncontrolled outbreak, this has left many loyal YIJU New Zealand readers anxious. They have been asking us: where are lending rates heading under level 4 lockdown?
With New Zealand house prices continuing to rise in recent years, ordinary people need to save at least a million New Zealand dollars to buy an average-priced Auckland home outright—equivalent to more than a decade of an ordinary wage earner’s income without spending anything on food or drink. Combined with the recent uncontrolled outbreak, this has left many loyal YIJU New Zealand readers anxious. They have been asking us: where are lending rates heading under level 4 lockdown? Will the outbreak affect applications for new bank loans? Will banks introduce new rules for home and business lending following this renewed outbreak? To answer these questions, we invited York Zhang, founder of Plaxo Mortgages, to share his expertise. We hope this conversation with an industry expert will provide practical insights to help readers plan their next financial steps during the pandemic.
{ad}
Q1: Hello, Mr Zhang, and thank you for joining us. Many readers have recently asked whether the return to level 4 lockdown will make it harder for aspiring homebuyers to get a loan.
Frankly, it will certainly have an impact. Under the additional requirements banks have imposed during previous lockdowns, customers need to confirm that their jobs or businesses have not been affected and will not face adverse consequences from the recent lockdown in future. For prospective applicants who have actually been affected, getting a loan has indeed become harder, or at least there are more matters to consider when applying.
Q2: Does that mean banks will introduce new rules for home and business lending following this renewed outbreak?
We have not heard much about new rules affecting fundamental lending policies so far. But, as mentioned above, banks are certainly very concerned about whether lockdown has affected customers’ incomes, so in practice quite a few requirements have been added.
Q3: Many readers are worried that reduced income or a period of unpaid leave during the pandemic could cause problems with their loan applications. Will it?
Based on past experience, these applicants need to explain clearly how long the impact will last. Is it long term or temporary? Banks may also require confirmation from the current employer that, once the short-term disruption ends, the customer will promptly return to their pre-lockdown income level, allowing the loan application to proceed.
Q4: How are approval times looking at present? Have loan applications become easier or harder for first-home buyers?
In fact, there has been little difference in loan processing times before and after this lockdown, and the market response has been relatively muted. People may already have been mentally prepared for lockdown, so expectations among both buyers and sellers have changed little. Recent sales activity and median sale prices already give some indication of this.
Q5: On the second day of level 4 lockdown, the Reserve Bank announced it would leave the OCR unchanged. How do you interpret this? Could lending rates return to 2% or below? What advice would you give investors considering borrowing in future?
Personally, I believe an OCR increase is inevitable and has merely been postponed because of the unexpected lockdown. Looking at the broader picture, if the whole country is out of lockdown before the next OCR announcement, an increase is certain. The pace of economic recovery, low unemployment and relatively high inflation all point towards higher interest rates. The early bird catches the worm. Whatever happens with Covid or Delta, property investment remains one of the best ways to protect against inflation and currency depreciation. Signals from the Reserve Bank of New Zealand (FMA) also suggest that lending policies and restrictions will only become more numerous, so it is better to act than merely think about it.
Q6: We noticed that, starting on the 26 last week, Plaxo Mortgages held four free educational sessions over four consecutive days on Zoom, discussing “what ordinary New Zealanders need to know about home loans”. The public response was very strong! Could you share some practical insights with YIJU readers too?
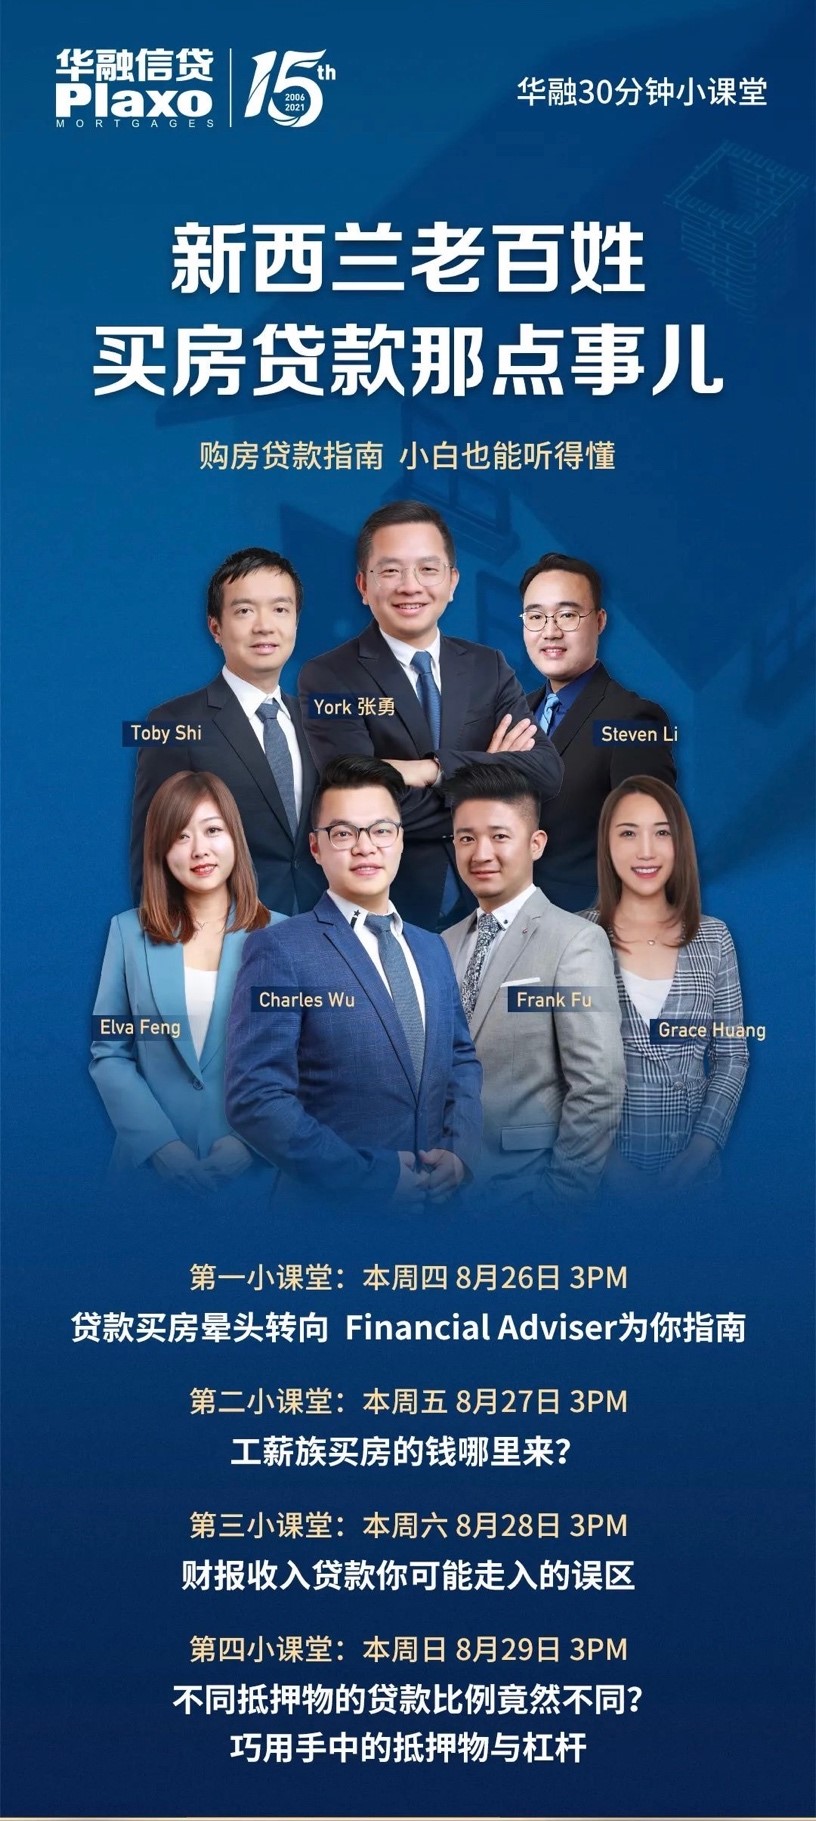
Certainly. Our team’s original intention was to make good use of level 4 lockdown to share insights from our many years in lending. We wanted to avoid lengthy empty talk and difficult concepts, and simply discuss, in language people understand, the key home-loan questions that matter most to wage earners. Whether you are buying your first home to live in or an investment property, we hope the expertise of each of our financial advisers will provide professional, reliable guidance on your property journey.
Our first speaker was Plaxo Mortgages financial adviser Steven Li. He began by explaining the role and responsibilities of a licensed financial adviser and how these differ from what people generally call a mortgage broker. He then explained the process of buying a first home in New Zealand, moving from the basics to more detailed points and illustrating them with real examples.
First episode video
https://v.qq.com/x/page/n3272xcld7s.html
The second session featured our financial advisers Elva Feng and Frank Fu. Together, they explored where wage earners’ homebuying funds come from, focusing on how banks assess PAYE income and how everyday spending affects the amount applicants can borrow. It was packed with practical information!
Second episode video
https://v.qq.com/x/page/j3272gv3ang.html
In the third session, our financial advisers Charles Wu and Grace Huang explained how self-employed people can avoid pitfalls when banks assess their income and business financial statements. We know that many Chinese New Zealanders are self-employed professionals who can easily encounter difficulties when applying for home loans. We hope this episode will help more self-employed applicants avoid unnecessary setbacks.
Third episode video
https://v.qq.com/x/page/e3272s1o5qe.html
The fourth session, presented by our financial adviser Toby Shi, covered secured lending and how to make effective use of collateral and leverage. What documentation do banks require for collateral? What documents must a bank see before you bid at auction? Viewers can find answers to these and other questions in the fourth video.
Fourth episode video
https://v.qq.com/x/page/o3272yqhp3u.html
We would remind readers that every loan application is different. If you have lending questions not covered above, consult an appropriately licensed financial adviser for professional advice.
Plaxo Mortgages Plaxo Mortgages
About the expert
York Zhang (Zhang Yong)
Chairman of Plaxo Mortgages
In 2006, York Zhang founded Plaxo Mortgages to provide the Chinese community with loans for homes, construction, businesses, land development, vehicles and large equipment. Combining his mortgage broking expertise with his personal experience of life in New Zealand, York Zhang hopes to use Plaxo Mortgages to bring more products tailored to the Chinese community’s circumstances and needs to the market, develop more outstanding mortgage brokers and unlock more funds from Chinese clients’ assets for reinvestment.