
After the storm: how are west Auckland homeowners whose houses were half-submerged faring now?...
Remember the torrential rain and flooding a few weeks ago that turned west Auckland into a sea overnight? The storm damaged more than 5500 homes in west Auckland.
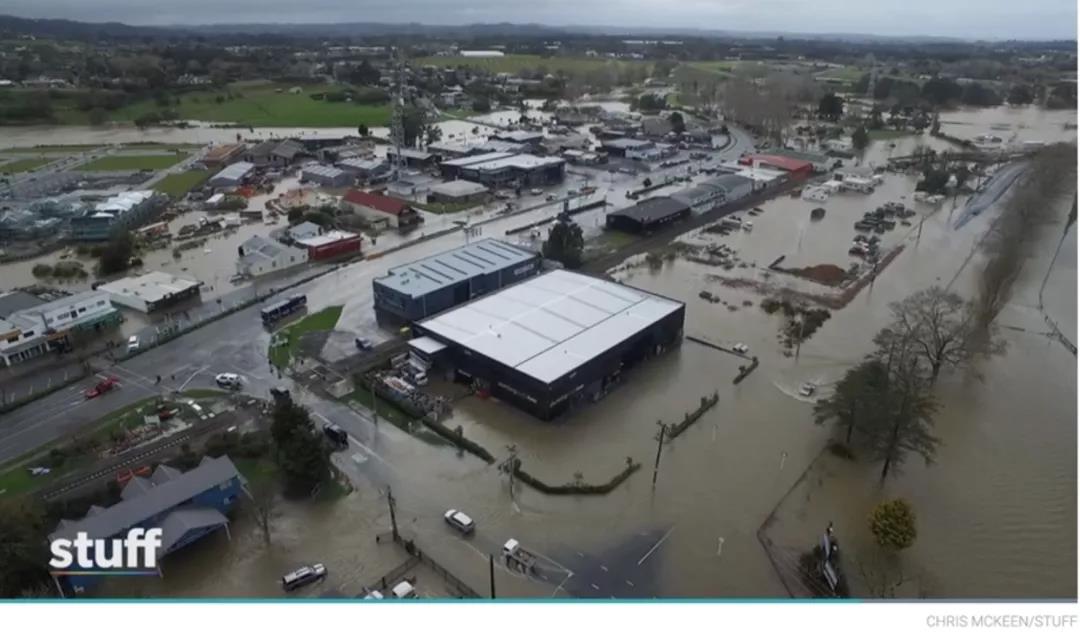
According to the National Institute of Water and Atmospheric Research, parts of west Auckland received 260 mm of rain in a single day, exceeding the usual average daily rainfall for August by 149%. It was the second-highest reading since records began in 1943.
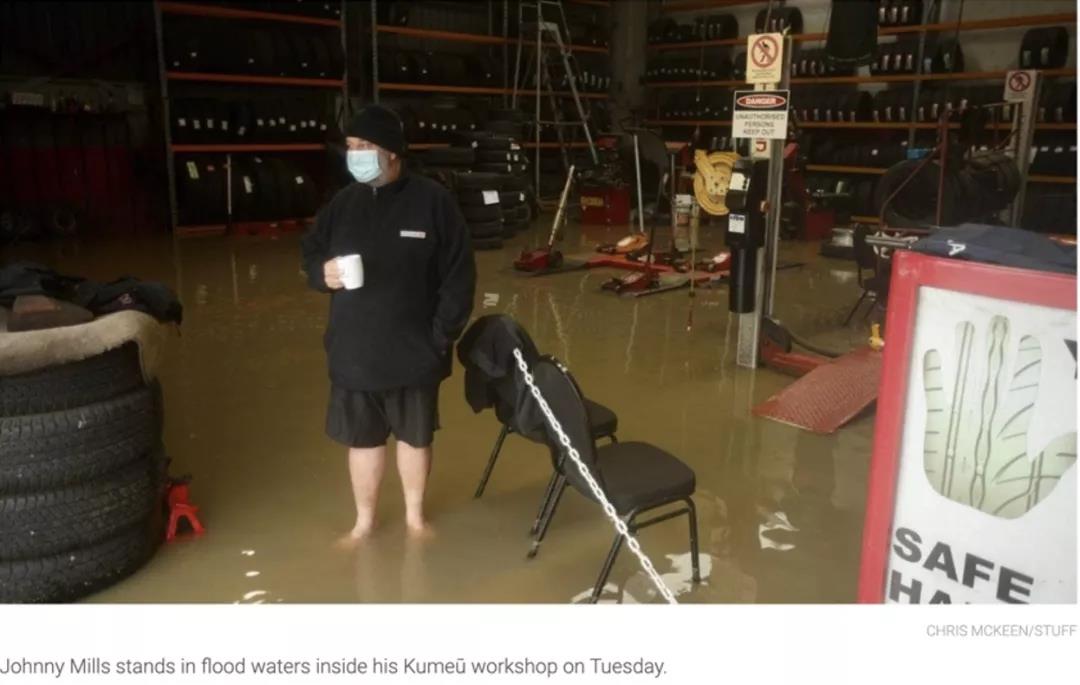
Several businesses suffered severe damage in the hard-hit Kumeū area. Bridgestone owner Mills estimated his business's flood losses at NZ$100,000. Even so, he said they had suffered relatively little compared with other businesses facing serious losses. “Many shops were badly flooded. A great many businesses will be hit hard by this flooding,” he said.
To make matters worse, the flooding occurred during Auckland's alert level four lockdown, making it extremely difficult for insurers to assess the damage.
After the disaster, Insurance Council of New Zealand Chief Executive Tim Grafton said: “Whatever the alert level restrictions, insurers will help their policyholders during lockdown.” Nevertheless, businesses facing unprecedented flooding would inevitably feel anxious and helpless when dealing with insurers to make claims, unsure where to start or how to submit a claim that would secure a prompt, efficient payout.
YIJU therefore interviewed Xu Li, a senior commercial insurance adviser at well-known New Zealand insurance brokerage Rothbury, to share a flood insurance claim case study, along with advice and points to bear in mind when making a claim.
Xu Li shared the following case of a flood-affected west Auckland business that, with coordination and assistance from a Rothbury insurance adviser, swiftly completed its loss assessment during lockdown and received a satisfactory payout.
The company's warehouse in Kumue, west Auckland, was inundated during the Auckland floods. Most of the stock and property inside were damaged, leaving the business with substantial financial losses.
To help the business make a claim as quickly as possible, a Rothbury claims adviser urgently lodged the claim with the insurer by telephone. The adviser also recommended that the business promptly photograph the damaged property and submit the images to the insurer as evidence supporting its claim.
After the claim was lodged, however, the insurer's loss adjuster was unable to visit the site because of alert level four restrictions. To secure a prompt settlement for the affected business, the insurance adviser worked to coordinate a solution with the insurer and loss adjuster. Ultimately, completing a series of pandemic-related questionnaires and a safety declaration enabled the adjuster to assess and investigate the losses during lockdown.
Here is one small detail from the claims process:
The business had a forklift worth approximately NZ$15,000 in its warehouse, normally used to move goods. It was also damaged in the flood. The insurer initially considered the forklift uninsured because the business had purchased only Material Damage Cover, without Commercial Motor Vehicle Cover that would cover the forklift. It said the electrically powered forklift fell outside the scope of Material Damage Cover and therefore declined compensation.
However, after investigating the forklift and gathering evidence, the business's insurance adviser drew on a thorough understanding of the policy wording and immediately made a strong case to the insurer and loss adjuster. Using photographs and evidence of the forklift's functions and characteristics, the adviser demonstrated that it was not a conventional forklift but should be classified as a portable commercial tool: electrically powered warehouse equipment. The adviser's professionalism and dedication deserve applause!
After reassessing the forklift's details and photographs, the insurer ultimately agreed to compensate for it as plant machinery.
If you are reading this and were also unfortunate enough to be affected by the floods, we hope this real insurance claim case helps you. Xu Li also shared some suggestions for communicating effectively with your insurance adviser and securing a prompt insurance payout:
01
Professional insurance advisers will do everything they can to secure the best outcome for their clients. Your role is to communicate actively with your adviser and cooperate with them as they work on your behalf. If anything changes with your insured property, tell your adviser immediately so they can better plan your cover and help you prepare for the unexpected!
02
When making a claim, prepare copies of receipts or instruction manuals for damaged items, particularly when the damage is so severe that the items cannot be clearly identified in photographs.
03
Provide as much detail as possible about damaged items, such as the brand, model, place and date of purchase, and manufacturer's serial number.
04
Provide written quotes for replacing or repairing damaged items.
Meet the expert
Xu Li
Insurance adviser
Xu Li has worked in insurance for 20 years and joined Rothbury 8 years ago. Through her professional, friendly service and comprehensive understanding of the market, she has spent years working to provide clients with the best insurance solutions, building a strong reputation and a large client base.
Looking for professional advice on commercial insurance?
Scan the QR code below
Contact Rothbury's Asian insurance broking team
Disclaimer: The case study and all insurance-related content in this article are provided for reference only. Please consult a professional insurance broker about your specific insurance arrangements. Neither YIJU nor Rothbury accepts any liability.