
Industry experts offer a different perspective on the shared-equity home purchase scheme
Over the past couple of days, my social media feed has been awash with heated discussion: “New Zealand is taking a huge step towards ‘communism’!
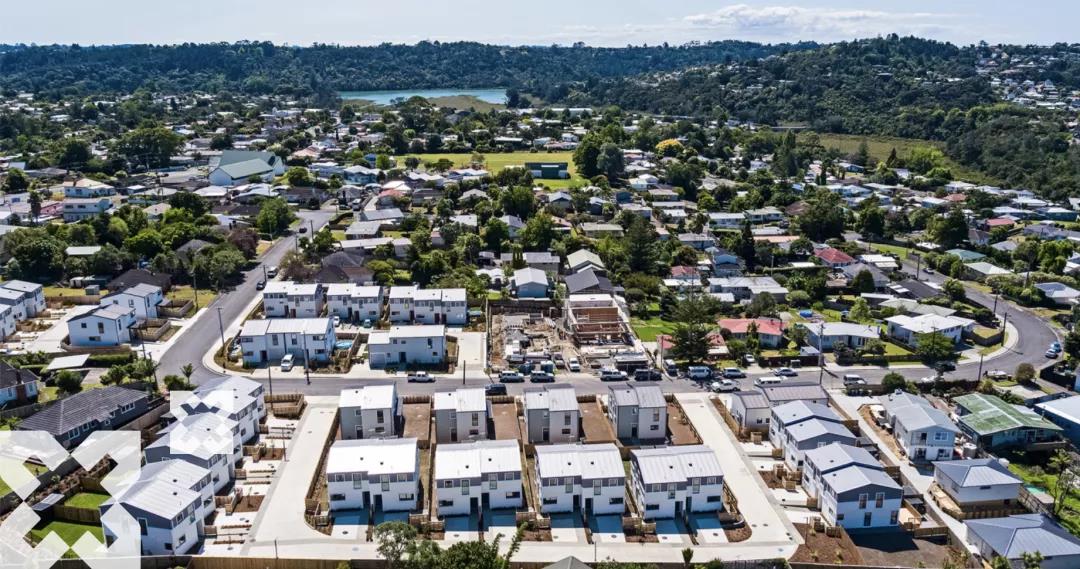
The Government is even paying our house deposits!” “If I invest in a home alongside the Government, I surely can't lose. I'll never have to worry about falling house prices again!” Well, on the road towards home ownership for everyone, the New Zealand Government has once again stepped in to right a wrong! But hold on — whether this really delivers “communism” remains to be seen. First, let's look at what Kāinga Ora actually is and what motivates it.
In Māori, Kāinga Ora means wellbeing at home through places and communities.
Kāinga Ora brings together the people and other resources of KiwiBuild, Housing New Zealand and its development subsidiary, Hobsonville Land Company. The aim is to make the Government's housing and urban development efforts in New Zealand more cohesive and achieve its planning priorities sooner. These include addressing the imbalance between housing supply and demand and making housing more affordable for New Zealanders.
Kāinga Ora has two key roles.
{ad}
1
The first is to be a world-class public housing landlord. Kāinga Ora provides tenancy services to around 187,000 public housing tenants and maintains and develops around 65,000 public homes, while also providing home ownership and other services. We focus on prioritising tenants' wellbeing and providing them with quality homes that are warm, dry and healthy.
2
The second is to work with communities where development is taking place, Māori, local and central government, and others on urban development projects of all sizes. Kāinga Ora also focuses on delivering high-quality urban development that connects homes with jobs, transport, open spaces and the facilities communities need. This includes accelerating the supply of land ready for building and developing a mix of homes of different types, sizes and tenures, including public housing, affordable housing, homes for first-home buyers and market housing.
Over the next four years, Kāinga Ora will add a net 1100 homes annually, with its building programme accounting for 7% of New Zealand's residential construction. Its total assets are worth NZ$26,800,000,000.
At the end of 2019, the Government introduced a supplementary bill, delivering what it called “the power of partnering differently” through a shared-equity home purchase scheme. At the heart of the scheme is a requirement for buyers to gradually buy back Kāinga Ora's share over the coming years. Kāinga Ora can contribute up to NZ$200,000 or 25% of the home's purchase price, whichever is lower. Applicants must obtain mortgage approval from a participating bank, BNZ or Westpac, and need a deposit of at least 5%.
Of course, buyers must meet specific eligibility criteria, and the scheme carries numerous restrictions. Their combined household income before tax must be below NZ$130,000. They must either be first-home buyers or currently own no home and have realisable assets worth no more than 20% of the house price cap for the area where they are buying. The home must be newly built. However, Kāinga Ora says the Ministry of Housing and Urban Development will consider allowing purchases of existing homes on a “case-by-case basis” where those homes in the area were completed no more than a year earlier.
Owners cannot rent out the home, but they can take in flatmates or boarders. While Kāinga Ora holds a share in the home, owners must obtain its approval before selling. Sale proceeds will be divided in proportion to each party's share. Owners must also commit to living in the home for at least three years. If their circumstances change and they need to move sooner, they must apply to Kāinga Ora, which will assess their situation on a “case-by-case basis”. Owners must also obtain Kāinga Ora's approval before undertaking renovations or any building work. They must allow Kāinga Ora to enter and inspect the home for any property maintenance and repairs.
I still have reservations about this development programme. After all, the Labour Government once confidently announced its KiwiBuild plan to build 100,000 affordable homes within 10 years, only to abandon its overly “ambitious” target. So is the Government's shared-equity home purchase scheme truly workable, and can it really help countless New Zealand renters fulfil their dream of buying their first home? YIJU New Zealand spoke remotely with several experienced construction professionals in the property industry for an in-depth discussion:
Q1: Headlines over the past couple of days have declared that New Zealand is entering an era of housing communism. Is that really the case? How do you interpret the scheme?
Frank Xu:I don't think we have entered an era of communism. Market house prices are currently far above the limits set by KiwiBuild. This policy helps first-home buyers afford homes at those market values.
Frank Li:I think there are still many unknowns. For example, how widely will the scheme's benefits extend? Can everyone who meets the criteria apply? How long will the waiting list be? Is there a limit on the Government's total contribution?
York Zhang: As mortgage brokers, we usually need to arrange lending for 80% of a home's total price. For ordinary people, even a 20% deposit is a substantial sum. Over the years, our company has helped many clients who needed loans covering 90% or even more of the purchase price. Our “White Collar Loan” product, for example, helps salaried workers realise their dream of home ownership. The Government's new policy lowers the deposit threshold.
Q2: Will the scheme affect the mainstream mortgage market? Will these applicants no longer need mortgage brokers? Does having only BNZ and Westpac participate create a monopoly and disadvantage other banks?
York Zhang:This policy should be positive for brokers. First, the Government needs to assess first-home buyers' eligibility for lending. Second, banks need to approve the loans. Third, buyers still need to find a suitable home. I believe brokers play an important role in this process. We will become busier helping more first-home buyers achieve their home ownership dreams. People buying for the first time are unfamiliar with many aspects of the process, and our years of experience allow us to provide professional advice and services. Only BNZ and Westpac are participating at present, but I believe other banks will follow as the policy is implemented further. That will take some time.
Q3: Do you think the impact on your company and New Zealand property prices will be significant?
Frank Xu:This new policy will certainly help some eligible first-home buyers purchase new homes. Its impact on the market will also be limited because it uses a more market-based approach to help first-home buyers afford homes at current prices. Rather than imposing price restrictions as KiwiBuild did, it subsidises first-home buyers so they can afford these homes. In that sense, it is a very good policy.
Frank Li:As developers, we welcome any policy that makes it easier for people to buy their first home. But the Government needs to get the details right. It must deliver more than grand promises with little action, and avoid an unfair outcome in which only a tiny minority benefits.
Q4: What negative effects could this cause? Could the measure push house prices beyond more people's reach rather than effectively stabilising them?
Frank Xu:It is a good policy for first-home buyers and will increase their willingness to buy. However, I think its overall market impact will be very small, with limited effects, positive or negative. Its ability to stabilise house prices will likewise be very limited. Market prices are mainly determined by supply and demand, along with building material and labour costs. The new policy does not significantly affect either of these factors, so it will not have a major impact on house prices.
Frank Li:As I said, the Government needs to release detailed rules to answer the following questions:
- Does the contribution of up to NZ$200,000 per home come entirely from taxpayers? Every taxpayer should be concerned about whether that money is used reasonably and fairly.
- Could it cause short-term house price fluctuations and an imbalance between supply and demand, for example in the market for new homes below $1,000,000? That depends on how widely the policy applies.
- If the scheme has broad reach, with buyers needing only a 5% deposit and the Government covering $200,000 or 25% of the lending, it could push prospective buyers to use the maximum contribution and focus solely on new homes priced at $800,000. This would create a shortage of properties at the $800,000 price point, inevitably pushing up the prices of cheaper properties and making homes below $800,000 harder to find.
- There is also repayment risk. As the remaining 70% still requires a bank loan, the policy would inevitably require the Government to bear repayment risk for the first 15 years while using taxpayers' money. If buyers cannot repay their bank loans, will the Government use more taxpayer funds to cover the shortfall? The risk the Government must bear is therefore another issue.
If the scheme benefits only a small number of people, it will never resolve the fundamental imbalance between supply and demand in New Zealand's property market.
York Zhang:I believe the Government must have considered these issues before announcing the policy. If it helps most people, it is a good government initiative. As for house prices rising or falling, would they necessarily fall without this policy? Not necessarily. We often say it takes one or two million dollars to buy a home, but there are also cheaper two-bedroom and three-bedroom homes, or properties in outlying areas. Overall, I think this policy is very positive.