
Investors alarmed as another bill passes: is New Zealand’s housing market losing its appeal?
On 17 March, New Zealand’s Parliament passed a controversial bill abolishing the long-standing policy allowing interest deductions for rental properties.
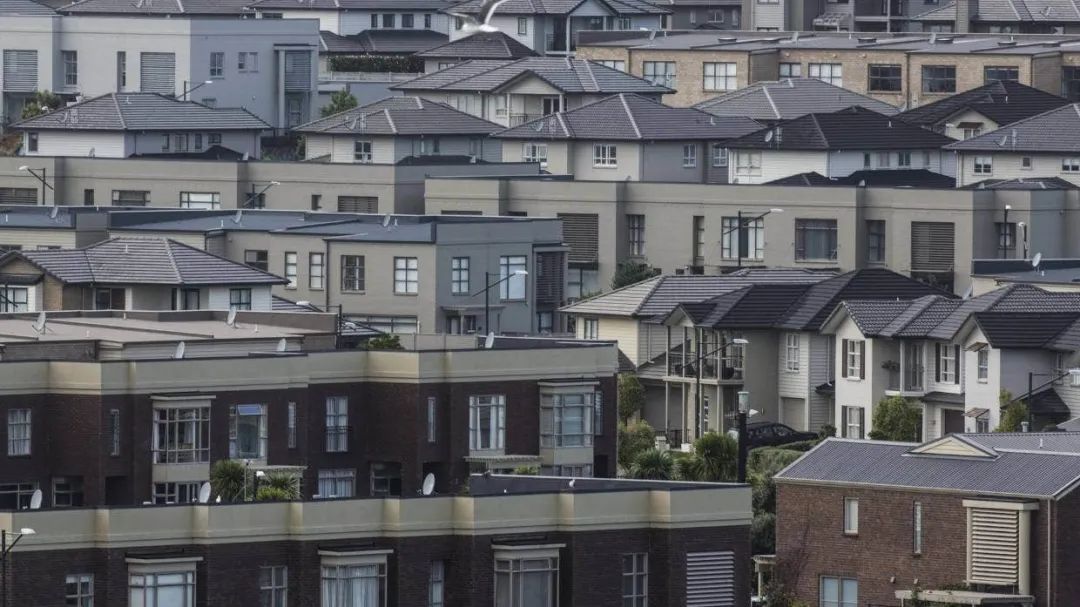
3 On day 17 of the month, New Zealand’s Parliament passed a controversial bill abolishing the long-standing policy allowing interest deductions for rental properties.
To tackle runaway house prices, the Labour Government announced plans as early as March last year to reform the tax system and remove preferential treatment for property investors.
New Zealand is, after all, among the few OECD countries without a capital gains tax. Yet implementing this bill essentially amounts to a loosely structured, indirect capital gains tax.
{ad}
Alongside tax reform, the New Zealand Government has extended the bright-line period. Under the latest rules, properties purchased after 27 March 2021 have a bright-line period of 10 years. This means owners who sell residential properties they have held for less than 10 years must pay tax on the gains, with an exception for their main home.
These rules will undoubtedly increase landlords’ costs of holding investment properties. For ordinary investors, borrowing is the largest cost, so being able to deduct loan interest as an expense makes their position somewhat easier. Now, perhaps only well-funded cash buyers can enter the market with full confidence.
Finance Minister Grant Robertson said the passage of the Taxation (Annual Rates for 2021–22, GST, and Remedial Matters) Bill was intended to curb investor demand while encouraging the supply of new homes.
He said: ‘We want to create a level playing field that allows first-home buyers to get onto the property ladder, while ensuring we do not create barriers to supply.’
He said the bill included exemptions, with commercial land, property developers and new builds, for example, excluded from its restrictions.
New builds are understood to mean properties that received a code compliance certificate (CCC) on or after 27 March 2020. The bright-line period for new builds will also be shortened from 10 years to 5 years.
The property types mentioned above, along with property developers, will remain eligible for interest deductions.
The specific reforms are as follows
Under the new rules, interest deductions will no longer be available from 1 October 2021 for residential properties purchased on or after 27 March 2021.
For properties purchased before 27 March 2021, the amount landlords can deduct will gradually decrease over the coming years:
From 1 October 2021 to 31 March 2023, 75% of interest can be deducted.
From 1 April 2023 to 31 March 2024, 50% of interest can be deducted.
From 1 April 2024 to 31 March 2025, 25% of interest can be deducted.
After 1 April 2025, interest deductions will be abolished entirely. This means that in the 2025–2026 financial year and subsequent financial years, landlords will be unable to deduct any interest expenses from rental income.
Although the bill has only just passed, the relevant rules will apply retrospectively from 1 October 2021 once enacted.
Tax experts say investors hold properties in different ways, so the effects will vary according to individual circumstances.
We consulted an industry professional about the bill’s implications:
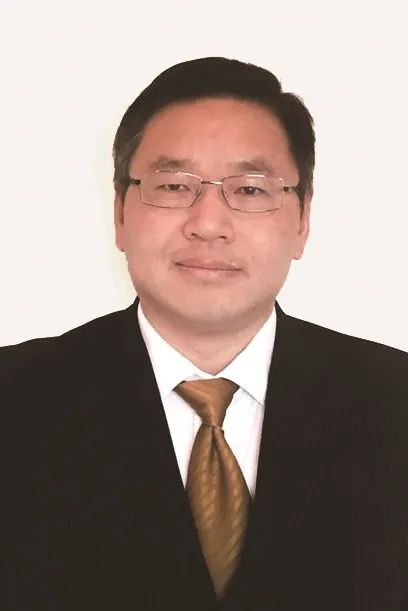
President of the New Zealand Chinese Building Industry Association
Frank Xu
Q1: Do you think investors’ property holding costs will rise substantially once the tax reforms take effect?
They will certainly increase the cost of holding rental properties, particularly for short-term investors and those who purchased existing homes after 27 March 2020. Over the next three to four years, investment property owners’ holding costs will undoubtedly continue to rise.
Q2: Will the new rules encourage landlords to pass costs on to tenants?
There is almost no doubt about that. Rental property investors need to strike a balance: they must either find savings elsewhere to offset these costs or pass them on to tenants.
Q3: Will these rules make property investment less attractive?
I do not believe these new rules will fundamentally reduce the appeal of investment properties. Auckland’s average house price now exceeds NZ$1,000,000, with annual house price growth ranging from 5% to 7%. Conservatively speaking, a property gains between NZ$50,000 and NZ$70,000 in value each year. The new tax policy we have just discussed actually adds only a few thousand New Zealand dollars in annual expenses—negligible compared with tens of thousands of dollars in capital gains.
Q4: What advice would you give rental property investors?
I believe most rental property investors already have strategies in place. First, I suggest they consider replacing their existing homes with new builds, because new builds are exempt from the new rules and remain eligible for interest deductions. There are many new townhouse developments on the market. Their smaller size and new condition make them more attractive to tenants.
Second, change the investment mix. Commercial properties remain eligible for interest deductions, as do new builds. Investors can minimise borrowing costs through combinations such as new builds and existing homes, new builds and commercial properties, or existing homes and commercial properties.