
An expert says the property market downturn will not last! Are first-home buyers ready to buy at the bottom?
Although others remain cautious about the property market outlook, he believes the market moves in cycles and the current downturn cannot continue indefinitely.
Well-known independent New Zealand economist Tony Alexander recently discussed the monthly real estate agent survey he conducts with the Real Estate Institute of New Zealand (REINZ). Asked what was currently preventing buyers from entering the market, agents gave three leading answers: 1: 82% said buyers considered interest rates too high; 2: 78% cited an inability to obtain sufficient lending; and 3: 69% attributed it to buyers' fear of prices falling after purchase (FOOP). Although others remain cautious about the property market outlook, he believes the market moves in cycles and the current downturn cannot continue indefinitely.
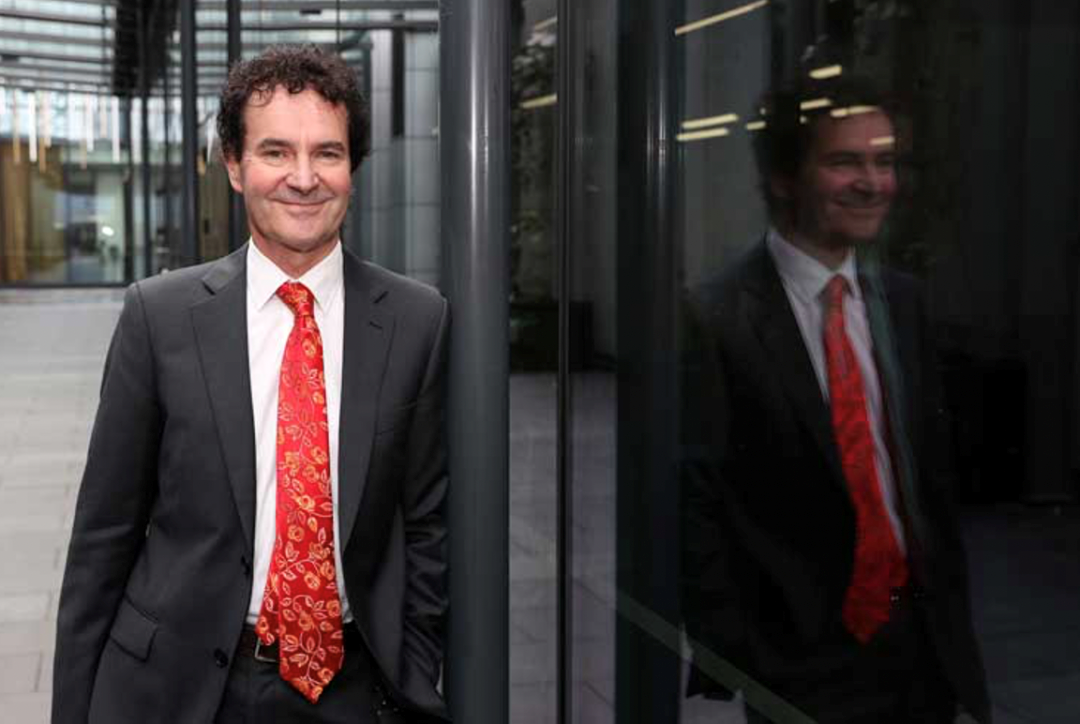
Independent economist Tony Alexander
Oil, coal and food prices have begun to fall, transport costs are easing, and local rent increases are slowing... These positive factors will help New Zealand inflation ease rapidly over the coming quarters. Meanwhile, the market expects the Reserve Bank of New Zealand to begin cutting interest rates at the end of 2023. Asked when first-home buyers should return to the market, Alexander says the three concerns previously raised by real estate agents will largely have eased by the end of this year. If, as current polls suggest, the National Party wins the next general election, favourable policy developments will encourage investors back into the market. As a first-home buyer, would you not want to get ahead by taking advantage of the current buyer's market to buy at the bottom, before activity picks up again and migrants return?
What should borrowers do when the bank says 'no'?
Getting started is always difficult. For first-home buyers applying for a mortgage for the first time, a bank rejection can mean their home ownership dreams are shattered. Worse still, if buyers have already signed a sale and purchase agreement and then discover the bank has declined their loan, they could also lose their deposit.
{ad}
At present, banks mainly reject loan applications because of one or more of the following factors:
- Insufficient income
- An excessively high loan-to-value ratio (LVR)
- Account spending behaviour
- Credit score
- Age
- Place of residence
Aseem Agarwal, head of lending at Global Financial Services, says banks may have some room to manoeuvre when one or more of these factors leads to a rejection. Buyers or investors can then consider finding an experienced mortgage adviser to negotiate with the bank on their behalf as a final effort.
The Jiayuan Finance mortgage advisory team, which has many years of experience in the New Zealand market, believes first-home buyers should obtain plenty of professional advice before applying for a loan. They sometimes begin discussions and assessments several months before a client applies, developing an application plan with the best chance of approval. First-home buyers generally have smaller deposits, so the advisers examine borrowers' individual finances carefully and draw on KiwiSaver or other government support to devise the most suitable application approach for each borrower.
Aseem Agarwal says a poor credit score is one of the main reasons banks say 'no'. Three credit agencies, Equifax, Centrix and Illion, hold credit records for most New Zealand adults. These include identity information, former names and all credit applications made over the past five years. Even without any credit applications, credit information can include overdue electricity, water, internet and mobile phone bills. Credit scores also incorporate personal and financial information relating to defaults, court judgments and bankruptcy. He says most defaults arise because applicants have not paid bills on time. If a borrower has been declined mortgage pre-approval and is still looking for a home, there is time to correct this 'mistake' over the next 3–6 months. Agarwal says borrowers need to demonstrate to the bank that they can manage their finances responsibly. Once an applicant and their mortgage adviser have found a way to address the problem, they will develop a detailed plan for the next 6 months, reviewing progress every 2–3 months to ensure the client is 'moving forward' in the right direction.
Jiayuan Finance's mortgage advisers say good spending habits are very important. They find that for many applicants, the pressure on their application comes from a need to tidy up their accounts rather than their financial position itself. Banks examine applicants' credit records over the past two years, and overdue bills can significantly affect an application. Some issues are relatively straightforward to resolve. For example, a borrower may have too many credit cards or other credit facilities, or an Afterpay bill split into four payments. Lenders count these as debt, so closing the accounts or reducing their limits can address the issue.
Agarwal advises against taking on additional debt, such as a car loan or credit card, before applying for a mortgage. If a borrower has just changed jobs and is on probation, the bank is likely to decline lending because the job is new. In this situation, the borrower needs to remain in the role at their current company. Once the probationary period ends, they can obtain a letter from their employer confirming that they are now a permanent employee. Demonstrating an ongoing ability to repay is the key to securing a bank's willingness to lend.
The Credit Contracts and Consumer Finance Act (CCCFA) is another major reason banks may decline home buyers. The Act aims to curb irresponsible lending. After CCCFA regulations were updated on 1 December last year, many previously eligible borrowers were unexpectedly declined. Anecdotally, this was because some banks assessed buyers' affordability against stricter standards. Mortgage adviser Jonathan Battersby says decisions to approve or decline lending sometimes depend on the individual bank assessor. Some banks remain as exacting as they were before the CCCFA rules were relaxed on 1 July this year, while others do not.
When mortgage advisers cannot secure a bank mortgage for a client, they often turn to non-bank lenders such as Resimac, Pepper Money, Avanti Finance, Liberty Financial and Bluestone. Agarwal says these typically charge 1%–2% more, but the opportunity cost may make this worthwhile for the client.
Finally, the Jiayuan Finance mortgage advisory team emphasises that it provides ongoing service throughout the loan application process, helping clients achieve financial freedom sooner. To do this, its advisers seek as much information as possible about applicants' actual current finances, offering personalised service and developing the most suitable financial plan for each client. Its experienced mortgage advisers make the most of clients' income and savings to minimise interest payments and help them repay their home loans early.