
Revealed: where in New Zealand is best for first-home buyers with a budget under one million dollars?
YIJU has recently received many questions from first-home buyers wanting to know where the best investment opportunities are for those with budgets below NZ$1,000,000. Coincidentally, data recently collected and analysed jointly by OneRoof and its partner Valocity reveals which parts of New Zealand offer the best opportunities for buyers with budgets below NZ$1,000,000 to enter the property market.
YIJU has recently received many questions from first-home buyers wanting to know where the best investment opportunities are for those with budgets below NZ$1,000,000. Coincidentally, data recently collected and analysed jointly by OneRoof and its partner Valocity reveals which parts of New Zealand offer the best opportunities for buyers with budgets below NZ$1,000,000 to enter the property market.
{ad}
Which New Zealand city is most welcoming to first-home buyers
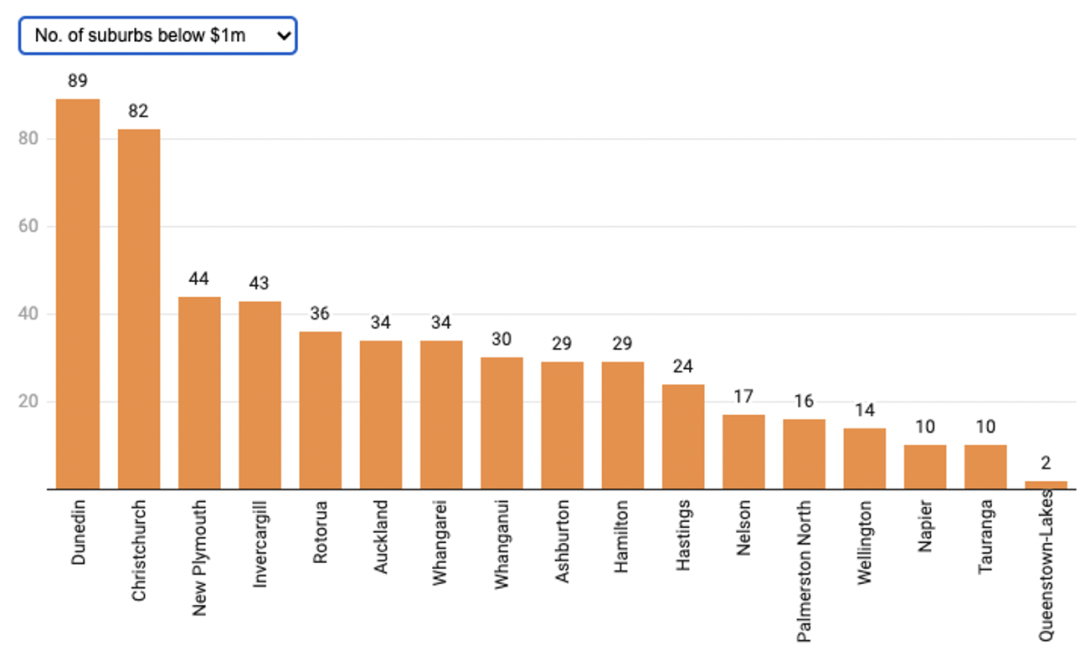
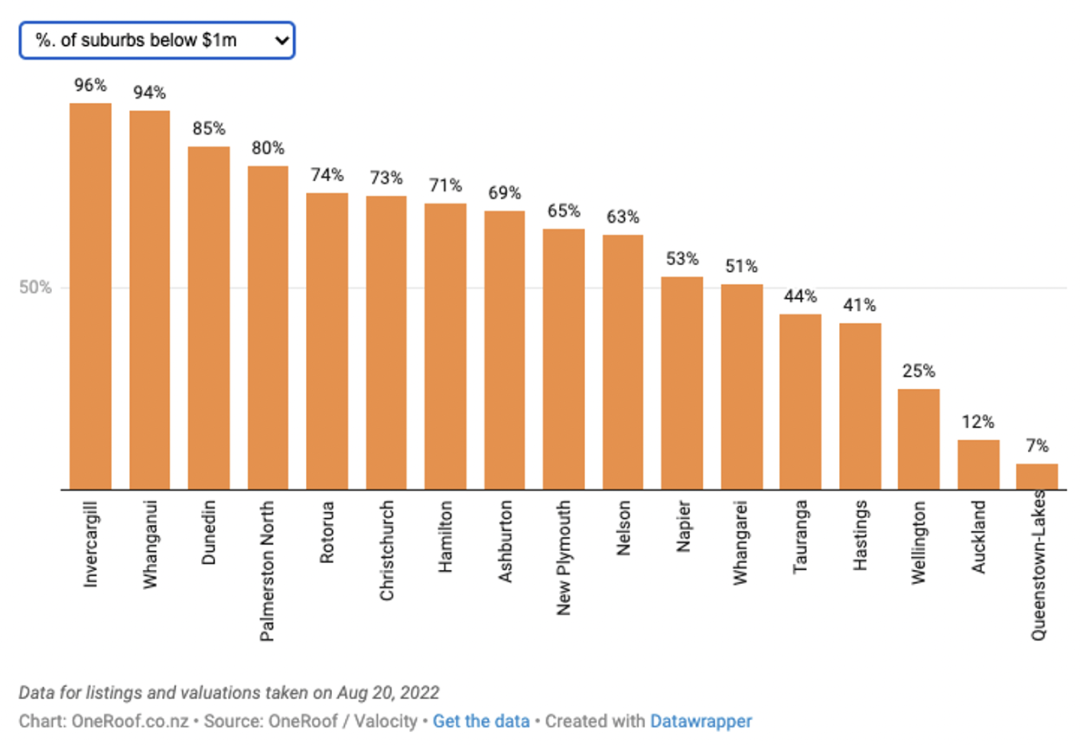
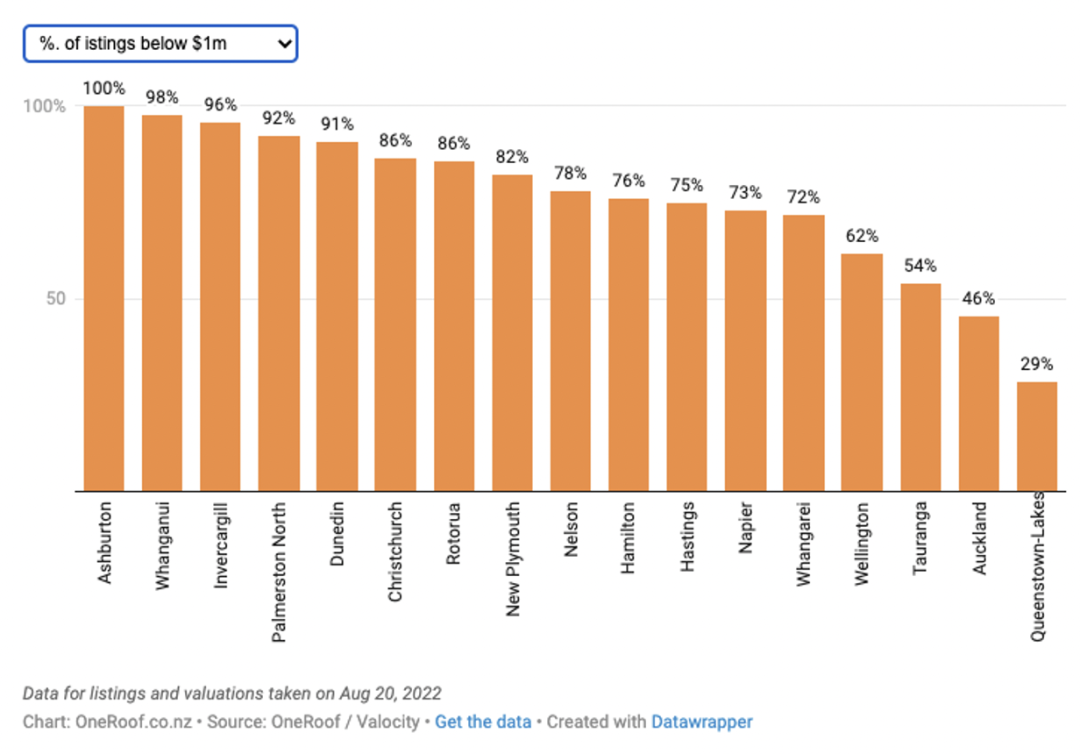
Number and percentage of suburbs in different New Zealand cities with house prices below 1,000,000 New Zealand dollars
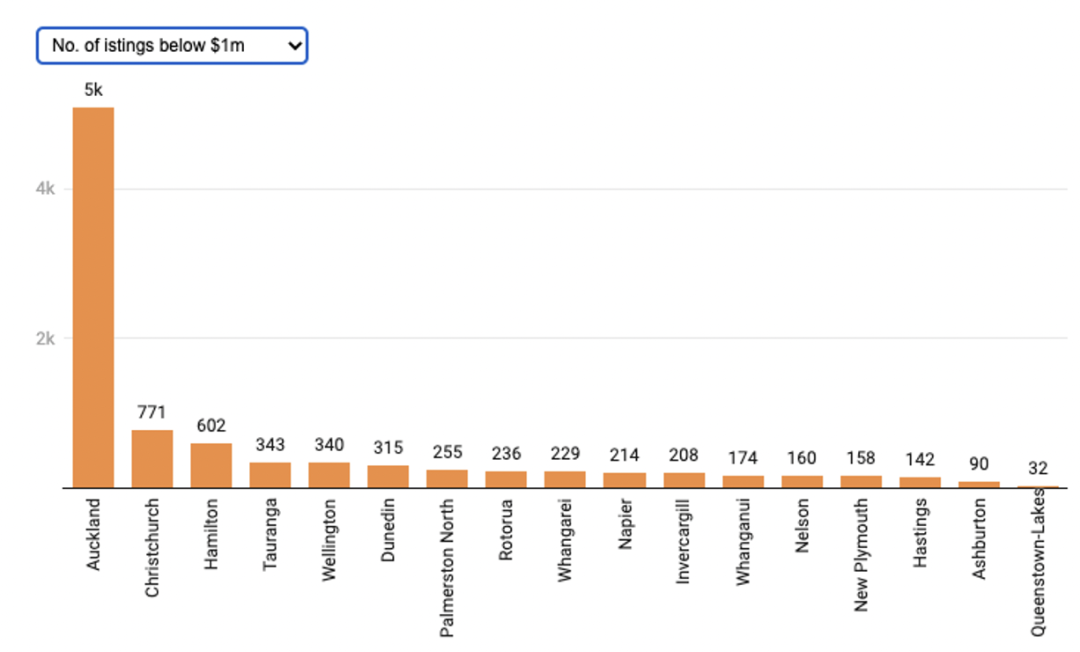
 Number of properties listed for sale in different New Zealand cities priced below 1,000,000 New Zealand dollars and
their percentage share
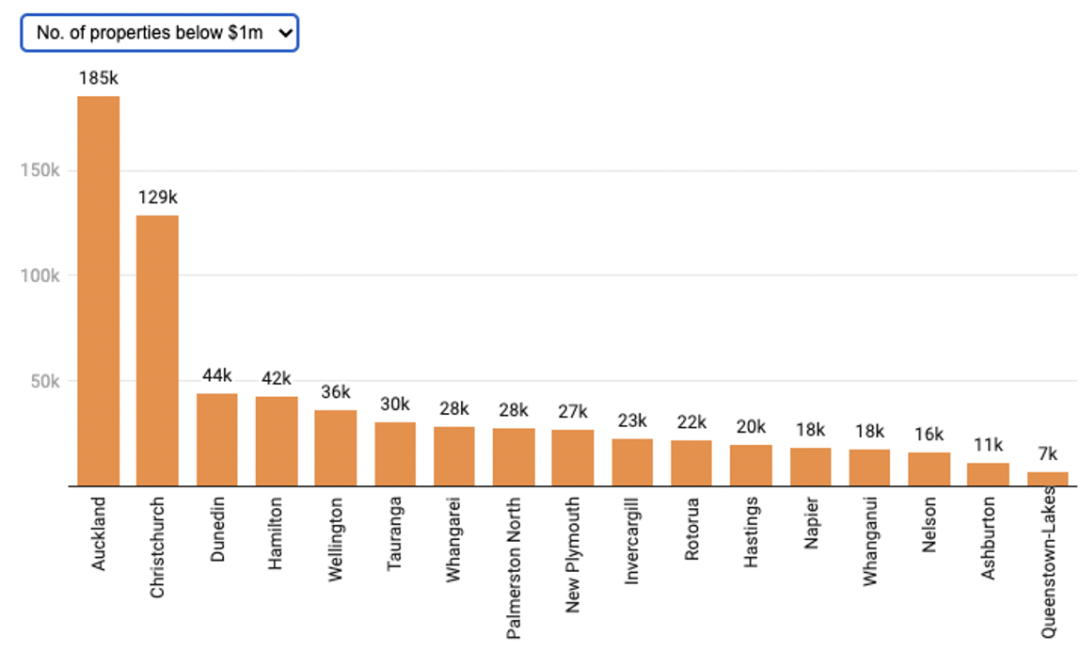
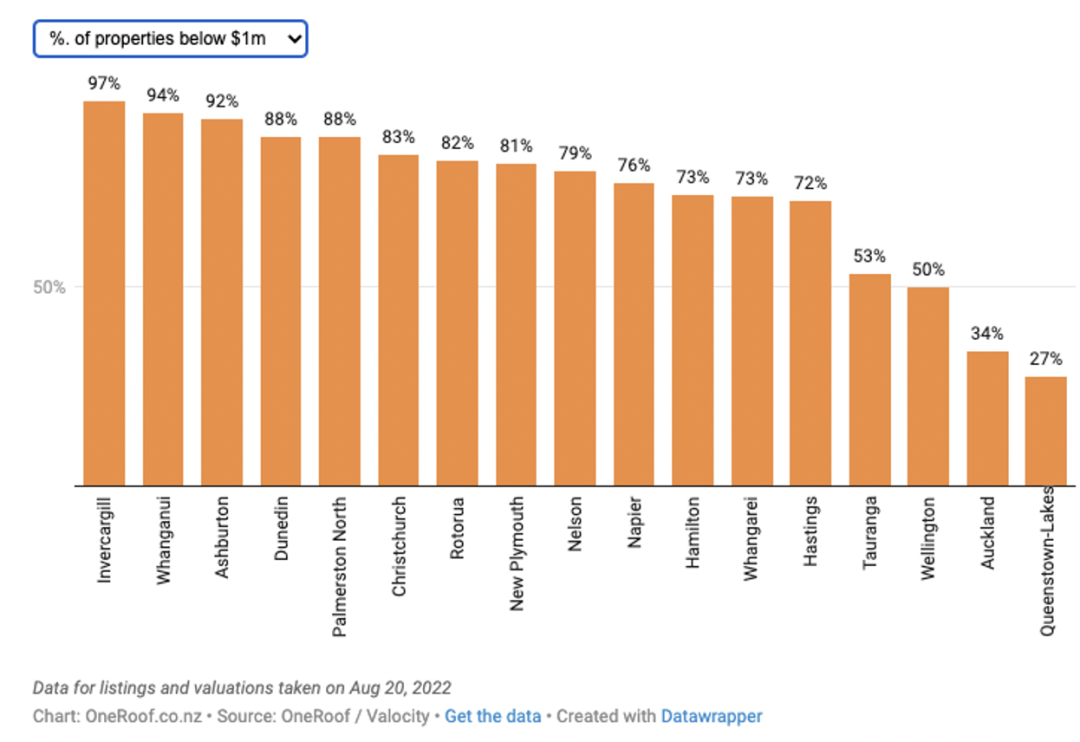
2022: number and percentage of properties bought by first-home buyers in different cities in the first half of the year for less than 1,000,000 New Zealand dollars
As the chart above shows, since the first half of 2022, Dunedin has had the most suburbs in New Zealand with house prices below one million dollars (89). Auckland has had the most listings below NZ$1,000,000 (5k) and the most property sales below NZ$1,000,000 (185k). Meanwhile, among Invercargill's properties valued below NZ$1,000,000, first-home purchases below NZ$1,000,000 accounted for the highest proportion of all properties sold (97%). Ashburton had the highest percentage of listings below NZ$1,000,000 (100%).
Queenstown Lakes ranked last in every affordability category surveyed. It also had the largest gap between the median price paid by first-home buyers and the overall median sale price, indicating that first-home buyers in Queenstown Lakes secured a much larger 'house price discount' than elsewhere.
Which Auckland suburbs should first-home buyers focus on?
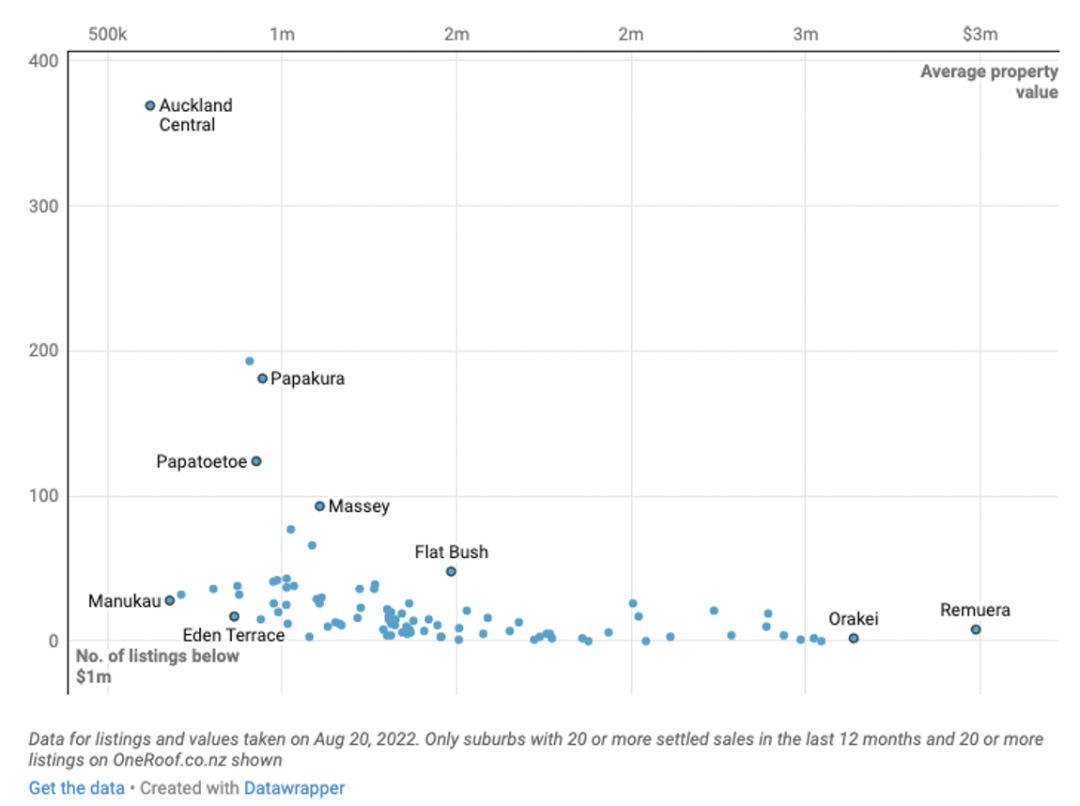
The research behind the chart above used the number of properties priced below NZ$1,000,000 listed on property website OneRoof on 20 August 2022, together with average house price data, to reveal which Auckland suburbs are more accessible to first-home buyers.
First-home buyers should note that Auckland CBD, where apartments dominate listings, is the clear winner for the number of properties around NZ$1,000,000 and affordability. Manurewa, Papatoetoe and Papakura, all in South Auckland, are also highly affordable. By contrast, Remuera and Orakei are the least accessible suburbs for buyers with budgets below NZ$1,000,000.
What are the key factors driving first-home buyers' purchase decisions?
Ray White Hamilton City principal Mark Keesom says family is an important motivation for first-home buyers in Hamilton and Waikato. Their budgets also need to be sufficient. He believes today's first-home buyers are better educated than those buying 10 years ago. However, even when buyers fully understand their needs, mortgage approval remains the key to realising their home ownership dreams.
As listings increase and house prices fall, enquiries from his clients are surging. He says many Auckland investors are also moving quickly into the market. Keesom says first-home buyers will currently be the area's largest buyer group, looking at properties priced from NZ$500,000 to NZ$900,000. They are not all young: he sometimes sees buyers over 40 still trying to enter the property market for the first time. Nevertheless, buyers in their 20s and 30s clearly remain the main group.
He believes new homes in Glenview, Melville and Dinsdale offer first-home buyers the best value for money. These areas are close to the hospital, and the completion of new residential developments is set to bring explosive growth to South Hamilton's property market.
Turning to Whangarei, Barfoot & Thompson branch manager Steve Sharp says the first-home buyer market has become active again since CCCFA rules were relaxed. Falling house prices have made first homes more affordable. First-home buyers in the city currently have budgets of around NZ$500,000–800,000, with plenty of choice in that range. Popular areas include Tikipunga, Morningside, Otaika, Horahora and Hikurangi.
Further north in Kaitaia, LJ Hooker franchise owner Gerard Ponsonby reports that the first-home buyer market is relatively quiet, mainly because there are too few listings. Ponsonby advises buyers to be patient. He says he has never seen the market this quiet but expects it to recover in spring. Ray White Kaitaia general manager Gary Steed also says first-home buyers remain active and have never left the market.
How can first-home buyers overcome the affordability challenges of high house prices?
With Auckland house prices so high, does buying a home remain a distant dream for single first-home buyers, even in a falling market?
Hannah McQueen, founder of financial advisory firm enableMe, says single people need not necessarily give up their dream of buying a home, as different approaches may still allow them to acquire a property. For those hoping to become homeowners sooner, she says buying an investment property before their first owner-occupied home is a good option. This gives them more flexibility over their first property's location: it does not have to be where they live and work, and it can cost less. First-home buyers also make trade-offs when buying, such as choosing between a city centre or suburban location, the number of bedrooms and the size of the backyard. Yet many overlook other options, such as buying jointly with family members. She advises first-home buyers against overinvesting in their first property. An owner-occupied home does not generate income and usually costs more than renting, while excessive debt can create a risk of being unable to keep up with mortgage repayments in future.