
OCR rises again! Is now the best time to buy a home, or should buyers wait for prices to fall further?
At two o'clock this afternoon, the Reserve Bank of New Zealand announced another 50-basis-point increase in the Official Cash Rate, from 3% to 3.5%. The Monetary Policy Committee agreed that continuing to tighten monetary policy to maintain price stability and support maximum sustainable employment remained the most pressing priority for New Zealand's economy.
At two o'clock this afternoon, the Reserve Bank of New Zealand announced another 50-basis-point increase in the Official Cash Rate, from 3% to 3.5%. The Monetary Policy Committee agreed that continuing to tighten monetary policy to maintain price stability and support maximum sustainable employment remained the most pressing priority for New Zealand's economy.
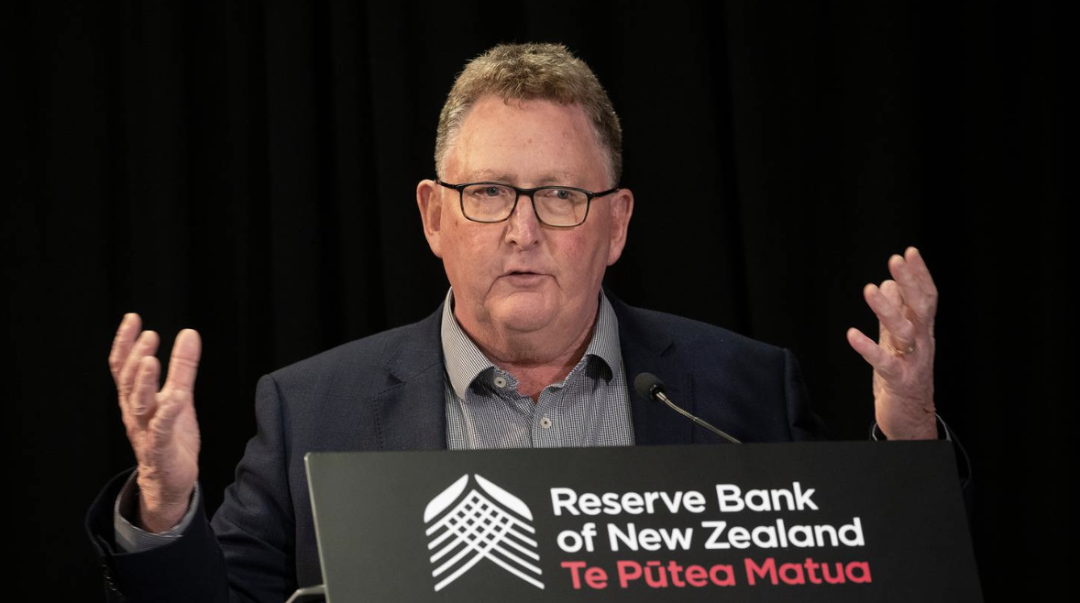
Reserve Bank of New Zealand Governor Adrian Orr today announced that the OCR would rise sharply again by 50 basis points
The latest property report from Realestate.co.nz shows that house prices fell across almost all of New Zealand last month. High inflation and the Reserve Bank's repeated interest rate increases have shaken many owners' confidence in continuing to hold property, leading to a steady increase in new listings. The latest data shows that all regions have entered a buyer's market, particularly Auckland, Wellington and Waikato. After peaking at NZ$992,659 in January this year, the national average property sale price had fallen 7.2% to NZ$921,187 by the end of September.
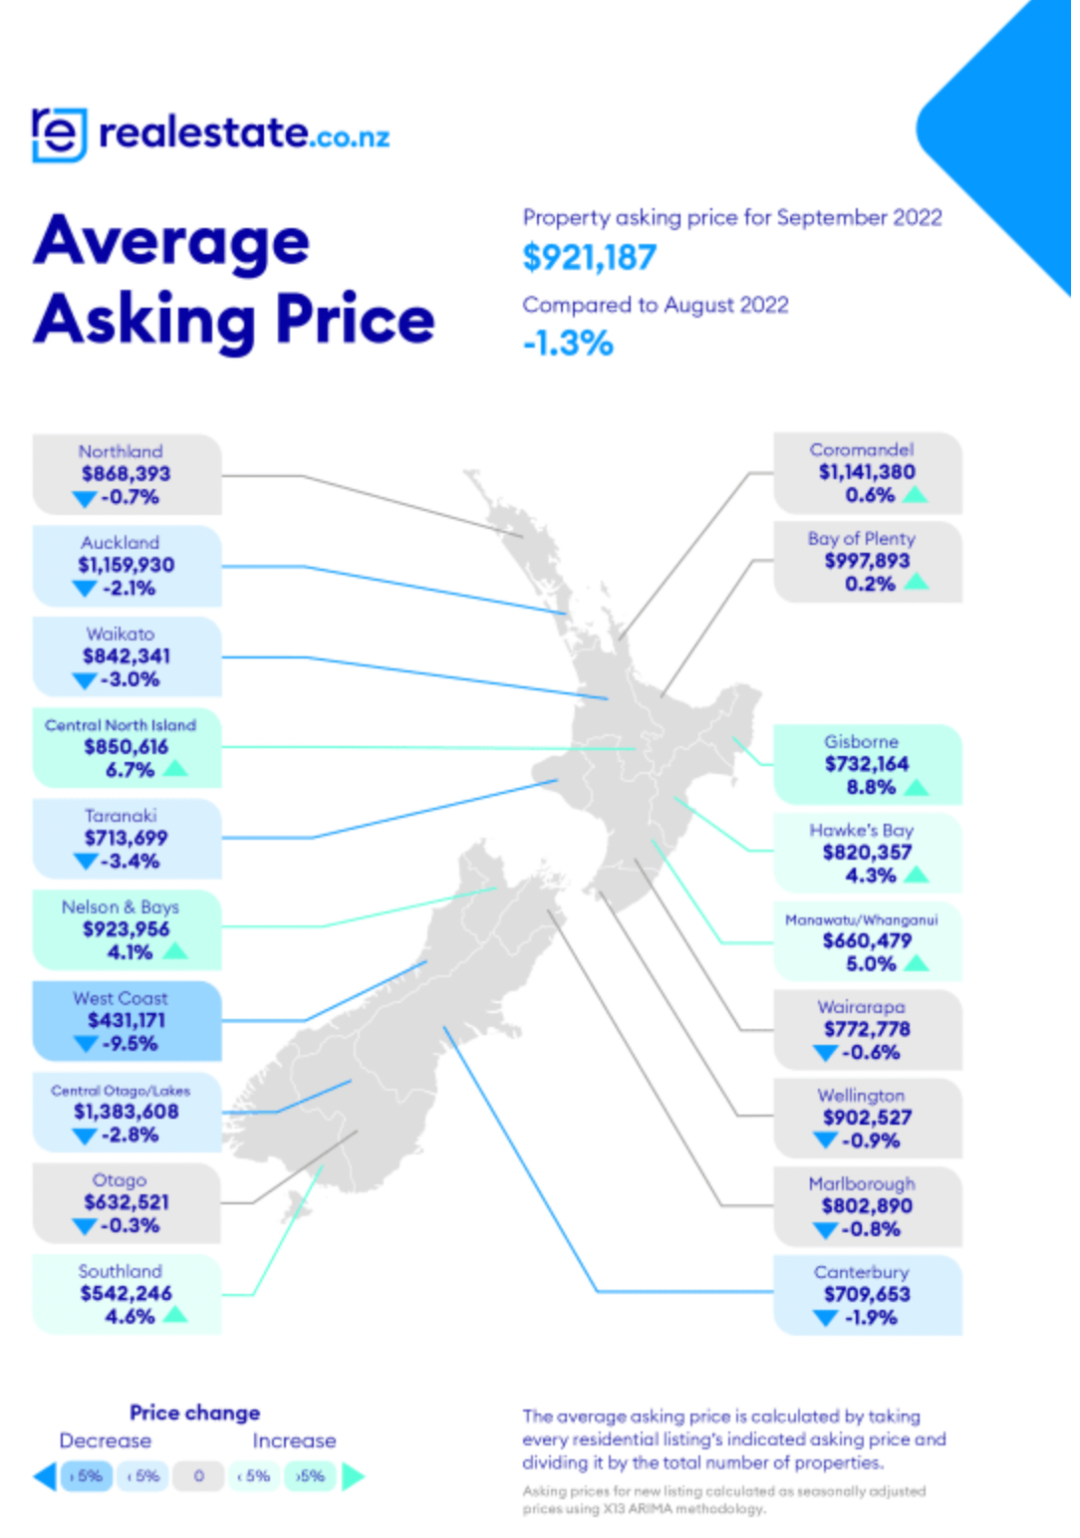
As at month 9: buyer and seller confidence indices across New Zealand's regions
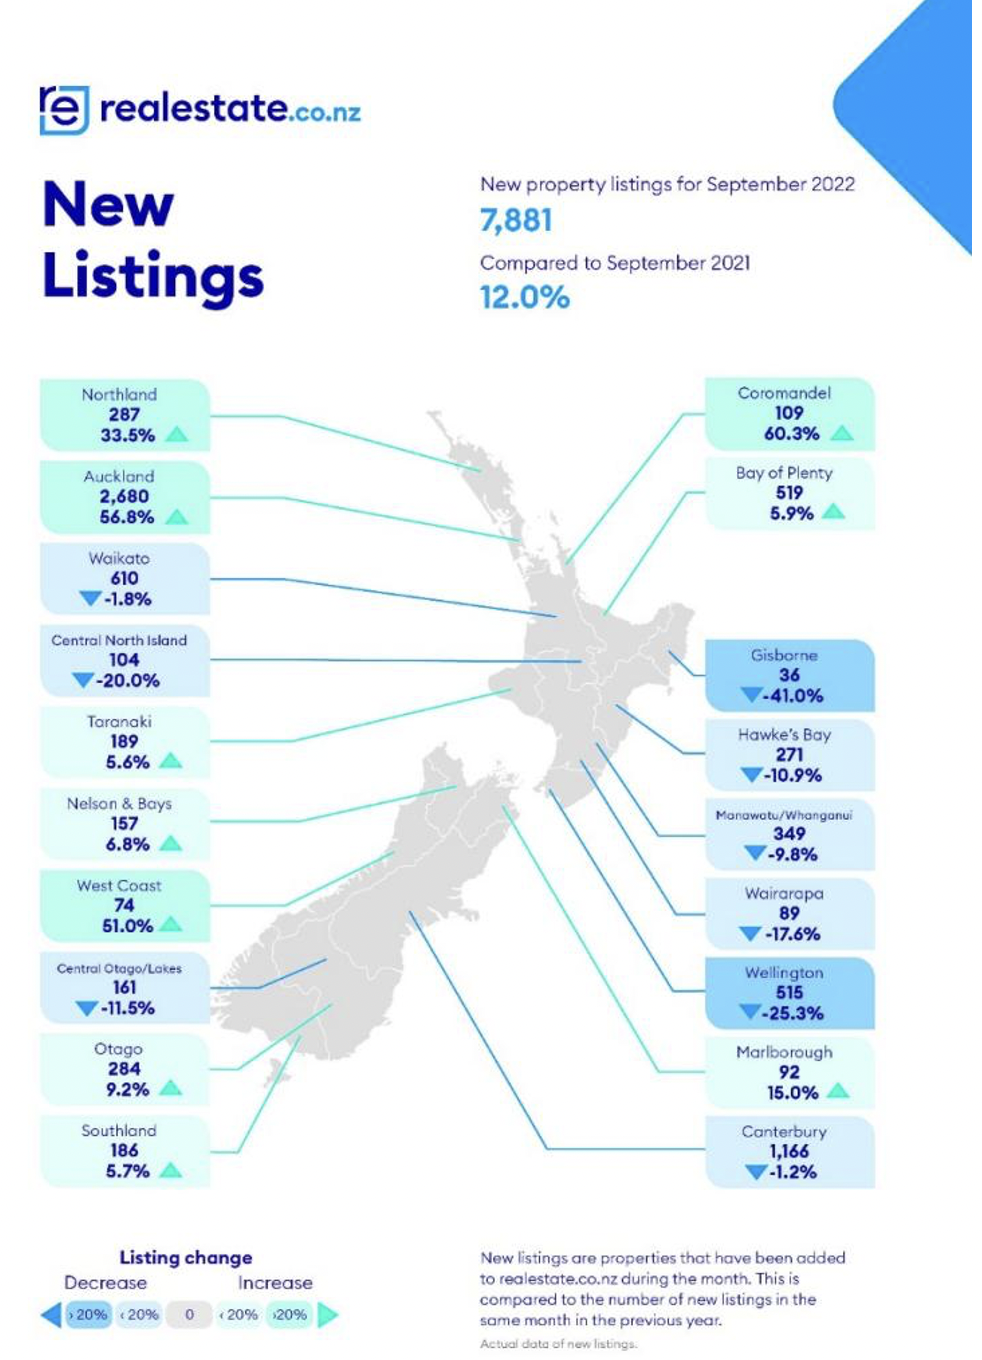
As at month 9: chart showing changes in property listings across New Zealand's regions
Realestate.co.nz spokesperson Vanessa Williams said the housing market was cooling, but not crashing. Although the national average house price had been falling by about NZ$10,000 a month since January, even if that trend continued until the end of this year, it would only take prices back to mid-2021 levels. While property owners might find that forecast unwelcome, investors should view the change rationally and recognise that property investment is generally a long-term way to generate returns.
As house prices fall, potential buyers in Auckland, Wellington and Waikato will find that the market continued to move in their favour over the past month. The report said New Zealand's property market entered a buyer's market in September for the first time in 10 years. More than 10,000 properties were listed for sale in Auckland that month, with available stock up 73.4% year on year, giving buyers more choice.
CoreLogic chief property economist Kelvin Davidson recently said data suggested buyers who had previously stayed on the sidelines were gradually returning to the market. So is now the best time to buy, or should buyers wait to see whether prices fall further? Vanessa Williams said the best time to buy was when buyers could afford to do so. Those trying to time the market and buy at the supposed bottom could end up losing more than they gained. She believed that in a market where key factors such as interest rates and lending rules were changing, buying a suitable property promptly was always a sensible decision. Just as nobody can truly predict when a property boom will end, neither can we accurately judge when prices will bottom out.
Interest rates are another reason why continuing to wait may be pointless for buyers.
This afternoon, the Reserve Bank of New Zealand raised the Official Cash Rate (OCR) for the eighth consecutive time to curb the country's high inflation. Banks including ANZ have also revised their forecasts for the OCR's peak from 4% to 4.75%. How will this latest increase affect borrowers' and their households' ability to borrow and make repayments? Williams advises buyers, particularly first-home buyers, to purchase when their financial circumstances are most suitable, because there are many factors to consider beyond house prices. She put it plainly: “If I had to define the best time to buy a home, it would be 10 years ago. The next best time is today.”
Current market conditions do offer buyers a good opportunity. The property market has slowed, and with less competition, buyers have more time to consider their options, make decisions and negotiate the best price with sellers. Finding a suitable property in an almost frenzied market presents many challenges. Buyers may have to make quick, potentially unwise decisions under competitive pressure, without enough time to investigate a property thoroughly. She also said those who bought at the market's peak need not worry too much. In her view, owners cannot lose money if they hold their properties long term, and over the past ten years she had not encountered a buyer who regretted purchasing because they had lost money. Finally, she concluded that most buyers simply seeking a home to live in should act when they can afford to, without letting minor market changes leave them uncertain about whether to buy.