
How old were you when you bought your first home? The New Zealand couple in today's story are just 19 and 21
News that a young Christchurch couple, aged just 19 and 21, had bought their first home recently became an instant focus of mainstream media attention. Many people were surprised that they had secured a home so quickly, at an age when most people are only just entering the workforce. Some felt there was no need to take on the pressure of a mortgage so young, while others argued that, with New Zealand house prices rising over the long term, the earlier people enter the property market, the better. In today's YIJU article, we look at how Emily Walker, 19, and Bradyn Taylor, 21, achieved their dream of buying their first home without help from family. Their experience might even offer some inspiration to the many people currently
News that a young Christchurch couple, aged just 19 and 21, had bought their first home recently became an instant focus of mainstream media attention. Many people were surprised that they had secured a home so quickly, at an age when most people are only just entering the workforce. Some felt there was no need to take on the pressure of a mortgage so young, while others argued that, with New Zealand house prices rising over the long term, the earlier people enter the property market, the better. In today's YIJU article, we look at how Emily Walker, 19, and Bradyn Taylor, 21, achieved their dream of buying their first home without help from family. Their experience might even offer some useful inspiration to the many aspiring first-home buyers working towards the same goal.
{ad}
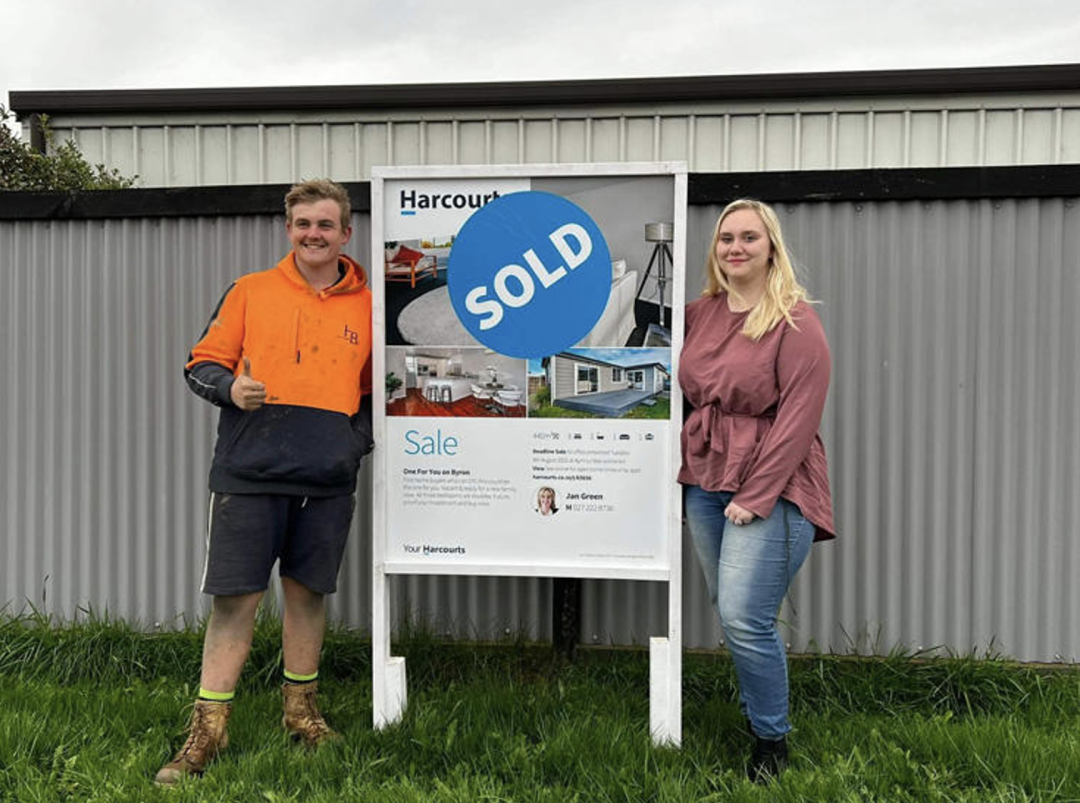
19-year-old Emily Walker and 21-year-old Bradyn Taylor
The home-buying process
The couple only began seriously saving for their first-home deposit at the start of this year. They originally expected that they would not be able to save the required 10% deposit until 2023. Walker, a receptionist at an IT company, and Taylor, a landscape gardener, had been following property prices across Christchurch's residential suburbs. Initially, they thought Rolleston was beyond their budget. But just three weeks ago, a three-bedroom home there caught Walker's attention as she browsed a property listing website. After a quick search on OneRoof gave them an approximate valuation, they promptly booked a viewing.
Two days later, they submitted an offer with just two hours to go before the deadline. Fortunately, their conditional offer of NZ$550,000 was successful. (Note: NZ$550,000 was also the maximum purchase price for them to qualify for a First Home Grant in Christchurch.)
The house on Byron St, built in the 80s, had been a rental, so some repairs would inevitably be needed after settlement. Walker was not concerned. Although it looked a little dated and was certainly not the prettiest house in Rolleston, she hoped some work would make it look much better. She said this could be a very good opportunity to own the property: Rolleston was continuing to develop, and she believed house prices in the area would keep climbing.
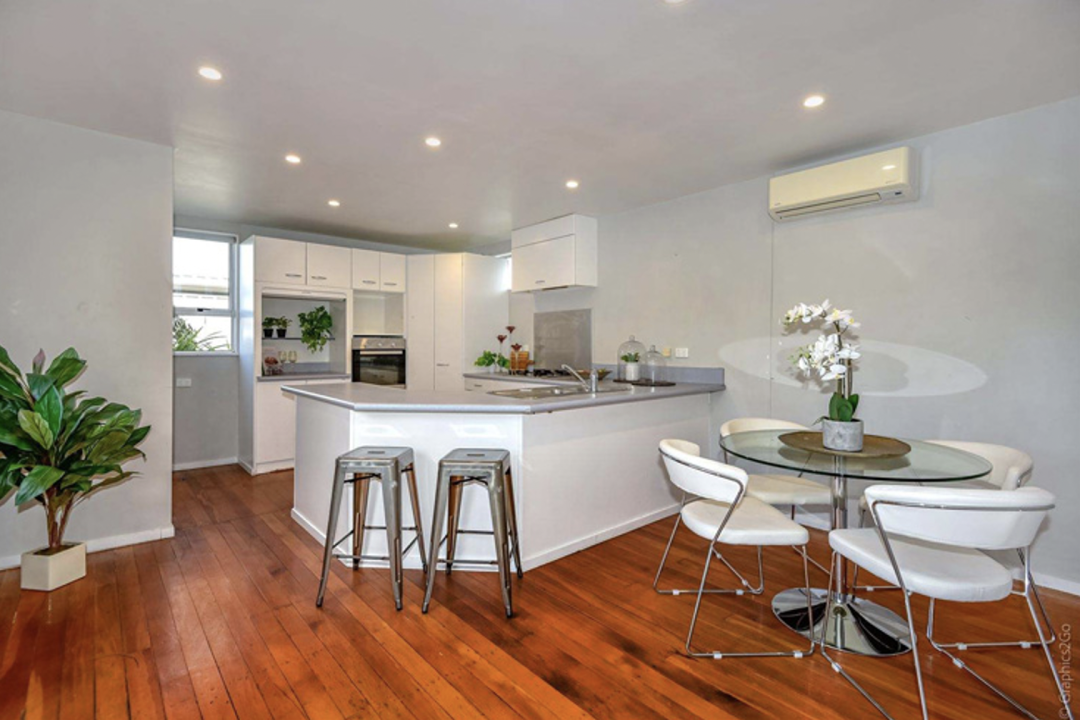
Although previously rented out, the property is in good condition
After the sellers accepted their conditional offer, the couple worked closely with a mortgage broker to secure eligibility for Kāinga Ora's First Home Grant and approval for a bank mortgage. This meant they could soon own their first home with a deposit of just 5%. (For information on qualifying for government first-home assistance, see YIJU's 20 September article ????)
Preparing to buy
Walker said they had put considerable effort into building their deposit. They had always been savers, and by keeping everyday spending to a minimum, they had saved about NZ$32,000 on living expenses since the start of this year. They also made use of NZ$20,000 in their KiwiSaver accounts and, with the government First Home Grant, secured enough for their deposit. Their main expenses had been rent, power, water, internet and groceries. Apart from a few credit cards that had already been paid off, they had no significant debts. Under the household budget they had set themselves, they could save about NZ$600 a week.
They also found a flatmate to share the rent on their two-bedroom city-centre apartment, saving them a considerable amount. Through their persistent efforts, and with help from the bank and Kāinga Ora, they achieved their dream of buying their first home without financial support from family or friends. Many of their peers were amazed that they had accomplished a seemingly impossible task at their age.
Advice from the young couple
For Walker, leaving their conveniently located Christchurch CBD apartment means a longer daily commute to the office. But she believes all the effort is worthwhile because they are now paying off their own home rather than paying rent to a landlord. She said many people her age should also start seriously considering buying their first home, follow properties coming onto the market and act promptly when the right one appears. The government has now raised the price caps for First Home Grant eligibility, which is very helpful for first-home buyers. Although many people believe house prices have further to fall, if prices are already at their lowest point, more first-home buyers could return to the market next year, bringing greater competition.
Advice from mortgage advisers
The mortgage advice team at New Zealand-based Jiayuan Finance told YIJU New Zealand that their clients regularly include young first-home buyers who successfully enter the property market with help from professional mortgage advisers. This shows that, with effort, their dream of owning a first home can be achieved. The example above suggests that if young couples start saving as soon as they get their first jobs, contribute more through KiwiSaver, keep short-term debt low and avoid excessive overdrafts, these essential steps will help them apply to a bank for their first mortgage.
As Walker noted, Kāinga Ora has removed the First Home Loan price caps, helping more first-home buyers achieve their dream with a deposit of just 5%. Banks' lending requirements under the CCCFA remain tight, and applications with an LVR above 80% can easily be declined, potentially making Kāinga Ora the only option for many people. Jiayuan Finance's mortgage advice team encourages young first-home buyers not to lose heart: current market conditions offer a very good opportunity to buy. They recommend consulting a professional mortgage adviser before viewing homes. A professional assessment can establish whether buyers qualify for a loan or what preparations they need to make to achieve their ultimate goal of home ownership.