
As the US banking crisis spreads, could New Zealand property face a dramatic turnaround? Earlier forecasts could all be overturned…
First Republic Bank, known for serving wealthy clients, is also teetering on the brink of a bank run
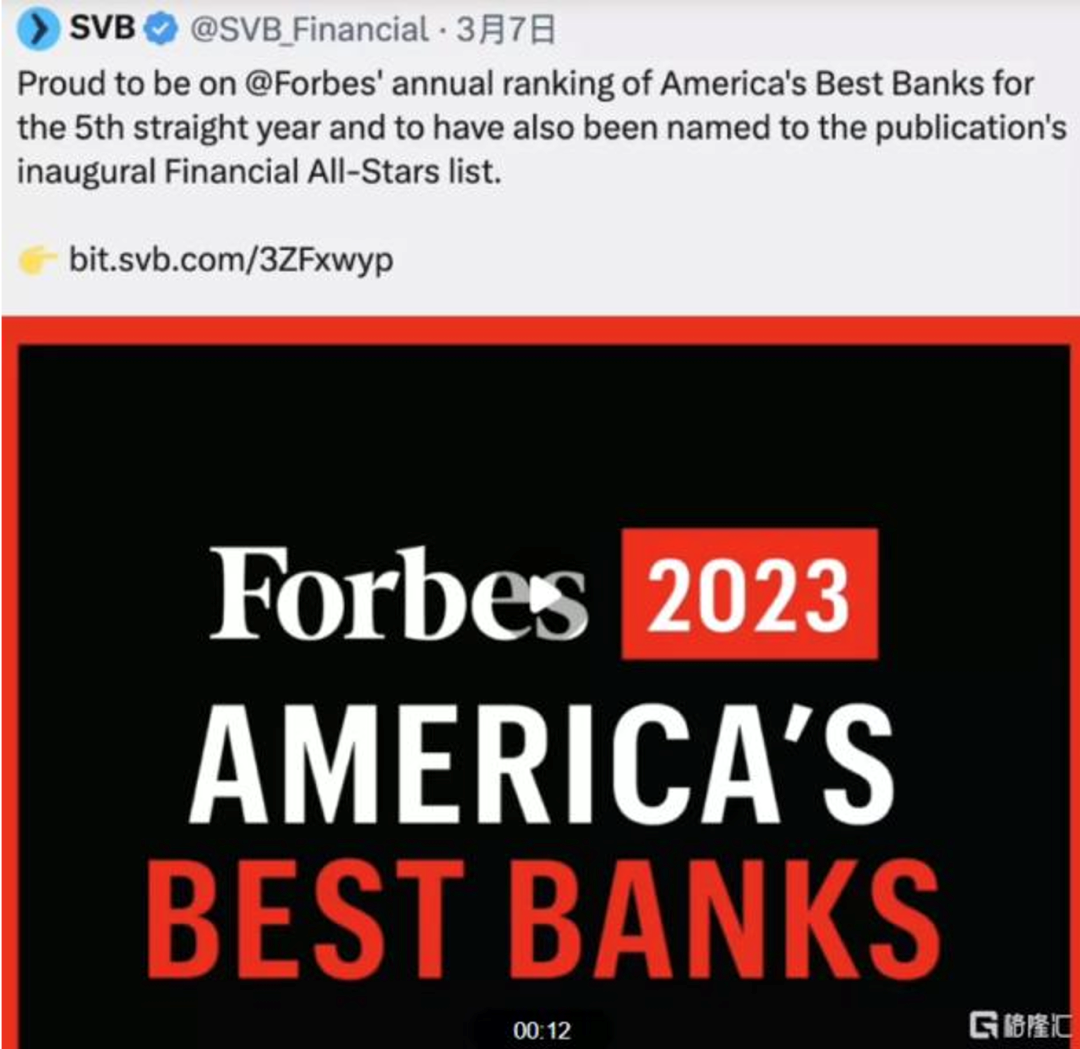
The recent banking crisis in the United States is now widely known. Silicon Valley Bank, founded in 1993 and with a 40-year history, suddenly collapsed following a bank run in just 3 days. Only last year, it had been named the best bank in the United States. Signature Bank also collapsed, while First Republic Bank, known for serving wealthy clients, is teetering on the brink of a bank run.
These banks collapsed suddenly or rapidly approached collapse because the United States' sustained, rapid interest rate rises to combat inflation affected the market value of their core assets: government bonds and mortgage-backed securities. Rapid rate rises drove down bond prices, forcing banks that needed cash or liquidity to sell bonds at a loss. Those losses accumulated to the point where the banks' capital was insufficient to cover them. When the news emerged, depositors panicked and rushed to withdraw their money, triggering bank runs.
Although the US government responded swiftly, introducing targeted tools to protect depositors and prevent the crisis from spreading, these events show that rapid US interest rate rises have reached the end of the road.
The Federal Reserve's new goal: preventing a financial crisis
Before this crisis, the Federal Reserve favoured rapid interest rate rises, and the market expected a 0.5% increase in March. This was because its monetary policy decisions focused on inflation and the economy. With US inflation remaining stubbornly high and no sign of an economic recession, rate rises were expected to continue and potentially accelerate. This was what Fed chair Powell had previously meant by a higher peak interest rate maintained for longer.
The Federal Reserve now needs to add another consideration to its original 2, bringing the total to 3: the financial sector's capacity to withstand higher rates. This crisis arrived very suddenly, highlighting the powerful side effects of rapid rate rises. They could unwittingly trigger widespread financial turmoil, at which point the economic damage would be beyond the reach of a straightforward bailout.
For these reasons, the Federal Reserve raised rates by only 0.25% today, rather than the 0.5% expected in February. Some market participants believe this may already be the final increase, with further rises potentially coming to a halt. Expectations about when a rate-cutting cycle might begin, and how far rates might fall, continue to shift.
Current interest rate expectations
The current Federal Reserve interest rate is 4.75%. The chart below comes from the well-known CME's FedTools, a Federal Reserve monitoring tool. It shows that, as of 8 March, the market expected rates to be 5.75% in October 2023 and 5.5% in February 2024. By 14 March, just 6 days later, expectations had shifted to 4.25% in October 2023 (a cut of 0.5%), followed by continued cuts to 3.75% in February 2024 (as much as 1.75% below the original forecast).
Changes in New Zealand's market and what lies ahead
The Reserve Bank of New Zealand now faces the same issues as the Federal Reserve: inflation and the economy. Fortunately, there are no signs yet of a financial crisis emerging in New Zealand, but pressures across industries are becoming increasingly apparent.
As an island economy reliant on international specialisation, New Zealand needs substantial imports and exports each year and is closely connected to the global economy. Its monetary policy is therefore heavily influenced by the Federal Reserve. The Fed could be described as the world's central bank: its every move has a profound effect on New Zealand's funding costs through the bond market.
In recent days, New Zealand's government bond market has moved in line with the US Treasury market, with yields falling sharply. This has pushed wholesale interest rates down by 0.5% in just a few days. History over many years shows that, if the United States cuts interest rates, New Zealand will inevitably follow.
{ad}
New Zealand property prices are closely linked to the interest rate cycle. The current cycle of rate rises began in October 2021 (when the OCR rose from 0.25% to 0.5%), while New Zealand property prices peaked between November and December 2021. After more than 1 year of rapid increases, the OCR now stands at 4.75%. Over the same period, the property market has undergone a deep correction, with Auckland's median house price falling by 20%.
Whether or not the Federal Reserve raises rates by only 0.25% in March this year, as the market expects, the threat of a financial crisis makes a slowdown or even a halt in rate rises a certainty. This also means the Reserve Bank of New Zealand's April increase could be smaller, or could be the last in this cycle.
As interest rates peak and a rate-cutting cycle begins, the point at which property prices find their floor will quietly draw closer.
The bottom could arrive sooner
This financial crisis has upended previous market expectations. Rate cuts may arrive earlier than expected, which would also mean house prices could bottom out sooner than anticipated.
Once external conditions, such as interest rates, change direction, markets can react very quickly. Although the future cannot be predicted, it is important to have a plan for how to respond when events unfold: place less emphasis on forecasting and more on responding.
Property investors can focus solely on properties with capital growth potential. Owner-occupiers, however, face very different circumstances and often have fewer choices because of factors such as family needs and location. Once they miss the bottom of the market, finding an ideal home may become very difficult. Owner-occupiers, including those moving home, therefore need to pay particular attention to opportunities around the market's trough.