
No parental funding or partner to share the cost: a 19-year-old New Zealander buys a home on her own! How did she do it?
For young people, buying a home of their own single-handedly in New Zealand now seems an impossible task.
For young people, buying a home of their own single-handedly in New Zealand now seems an impossible task. Data shows that a household earning the median wage needs to save for an average of 229 weeks, putting aside 30% of its income, to afford a standard property, with fortnightly repayments reaching NZ$1549.
Yet in Christchurch, in the South Island, a young woman aged just 19 has bought her first home entirely on her own! How did she do it? Here is her story.
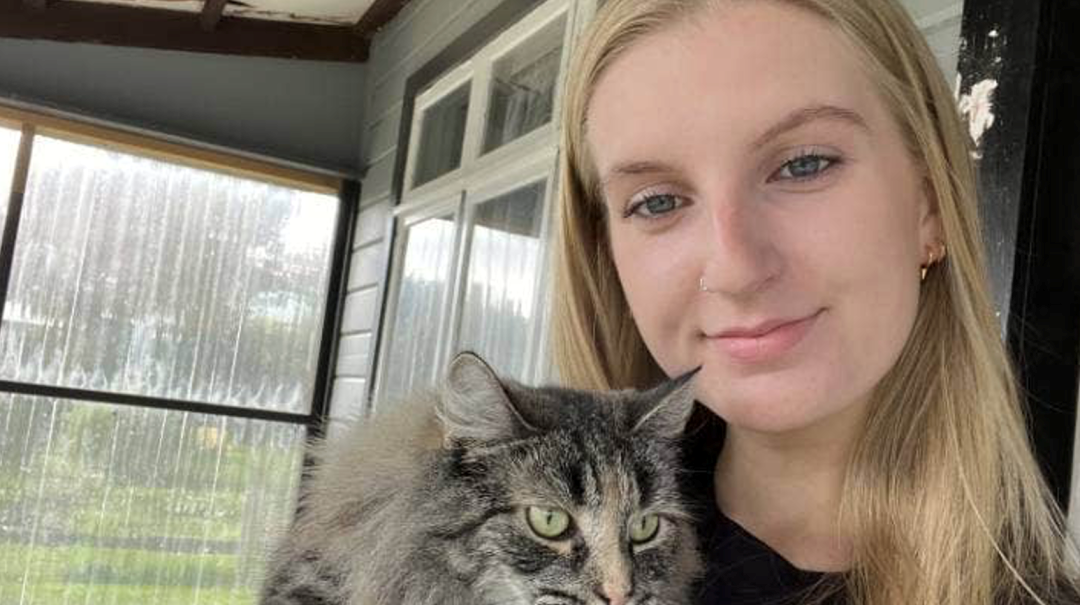
Kiana Sefonte
19 and the challenges of buying a home on her own at that age
Kiana Sefonte, a 19-year-old New Zealander, successfully bought a home on her own, without financial help from her parents or support from a partner. The most frustrating part of the process was the widespread doubt that she could do it alone. Real estate agents and bank representatives alike assumed her parents were buying the house for her, or that she was buying with a partner. She found it deeply discouraging to have to explain repeatedly that neither was the case, and many people were not even willing to deal with her.
During her childhood, her family frequently moved around the country and between rental properties, prompting her to decide early on that she wanted to buy her own home. In November last year, she bought a “pretty perfect” two-bedroom house with a garden in North Canterbury.
“When you are renting, you never know when you might have to move for some reason,” she said. “I have always wanted a home of my own, where nobody can give me notice to leave and I can paint the walls as I please.”
{ad}
What did she get right during the home-buying process?
1
Work full-time and save hard
Kiana Sefonte began working full-time in hospitality and tourism at 16, opened a KiwiSaver account and kept her spending as low as possible without making life too difficult for herself.
At 18, she found a job at St John, where her colleagues were planning to buy homes. This strengthened her own determination to buy.
2
Apply for first-home buyer assistance
Her parents were unable to help her financially, and she had no partner to share the mortgage burden, so Sefonte had to rely on her own savings.
Fortunately, Sefonte qualified for Kāinga Ora's first-home scheme, allowing her to buy with a 5% deposit. With a First Home Grant of NZ$3000, her deposit came to about NZ$12,500, enough to buy a home in the NZ$250,000 price range.
3
Adjust expectations and look further afield
Sefonte quickly realised Christchurch homes were too expensive for her, so she began looking around the wider Canterbury region. “I am a realist, so I knew I would have to buy a cheaper home somewhere more remote and less popular, but I was completely comfortable with that,” she said.
4
Get everything ready before applying for a loan
There were some properties available, but Sefonte found the buying process daunting. She was also deeply frustrated by how many people doubted she could do it alone. She contacted several mortgage brokers for help.
“One mortgage broker simply ignored me, and another was helpful at first but then disappeared completely,” she said. “So I faced considerable resistance before I even had a chance to explain my circumstances, or before anyone looked at my bank accounts and finances.”
That meant doing her own research and approaching banks herself. It took time and several attempts before she found a bank that took her seriously. At times, she felt she should simply give up. “It was certainly stressful, but I am stubborn, and that made me even more determined,” she said. “My parents encouraged me, and I knew I qualified for a loan with a 5% deposit, so I kept going.”
Eventually, she found a house within her budget in a small town. When she went to SBS Bank to apply for a loan, she met a helpful and understanding account manager. They worked through the application together, and her finances met the lending requirements, although she was surprised by how much information she had to disclose.
Once she secured the loan, with a one-year fixed rate of 5%, things went very smoothly. She bought the house for NZ$250,000, and because it was vacant, she could move in straight away.
Having bought her home, she hopes to encourage all prospective buyers
It is an older house that needs some cosmetic work, such as a fresh coat of paint. “But it is in decent condition, liveable, insured and mine,” Sefonte said. “It is on a quarter-acre section. The neighbouring property is on a cross-lease, with a garden at the front, so I look out over their garden, and there is farmland behind. It is lovely here.”
Her mortgage repayments are about NZ$270 a week, compared with NZ$200 a week to rent a cramped one-bedroom flat in Christchurch. She said the difference in cost was not particularly large. “And now my cat and I have more space, so it is worth it.”
The daily commute of more than an hour to work in Christchurch took up too much time, so she changed jobs and now drives a truck for a local company. But she is “one hundred per cent happy” with the home she bought and her move to the small rural town.
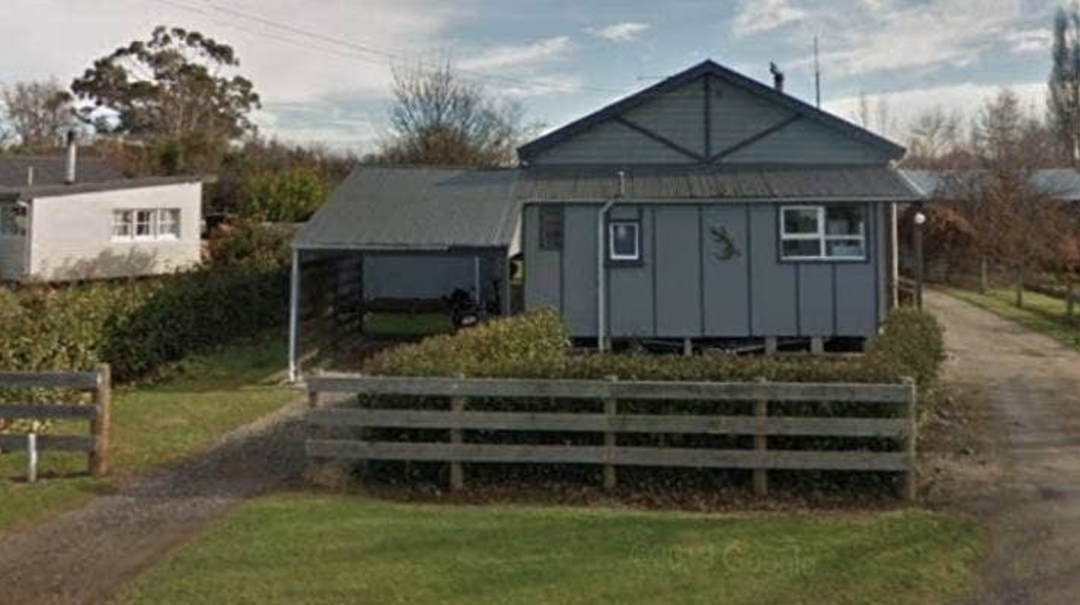
Kiana Sefonte's home purchase
She advises buyers to be realistic: “You have to start small, as I did. Even a unit or something similar is fine. It is a start, so if you can work towards it, go for it. If you are paying hundreds of dollars a week in rent and mortgage repayments would be much the same, buying is worthwhile. Even if you eventually cannot afford it and have to sell, you can get something back, which you cannot do with renting.”
“Most people ask who helped me buy the house, almost as if they do not want to believe I could do it on my own. Although buying a home at my age is unusual, I want to tell my story to inspire other people who want to buy。”
How old were you when you bought your first home?