
Will next year’s DTI rules increase homebuying risks for borrowers and make approval harder? Will you still be able to secure a loan?
News that the Reserve Bank of New Zealand will introduce new debt-to-income (DTI) lending rules next year immediately prompted considerable concern
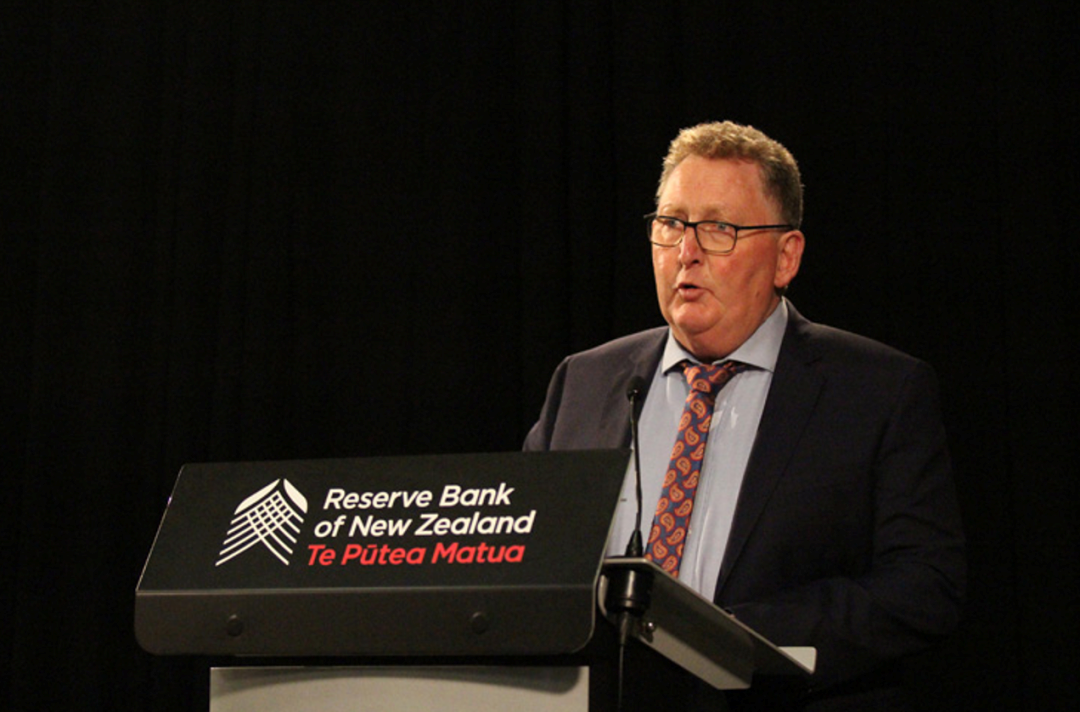
Reserve Bank of New Zealand Governor Adrian Orr announces that the new DTI policy will be introduced next year
News that the Reserve Bank of New Zealand will introduce new debt-to-income (DTI) lending rules next year immediately prompted considerable concern that the rules would disadvantage investors and first-home buyers. Many buyers expressed alarm that even if house prices fall next year, high interest rates will make buying a home more challenging. Although the precise income multiple that next year’s DTI rules will impose on borrowing remains unclear, the Reserve Bank of New Zealand established the basic framework in April and said it could take effect as early as March next year.
DTI How it differs from LVRs
Loan-to-value ratios (LVRs) limit the maximum amount an individual can borrow based on their deposit, while mortgage serviceability tests focus on whether borrowers can afford their monthly repayments. DTI, by contrast, limits borrowing based on the borrower’s income.
DTI is a Reserve Bank tool for controlling property prices, an important part of managing financial stability and a significant measure to curb property investment. Measures to restrain property investment generally include:
- Phasing out interest deductibility for existing investment properties, with an exemption for new builds;
- Banks currently assessing investment properties on a principal-and-interest basis, which is unworkable for many investors;
- Higher LVRs for investment property buyers than for owner-occupiers
- The Reserve Bank raising the cash rate
{ad}
Experts: DTI rules may be applied flexibly
Experts recently said concerns that next year’s lending rules would expose mortgage borrowers to greater homebuying risks and higher interest rates were unfounded. They believe there may be some flexibility when the policy takes effect, with the Reserve Bank allowing commercial banks to lend around 15% of their total mortgage lending outside the DTI rules and granting exemptions to borrowers buying new builds.
However, some financial commentators remain concerned that DTI restrictions could further constrain first-home buyers’ access to the market. These buyers already struggle to secure loans under existing LVR policies and stress tests, shifting that pressure onto their parents by having them share the debt.
Are second-tier lenders really a “magic remedy” for mortgage borrowers?
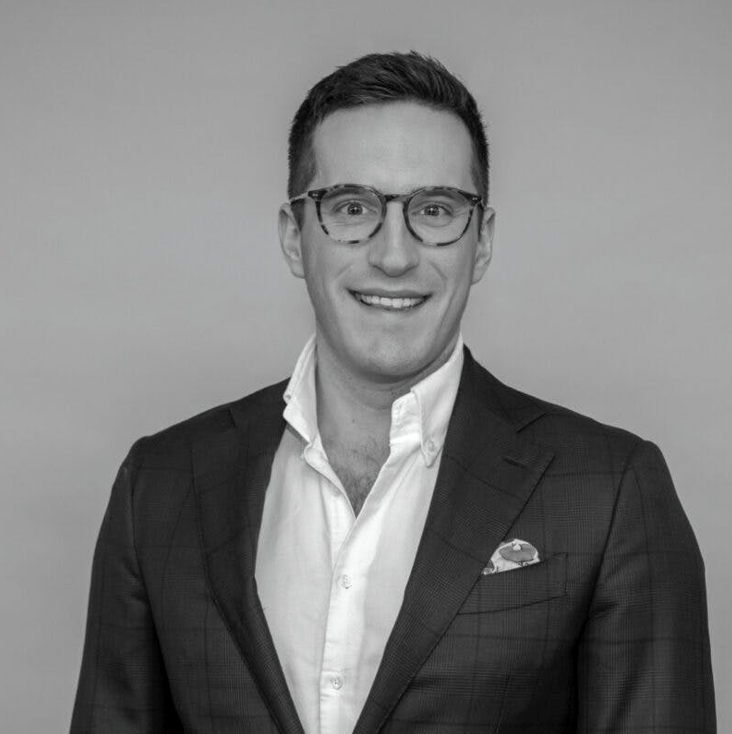
Opes Partners Economist Ed McKnight
Opes Partners economist Ed McKnight said non-bank lenders can offer opportunities to borrowers facing difficulties, providing homebuying funds to people unable to obtain finance from mainstream commercial banks, such as the self-employed. McKnight explained that these second-tier lenders often have discretion over how they assess borrowers’ repayment capacity and are not bound by DTI rules. He added that business customers such as builders and developers could be another group to benefit from second-tier lenders, as they need shorter loan terms, whereas commercial banks prefer customers to take out long-term mortgages of 30 years. Non-bank lenders therefore offer investors greater flexibility over loan terms.
First-home buyers typically take out non-bank loans for 1–2 years, hoping future property appreciation will increase their equity enough to meet mainstream commercial banks’ lending criteria. The greatest risk, however, is that many who bought at the market peak have since seen their property values fall by a cumulative 30%, leaving them trapped with higher non-bank lending rates.
McKnight does not believe the current economic climate will drive large numbers of homebuyers to non-bank lenders. He said DTI policy would not take a blanket approach, and the Reserve Bank might allow 15% of bank lending outside the framework. If the Reserve Bank introduces a DTI ratio of 7 next year, up to 15% of bank borrowers could still have debt-to-income ratios above 7. Currently, fewer than 10% of borrowers would be affected by a DTI ratio of 7, meaning the impact would be very limited even if the rules took effect today. He also noted that non-bank lending currently accounts for only around 1% to 2% of the mortgage market, making a large-scale shift to second-tier lenders unlikely.
More importantly, the higher interest rates charged by non-bank lenders make them an uneconomic choice for homebuyers. If a buyer plans to purchase an investment property with a gross yield of 6%, a non-bank lender might charge interest of 8%–10%, making the arrangement entirely unworkable. Applications to second-tier lenders may also incur additional application and processing fees, further reducing their appeal. A good illustration is that before LVR restrictions and the strengthened Credit Contracts and Consumer Finance Act (CCCFA) were introduced into the lending market in December 2021, many predicted a sharp increase in borrowers turning to non-bank lenders, but this did not eventuate.
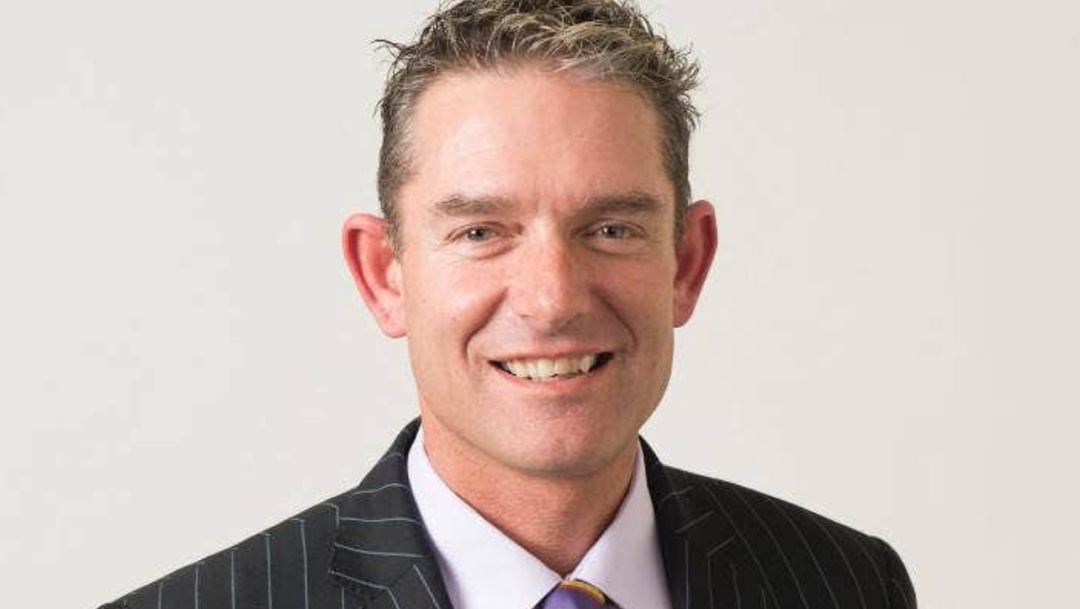
Squirrel chief operating officer David Cunningham
David Cunningham, chief operating officer of mortgage company and lender Squirrel, recently said people often mistakenly believe borrowers can easily obtain funds by applying to non-bank lenders. He said that is not the case: funding is always limited, and non-bank institutions cannot accommodate a large volume of loans. If borrowers turn to non-bank lenders in large numbers, competition will become intense, making alternatives to banks even harder to find. Homebuyers who qualify for non-bank loans often have substantial financial resources. Their irregular income may prevent them from passing banks’ stress tests, but that does not mean they lack the money to meet monthly repayments.