
Rental yields are rising across the board! Will they attract more property investors?
CoreLogic's latest survey shows that the national average property yield was 3.1% in June, up from last year's low of 2.6% and the highest level since February 2021.
CoreLogic's latest survey shows that the national average property yield was 3.1% in June, up from last year's low of 2.6% and the highest level since February 2021.
{ad}
Gross yield measures the rental income a property generates as a proportion of its purchase price, without accounting for expenses such as tax, insurance and maintenance.
Meanwhile, Bayleys has also released its latest survey figures, showing that the national average pre-tax rental yield in March was 3.3%, up from 2.8% in the same period last year. Bayleys' net yield figures represent rental income after expenses, but before tax and interest.
CoreLogic chief property economist Kelvin Davidson
The outlook for rental yields
In recent years, rental yields have remained low as rent increases have lagged well behind soaring house prices, making investment strategies focused on high rental returns more difficult. CoreLogic chief property economist Kelvin Davidson said falling house prices and rising rents had been the main drivers of improving yields.
So where are rental yields heading? He believes house prices are unlikely to surge again in the short term. Rents, however, have further room to rise because of strong rental demand and tight supply, which would allow yields to continue improving.
How attractive are rental yields to property investors?
Davidson said rising rental yields could bring investors back into the market, but a return of 3.1% was still low compared with current term deposit rates of around 5.5%. Investors have to consider the gap between rapidly rising mortgage rates and rental yields. In other words, even though rental yields have edged up recently, property investors will still weigh carefully whether to return to the market.
He warned that most properties would typically have negative cash flow at the outset, potentially for some time. This means buyers would need to contribute hundreds of dollars in actual cash each week to cover mortgage repayments. Such uncertainty over returns compares unfavourably with the fixed capital returns available from other investments. Davidson compared the gross rental yield of 3.1% with the standard two-year fixed mortgage rate of 7.1%. The resulting negative interest rate spread of 4% was the largest since the end of 2008.
Davidson stressed that if National won this year's general election and restored interest deductibility, it could help rental yields. Rules preventing mortgage interest from being deducted against rental income significantly increase investment costs. Restoring deductibility would therefore help landlords, potentially reducing their annual tax bills by NZ$5000.
It is worth noting that even restoring interest deductibility would not materially change the gap between yields and interest rates. Davidson advised prospective investors to weigh the pros and cons carefully. Changes to tax policy, rather than lower mortgage rates, would be the key factor in bringing investors back to the housing market. This is because tax changes could drive greater capital gains, whereas when interest rates begin to fall, the Reserve Bank could use other measures, such as debt-to-income (DTI) restrictions, to curb their impact on the housing market. New Zealand's property yields have in fact remained relatively high over past years. CoreLogic data shows that national gross yields have been around 4% since 2009.
Bayleys head of insights, data and advisory
Chris Farhi
Chris Farhi, Bayleys' head of insights, data and advisory, said national net property yields before tax and financing costs had returned to 2020 levels, but remained below the 5.0% yields seen at the start of the 21st century. He said that although investors' financial and tax circumstances differed, after-tax yields were generally low because of changes to interest deductibility. This had directly dampened enthusiasm for buying rental properties. Compared with five years ago, higher mortgage rates and the removal of tax relief had caused investor numbers to fall substantially.
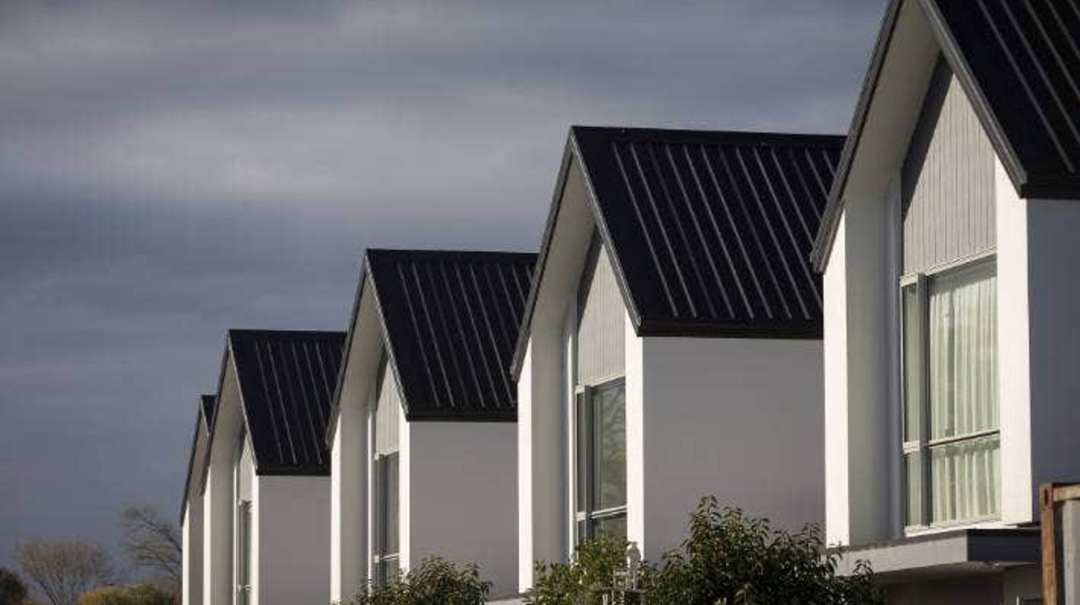
New builds are exempt from the new interest deductibility restrictions
Farhi said he was seeing more investors consider new builds because their tax advantages offered higher returns than existing homes. Under the new policy, new homes issued with a code compliance certificate after 27 March 2020 remain eligible for interest deductions for 20 years from the date of issue. He had also noticed that more new homes were townhouses or apartments, with more compact designs than traditional houses and often higher rents. Bayleys' nationwide survey found average net yields of 3.2% for houses and 3.6% for apartments and townhouses.
Farhi expects surging net migration and fewer new builds to tighten the balance between rental supply and demand, continuing to push rents higher. He said most economists expected house prices to rise steadily in the second half of this year, so yields could remain reasonably stable. This means current housing market trends are moving in a favourable direction for investors who already own property or are buying, as they are likely to continue seeing steady growth in both rents and property values.
According to Bayleys, the West Coast has New Zealand's highest net rental yield at 5.6%, while Auckland has the lowest at 2.9%.