
Important changes to buying a home with a 5% deposit: good news for first-home buyers! Which property market developments deserve the most attention this week?
Official labour market figures released by Stats NZ last week appear to have held few surprises. The employment rate continued to rise in the second quarter of this year
01
Latest labour market figures hold few surprises
Official labour market figures released by Stats NZ last week appear to have held few surprises. The employment rate continued to rise in the second quarter of this year, while the labour supply also expanded, largely thanks to strong net migration and higher wages attracting people back into work. In fact, the labour force participation rate has reached a record high of 72.4%. This means that, even as the employment rate rises further, the unemployment rate can also increase, moving from 3.4% to 3.6%. Even so, it remains very low. Overall, the strength of the labour market is consistent with the view that the property market has bottomed out.
With unemployment still low at 3.6% and wage growth remaining relatively high at 4.3%, the Reserve Bank of New Zealand may still consider another interest rate rise. This is because it wants to see the labour market soften, helping to curb high inflation. However, CoreLogic chief economist Kelvin Davidson says there is no need to panic: labour market weakness takes time to emerge, and overall inflationary pressure is also gradually easing in the meantime.
02
7: did house prices rise in New Zealand's main cities?
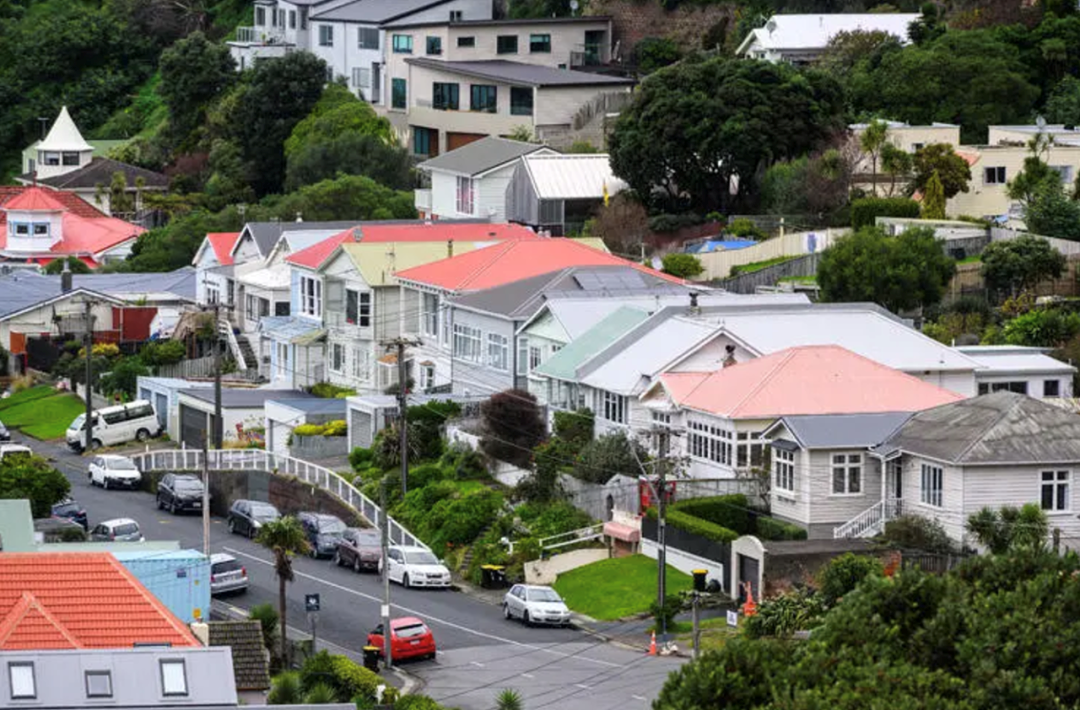
Wellington was among the few areas in New Zealand where house prices rose in July
According to CoreLogic's latest house price figures, prices rose across much of Auckland, including Papakura, Manukau and the North Shore, and Wellington, including the central city, Porirua and Upper Hutt, in July. Prices elsewhere in the country fell further. Even where fundamentals, such as strong employment and increased property demand from rising net migration, are translating into upward pressure on prices, that momentum is neither consistent nor widespread. Davidson believes the next phase of the economic cycle may bring only modest growth, as mortgage rates remain high and affordability remains stretched.
03
Government to amend First Home Partner shared ownership scheme
From 14 August, the Government will make changes to First Home Partner, its shared ownership scheme for first-home buyers. First Home Partner is the scheme often described as buying a home with a 5% deposit, developed through cooperation between the Government and banks. For eligible first-home buyers, the Government helps make up the deposit shortfall and shares ownership of the home. Follow the link to our earlier explanation: A step-by-step guide to government home-buying assistance for first-home buyers with an insufficient deposit
Since its launch in October 2021, the scheme has helped countless eligible individuals and families buy their first home jointly with Kāinga Ora. The Government has now made substantial changes, raising the household income cap and extending the scheme to include existing homes.
The main changes include:
- As well as new builds, all eligible applicants will be able to buy existing homes through the scheme, giving buyers a wider choice of properties.
- The annual household income cap for buyers will rise from NZ$130,000 to NZ$150,000.
- The income-cap criteria for intergenerational households have been broadened to cover a wider range of families, allowing eligible households with at least 6 family members who normally live together to buy a home through the scheme.
- These changes are expected to take effect from 14 August.
For full details, visit the relevant website by copying the address into your browser
https://www.hud.govt.nz/news/progressive-home-ownership-changes-increase-opportunities-for-first-home-buyers/
04
Latest Reserve Bank of New Zealand lending figures due
This week brings the latest Reserve Bank of New Zealand figures covering lending on floating and fixed interest rates. In recent months, around 70% of new loans, including top-ups and loans switched between banks, have been fixed for terms of up to two years. This pattern may continue for some time, as borrowers try to avoid locking in for too long in case interest rates begin falling at some point over the next year or two.
05
Will rent growth accelerate?
This Friday, Stats NZ will release its latest rental market figures. Rent growth accelerated in July. With rental demand rising and supply remaining tight, rental vacancy rates are expected to fall from 4% to 2.5%.
06
Further falls in building consents?
A report released by Stats NZ last week showed that applications for building consents for new homes in June were down 16% on the same period last year, marking the ninth consecutive monthly decline. Some commentators believe the fall in newly approved housing projects could be a key factor driving substantial house price rises over the next 6–12 months. Davidson takes a more cautious view. He points to the construction industry's long lead times, with many builders still working on projects consented earlier. In other words, a large number of new homes remain under construction. A substantial fall in building consent applications could certainly cause housing shortages in the future, but it is unlikely to be enough to affect house prices over the next year or so.