
Watch out! House prices are rising and investors are returning: is time running out for first-home buyers?
The property market's recovery began just 3 months ago, but its momentum has been strong
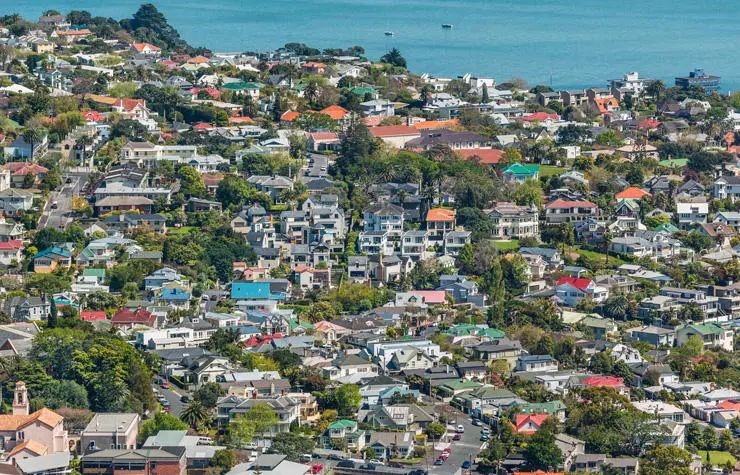
In a recent market survey report, well-known independent New Zealand economist Tony Alexander said his property data showed that, although the market's recovery began just 3 months ago, its momentum had been strong. Each month, Alexander conducts 5 targeted market surveys, emailing questionnaire invitations to more than 31000 people, including real estate agents, mortgage advisers, portfolio investors, residential property investors and ordinary consumers.
{ad}
Over the past half-year, he has closely tracked changes in the market. From February, he saw more first-home buyers returning. In March, increasing numbers of investors left the market, while commercial banks became more willing to lend. From May, he observed more prospective buyers attending open homes, followed by their return to auction rooms in June.
Since May this year, first-home buyers' share of property purchases has surged. By July, buyers' fear of missing out (FOMO) had risen sharply, and the property market nationwide was gradually shifting from a buyer's market to a seller's market. At the same time, he found that buyers' concerns about declining listing numbers had risen above the long-term average, while fears that prices would fall after they bought—fear of overpaying (FOOP)—were well below the long-term average.
In his monthly survey of mortgage advisers conducted with Mortgages.co.nz, Alexander identified a new market trend: 24% of mortgage brokers reported seeing more investors seeking advice on finance and interest rate options. This was the strongest positive market signal since January 2021. It suggests that, alongside strong demand from numerous young buyers, investor buyers may also return to the property market.
Why are investors returning to the market?
So why are investors choosing to return to the housing market while interest rates remain high? Alexander believes one reason is that house prices are now showing record-breaking upward momentum. After seasonal adjustment, average house prices rose by 0.7% a month over the three months to August, with particularly strong growth in the main centres of Auckland, Wellington and Christchurch. Generally, rising capital market prices lead to higher house prices, and we are now in the first stage of the house price cycle.
Alexander believes another reason is that surging net migration into New Zealand is putting pressure on housing supply and demand and pushing prices upwards. A monthly survey he conducts with property management company Crockers shows that existing property investors report easily finding tenants willing to pay higher rents. This could push rents up further, but for property owners, the bigger question is whether they can wait for rents to rise further before letting their properties.
He believes the third reason is the election result due in mid-October. If National is elected, full interest deductibility will be restored by the middle of 2026. Alexander's previous survey data showed that many investors withdrew from the property market when tax rules changed in March 2021. There is therefore reason to believe that, if the governing party changes, changes to tax deductibility rules will encourage investors to return.
Will the return of large numbers of investor buyers
cause house prices to surge?
CoreLogic Chief property economist Kelvin Davidson
CoreLogic chief property economist Kelvin Davidson recently said lending standards had eased. From 1 June this year, commercial banks could allocate 5% of new lending to property investors whose deposit requirement had fallen from 40% to 35%. Banks were also allowed to allocate 15% of new lending to owner-occupiers with 20% deposits, compared with the previous 10%. This means more lending activity and helps lift house prices. But will the return of large numbers of investor buyers trigger another surge in prices?
Alexander does not think so. Full tax deductibility for investment properties will take nearly 3 years to implement, so investors will return selectively and in stages. Persistently high interest rates, annual increases in maintenance costs, council rates and insurance premiums, and LVR limits on investment property lending also mean investors cannot all return at once. Banks remain very cautious about lending to new investors and will continue pressuring existing borrowers to reduce their debt before borrowing more. Taken together, these factors make house price increases unlikely in the near term, while the surge in mortgage applications has yet to truly begin.
Are opportunities for first-home buyers shrinking?
Based on current market trends, Alexander predicts average house price growth across New Zealand of around 5% this year, approaching 10% in 2024 and reaching 15% in 2025. He says this is the nature of an upswing in house prices, and the current cycle is only 3 months old. For young first-home buyers, sellers have been willing to accept offers with more conditions in a market with almost no competition. But as investor buyers continue returning, opportunities for first-home buyers are rapidly disappearing.