
A lukewarm reception for last week's Auckland Home Show? This reason could see consumers abandon kitchen and bathroom renovation plans
New Zealand's largest home exhibition, the four-day Auckland Home Show, came to a close last Sunday
New Zealand's largest home exhibition, the four-day Auckland Home Show, came to a close last Sunday, with overall visitor numbers seemingly well below those at the April event. After a three-and-a-half-year absence caused by the COVID pandemic, the show returned in April to reports of unprecedented crowds, with thousands flocking to the venue. Last week, YIJU heard from people working at kitchen cabinetry stands that the April show coincided with many households needing kitchen renovations after Cyclone Gabriella and the Auckland floods, prompting a surge in enquiries. Demand was noticeably weaker at the September show. What caused the change?
Reports suggest that rising mortgage rates are putting unprecedented financial pressure on ordinary New Zealand households, while the number of homeowners missing mortgage repayments continues to grow. Credit bureau Centrix reported that 18,800 mortgage accounts were overdue in July this year, up 31% on July last year, but below the 19,300 accounts in arrears in March. Over recent weeks, ANZ, ASB, BNZ and Westpac have all raised their mortgage rates. Standard one-year and two-year rates are now well above 7%, even approaching the historical high of 8%. The latest mortgage rates from the major commercial banks are listed below:
{ad}
These soaring rates mean many borrowers about to move onto higher rates will have to pay an average of NZ$1200 more each month. For many homeowners, rising mortgage costs could become one of the heaviest burdens in their lives. According to Centrix, 240,000 mortgage holders nationwide owe more than NZ$500,000, while just 42,500 owe less than NZ$50,000.
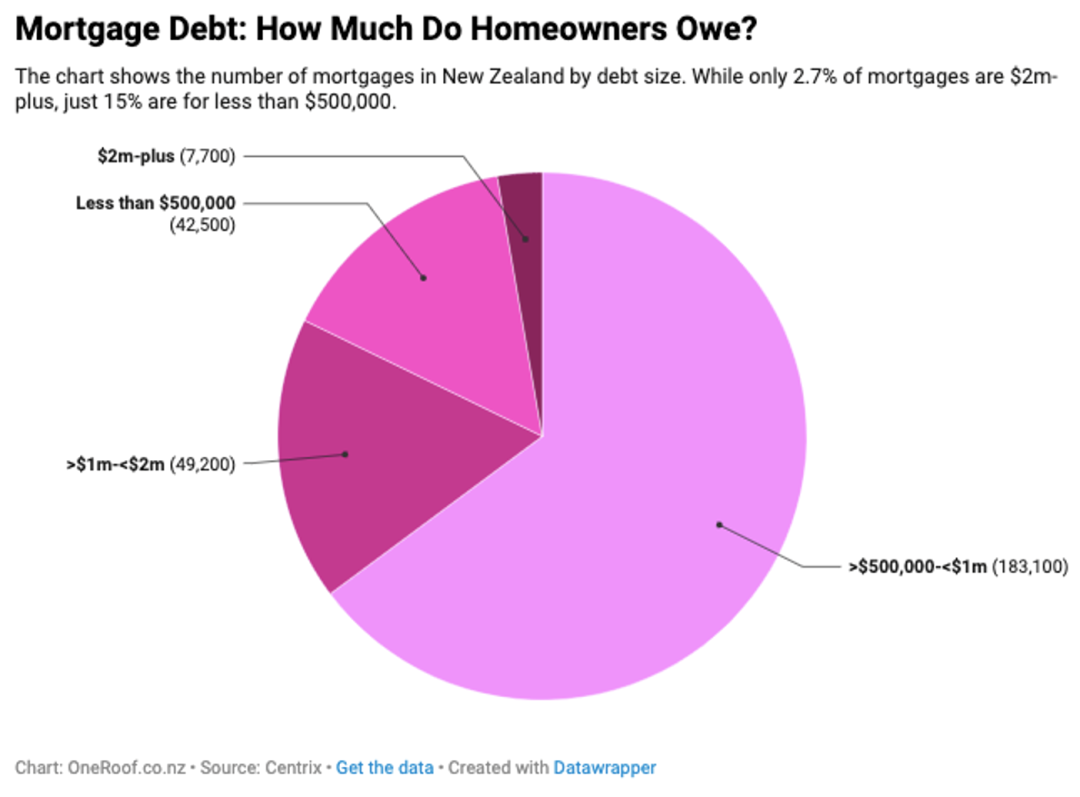
Proportions of New Zealand borrowers by outstanding loan amount (Source: Centrix)
In other words, households under heavy mortgage pressure cannot afford renovations or major purchases. Figures released by the Reserve Bank of New Zealand in July show that the number of homeowners topping up their mortgages to buy big-ticket items or renovate their homes has fallen by almost half since 2021. Mortgage top-ups totalled just NZ$7,700,000,000 over the 12 months to July 2023, well below the NZ$13,600,000,000 borrowed in top-ups during the earlier 12-month period ending in July 2021.
Loanmarket mortgage adviser Rodney King said top-up borrowing for new kitchens and bathroom renovations had fallen markedly, possibly by more than the decline estimated by the Reserve Bank of New Zealand.
The Lending Team mortgage adviser Neville Modlin also said Cyclone Gabriella and the Auckland floods earlier this year had played a part, with insurance payouts replacing some of the additional borrowing needed for renovations.
Campbell Hastie of Hastie Mortgage Limited said fewer clients were applying for mortgage top-ups. He had received about 40 applications last year, compared with just 15 so far this year, a substantial decline. Most were for less than NZ$100,000, typically between NZ$20,000 and NZ$50,000. He believed rising interest rates and living costs were prompting people to cut unnecessary spending rather than undertake major building work. Joe Public agreed, saying the introduction of the Credit Contracts and Consumer Finance Act (CCCFA) had prevented many applicants from accessing loans. Together, these factors would reduce demand for borrowing.
Canstar general manager Jose George said its research showed New Zealanders were currently “hunkering down”. He believed that if New Zealanders find they have spare money, making extra mortgage repayments is the wisest move, because every additional payment can make a substantial difference to the total interest paid over the loan's lifetime. Those needing to refix could also consider shortening their mortgage term, increasing repayments while reducing the interest paid over the longer term. Borrowers can also use this opportunity to make a substantial lump-sum repayment without incurring break fees. His final suggestion was that borrowers with funds available who did not want to put them towards their mortgage in one lump sum could consider a term deposit or savings account, earning very attractive interest with considerable security. Given the difficult financial times, this could be a good option.