
What does National's return to power mean for housing? This week's key developments for property investors
National may still need New Zealand First to form a government, leaving some uncertainty for the time ahead.
|
What does National's victory mean for the housing market? |
We imagine YIJU New Zealand readers were watching their screens last Saturday, just as we were, waiting for the final result of New Zealand's 2023 general election. In fairness, National's return to power was in line with most voters' expectations. However, National may still need New Zealand First to form a government, leaving some uncertainty for the time ahead.
Fortunately, New Zealand First seems more focused on policy changes affecting other aspects of people's lives than on housing. This makes it highly likely that the bright-line test period will be shortened next year. Mortgage interest deductibility for property investors will also be restored in stages, whether properties are new or existing, regardless of their type or age. Proposals to ease restrictions on overseas buyers will also be discussed further and approved.
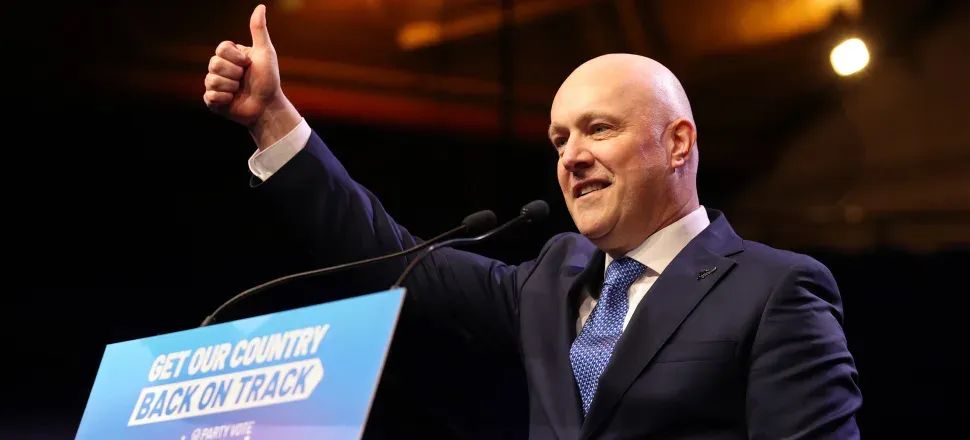
National Party leader Christopher Luxon declared victory in the election last Saturday
The election result is widely expected to lead directly to house price rises over the next year or two. However, CoreLogic Chief Property Economist Kelvin Davidson believes several factors will prevent another price surge: affordability remains a major issue; interest rates will not fall quickly in the short term; and mortgage debt-to-income limits will remain in effect in 2024.
For investors planning to buy property, lower tax rates can effectively improve investment returns. However, given current low rental yields and high mortgage rates, investors will still need to cover the gap between monthly mortgage payments and rental income themselves. Over the longer term, if National reduces regulation of the property market and slows housing intensification in major cities, this will put upward pressure on house prices. Davidson believes this effect will emerge gradually over a long period rather than all at once.
|
Will the latest consumer price index keep rising? |
With the 2023 election over, this week's main event will be Stats NZ's consumer price index (CPI) release on Tuesday. It will play a crucial role in determining whether the Official Cash Rate (OCR) is raised again in this cycle.
In its latest Monetary Policy Statement, the Reserve Bank of New Zealand said it expected quarterly CPI growth of 2.1 in the third quarter and annual growth of 6.0%, unchanged from the second quarter's annual figure. This means that if Tuesday's release shows third-quarter inflation remaining unchanged or falling, another OCR increase on 29 November will become less likely. Conversely, any increase in CPI would strengthen market expectations of another OCR rise.
However, the market outlook may not be as harsh as we imagine. Davidson maintains that, whether or not the OCR rises, the effect on future mortgage rates will be very limited because the largest interest rate increases are already behind us. The OCR is also not the only factor influencing 1–2 year fixed mortgage rates; banks' offshore funding costs are another key consideration.
|
Is construction cost growth slowing? |
The Cordell Construction Cost Index released last week showed that inflation in new-home construction costs has slowed. Quarterly inflation eased to 0.5% in the third quarter, while annual inflation fell to 3.4%, a substantial decline from its peak of 10.4% at the end of 2022. Slower construction cost growth reflects easing supply chain pressures and reduced pressure on industry capacity as fewer projects get under way. However, slower growth does not mean construction costs are falling. With labour costs, which account for 40–50% of total project expenditure, unlikely to fall, a decline in construction costs appears unlikely.
|
Is net migration still surging? |
Net migration figures released by Stats NZ last week showed a record net gain of more than 110,000 people in the year to August. The effect of this increase on the property market is clear: rising demand is putting significantly greater upward pressure on rents.
|
Is the property market's path to recovery still unclear? |
Readers may have noticed that the latest property sales volumes and prices were somewhat weaker than most people expected. This suggests that New Zealand's economy will not rebound sharply after a period of decline, even with the Reserve Bank of New Zealand's revision to the rate of GDP decline. Davidson noted that the path to economic recovery remains uncertain, particularly while affordability is constrained, mortgage rates remain high and mortgage debt-to-income limits are still set to apply next year. We therefore have reason to believe that, whichever party takes power, “whether a cat is black or white, it is a good cat if it catches mice”. In other words, what matters is who can restore investors' ability to deduct mortgage interest in full from rental income.
|
Rent growth accelerates again |
Stats NZ's latest rental figures, released last week, showed annual rent growth of 7.2% in the year to the end of September. This was the second-highest increase since 2008, exceeded only by the 7.8% recorded in September 2021.(Coming up: follow YIJU New Zealand's WeChat official account tomorrow for an in-depth analysis of the rental market's continuing rise.)
{ad}