
Could selling an Auckland property deliver a NZ$3,000,000 profit in one go? Key developments for property investors this week
93.3% of sellers made a profit when reselling their property!
Last week, Stats NZ released key official labour market data for the fourth quarter of last year. Unemployment rose from 3.9% in the third quarter to 4%, its highest level since the second quarter of 2021. However, with both job numbers and employment still growing, the slight rise in unemployment reflected an expanding labour force. Viewed against historical data, unemployment of 4% remains relatively low, while wage growth has stayed at a “reasonable” level of around 4%.
Overall, the latest labour market data may not be as weak as the Reserve Bank of New Zealand expected, reinforcing to some extent the likelihood that the Official Cash Rate will not be cut any time soon. On the other hand, high employment remains good news for households facing mortgage repricing in the period ahead.

The latest CoreLogic Pain & Gain Report shows that, at the end of 2023, the proportion of sellers accepting less than their purchase price, and therefore making a loss, remained relatively low at 6.7%, down from 7.6% in the third quarter of last year. This suggests there has been no large-scale emergence of bad or non-performing loans despite sharply higher mortgage rates, demonstrating the labour market’s strong resilience.
In other words, 93.3% of sellers made a profit on resale, also indicating that the vast majority of homeowners have held on to their properties through this round of interest rate increases. Of course, the length of ownership is also a key factor in whether a resale produces a profit. The data show that if sellers have held a property for 7–8 years, the market’s overall performance during that period will inevitably deliver capital gains. However, for owner-occupiers, this is not a windfall, as the additional equity is absorbed into their next property purchase.
The transaction with the highest resale return in the fourth quarter of last year involved a property worth NZ$3,400,000 in Auckland’s Remuera. The seller bought it more than twenty years ago for NZ$2,100,000 and sold it in November for NZ$5,500,000.
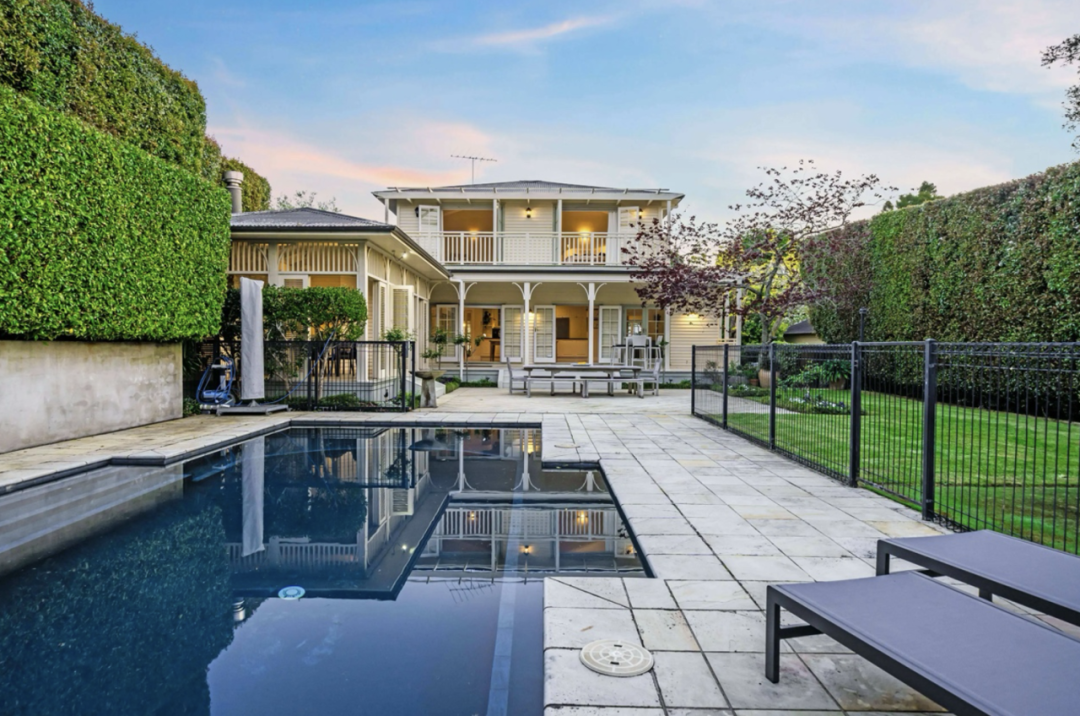 The property on Woodley Avenue in Remuera sold in November 2023 for NZ$5,500,000, NZ$3,400,000 above its previous sale price. Image source: NZ Herald
The latest Reserve Bank of New Zealand data show that 74% of new lending in December was fixed for two years or less. This was the third-highest proportion since the end of 2020, exceeded only in March and April 2023. In other words, as mortgage rates peak and expectations grow that rates will start falling over the medium term, more borrowers are sensibly choosing shorter fixed terms.
This Wednesday, Stats NZ will release rental price data for January, followed on Thursday by net migration data for December. New Zealand’s population has grown rapidly over the past 12 to 18 months because of substantial net migration inflows. The latest data suggest this growth will continue, placing unprecedented pressure on the stock of rental properties. This reflects strong demand as well as a shortage of new properties entering the rental market. One explanation is that landlords’ property purchasing activity has remained subdued in recent years. This is clearly a headache for tenants, as it has also driven rents steadily higher.
At 3 pm this Friday, the Reserve Bank of New Zealand will release debt-to-income data for new mortgages issued from October to December last year. With new debt-to-income rules due to take effect from the middle of 2024, actual market data and trends deserve particular attention. CoreLogic chief property economist Kelvin Davidson said that, given high mortgage rates already constrain borrowing, the latest figures for high-DTI lending are likely to remain low for an extended period. In practice, DTI caps are unlikely to affect the market immediately, but as mortgage rates fall over the medium term, they will begin to constrain borrowers’ borrowing capacity. Banks will, of course, continue lending to investors, but are likely to slow lending growth across their portfolios.