
Will the Reserve Bank of New Zealand resume rate hikes this Wednesday? This week’s key events for property investors
Not long ago, ANZ forecast that the official cash rate (OCR) would rise twice more before the next round of rate cuts began.
At two o’clock this Wednesday afternoon, the Reserve Bank of New Zealand will announce its latest official cash rate (OCR) decision, alongside forecasts for other key economic indicators, including inflation, GDP, employment and house prices. At the start of this year, economists generally expected interest rate cuts to begin around mid-year. Those views have shifted as time has passed and more economic data has been released.
Not long ago, ANZ forecast that the official cash rate (OCR) would rise twice more before the next round of rate cuts began. Its latest forecast puts an increase this week from the current 5.5% to 5.75%, followed by another rise in April.
So what caused this shift? What is keeping interest rates elevated, and when will borrowers finally see rates fall?
Infometrics Chief Executive Brad Olsen explained that concerns about the Reserve Bank of New Zealand raising the OCR this week stemmed from its last monetary policy update in November and recent, less encouraging economic data. In November last year, the Reserve Bank slightly raised its projected OCR track, setting the peak at 5.7%.
Because the Reserve Bank usually raises the OCR in increments of 25 basis points, that projected track suggested it was leaning towards another increase, although the time was not quite right. Its tone was also firm: any surprises in the economic data would leave the door open to another hike.
GDP data released subsequently in December last year was weaker than expected, providing some evidence that the Reserve Bank’s policy efforts were having an effect. Olsen noted that this was also the main reason swap rates fell, with the one-year wholesale swap rate dropping from 5.56% on 13 December to 5.32% on 15 December. The economy’s weakness pointed to easing inflationary pressure and would help the Reserve Bank begin cutting rates sooner.
The latest inflation figures, released not long ago, were less satisfying for the Reserve Bank. Although the headline figure was below expectations, domestic inflation remained stubbornly strong. In a speech, Reserve Bank Chief Economist Paul Conway highlighted lingering market risks that could keep interest rates elevated. Financial markets then began to waver in their expectations of an OCR cut around mid-year. Unemployment figures released subsequently were stronger than expected, with wage growth in particular presenting a further obstacle to the anticipated rate cuts.
ANZ ultimately made a substantial revision to its interest rate forecast, switching from a possible cut in August to two hikes, in February and April. Markets reacted quickly. Although swap rates had not returned to their levels at the beginning of December, they were clearly trending upwards. Even economists who initially disagreed with ANZ’s call for rate hikes now had to acknowledge that another increase was possible.
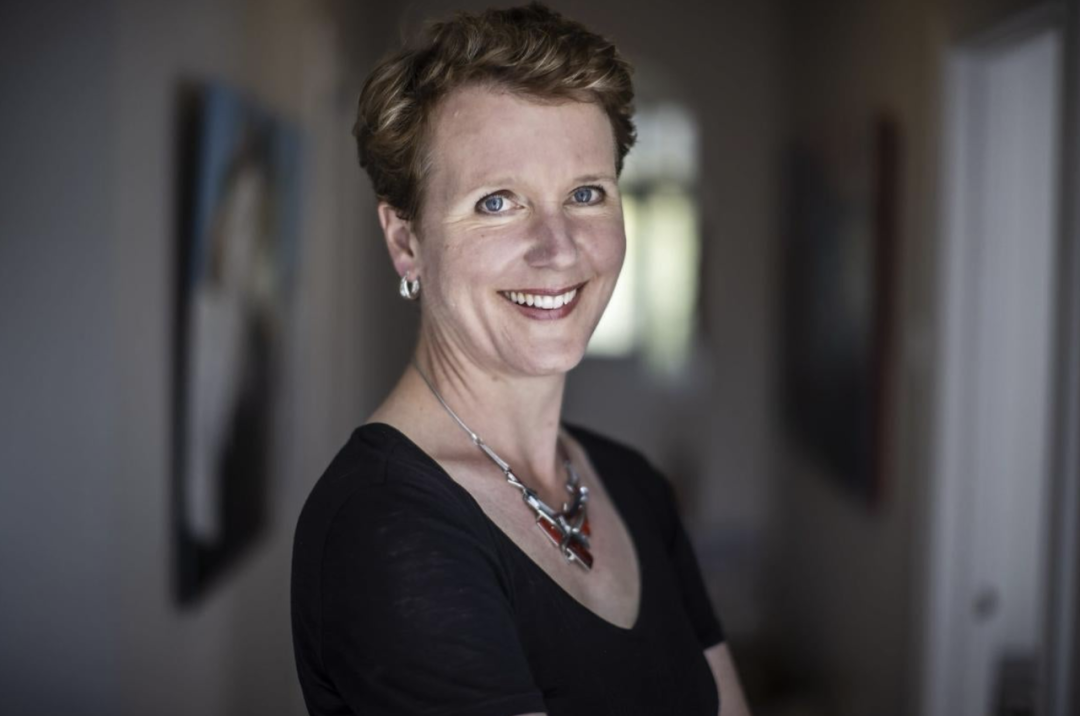 ANZ Chief Economist Sharon Zollner
For mortgage borrowers, some recent developments in financial markets have been puzzling. Although ANZ has forecast an OCR increase, this has not actually been reflected in retail interest rates. BNZ and Westpac have instead lowered their rates.
Olsen said borrowers wanting to avoid potentially unsettled interest rates over the coming months could fix for a year or 18 months. He did not think this turbulence would involve large swings. Smaller, less predictable changes were more likely, potentially continuing over the next 12 months. He suggested borrowers ask their lenders how further rate increases would affect their repayments.
Squirrel Chief Executive David Cunningham said there was now an almost universal expectation that rates would only fall by around 1% a year from now. He believed borrowers would be better off choosing short fixed terms, otherwise risking being locked into higher rates. He expected all central banks worldwide to begin cutting rates between June and September this year, with markets expecting the Reserve Bank of New Zealand to start cutting in November.
ANZ Chief Economist Sharon Zollner said there was no need for excessive concern. Any further hikes now could lead to faster cuts next year. With rates rising and then falling relatively quickly, the effective mortgage interest rates borrowers actually paid would change little. She suggested borrowers could split their home loans into several portions and fix them for different terms to spread repayment risk.
Alongside GDP data, New Zealand’s economic activity index, released last week, was another important indicator suggesting the economy was growing steadily and had not entered a recession. This was very encouraging insofar as active economic conditions continued to support the labour market. At the same time, it could keep inflation elevated for longer, making it harder for mortgage interest rates to fall.
The Reserve Bank of New Zealand’s mortgage lending figures for January will be released this week. Trends over recent months suggest that, although the figures may show a further increase in loan numbers, growth will be limited and the overall base will remain low. Recent data shows that both borrowers and lenders remain cautious about low-deposit, high-LVR lending. For example, 7–8% of recent owner-occupier lending involved deposits below 20%, well below the 15% limit.
Stats NZ will also release its latest employment figures for January this week, which are likely to show another increase in the number of people employed. More jobs and more people in work are clearly positive for those seeking new mortgages or needing to adjust existing loans to cope with higher interest rates. On the other hand, higher employment often brings some inflationary pressure, hindering progress towards the inflation target range.
Residential building consent figures for January will be released this Friday. The downward trend in consent application numbers may continue for some time. With population growth remaining strong, we hope applications will bottom out and recover soon; otherwise, housing shortages could quickly re-emerge.