
Take note: ANZ warns first-home buyers! Will changes to bank lending rules give these buyers greater purchasing power?
As interest deductibility was phased out, many investors began selling older rental properties. Now, these investors are set to hold on to them because they will once again be entitled to deduct interest.
The latest survey figures from New Zealand’s Tenancy Services show that the national median rent reached a new high at the start of 2024. In January this year, the national median residential rent was NZ$608 a week, up NZ$28 (+4.8%) from December and NZ$33 (+5.7%) from the same time last year. In Auckland, the country’s largest rental market, the median rent in January was NZ$650 a week.
Property auction activity is also showing signs of recovery after a period of decline. Last week, 568 residential properties went to auction nationwide, the third-highest weekly total in more than a year. Of these, 127 sold, giving a clearance rate of 31%, while 42% of properties sold at or above their capital value (CV). There is reason to believe that as rents continue to rise, more property investors will consider returning to the market.
ANZ recently announced that it had changed its rental property lending rules to support property investors, making it easier for them to buy existing properties. The bank is understood to be increasing the proportion of rental income it recognises when assessing lending applications for existing rental properties.
An ANZ spokesperson subsequently confirmed the change, saying the bank had simplified its loan application process for property investors. Its rental income calculations now include rates and insurance costs, as part of its regular review of affordability settings. Observers expect other banks to follow suit.
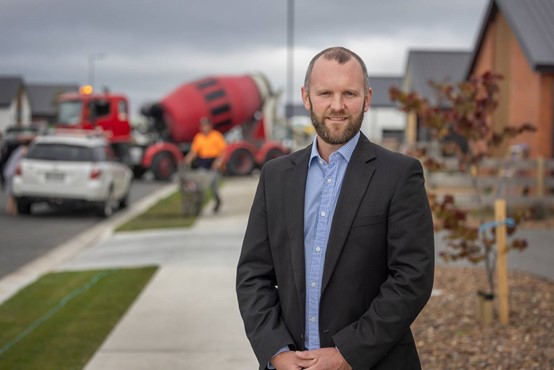
Gareth Veale, a financial adviser at EasyStreet Mortgage, believes the changes make it easier for investors to buy existing homes. He welcomed ANZ being the first bank to take this step after the Government confirmed that interest deductibility would begin to be restored for all rental properties from 1 April, and expects other banks to follow soon.
Veale further explained that when the Labour government removed interest deductibility for existing properties, it became more expensive to buy them relative to new builds. Now that the new Government is restoring interest deductibility, banks are moving towards treating all rental income equally. Investors whose portfolios include existing properties have therefore seen a considerable increase in their investment returns. Previously, when calculating borrowing limits, ANZ included 12–24% of income, excluding interest and insurance costs. Under the new rules, around 27.8% of income, including interest and insurance costs, will be counted, a change that is clearly more favourable to borrowers.
BNZ is currently the only bank in the market that treats existing homes and new builds equally, counting around 30% of rental income. Veale said that while obstacles to buying investment properties remain, including high interest rates, the latest move substantially improves investors’ opportunities to buy existing homes. He observed that as interest deductibility was phased out, many investors began selling older rental properties. Now, these investors are set to hold on to them because they will once again be entitled to deduct interest.
 CoreLogic chief economist Kelvin Davidson
 said that although tax rates had fallen, bank lending rules were more favourable to investors, and changes to loan-to-value ratio (LVR) and debt-to-income rules were approaching, interest rates remained the biggest obstacle to obtaining a new mortgage, particularly given that they were unlikely to fall in the near term.
He believes that following ANZ’s changes to its lending rules, other banks may ease other aspects of their lending application requirements. Both first-home buyers and investors have a reasonably balanced mix of demand for new builds and existing homes. Although the latest changes may encourage more investors to buy, he does not expect a surge in demand for any particular property type. Are these recent changes to lending rules reshaping the property market’s “rules of the game”? That remains to be seen.