
Major announcements: tax cuts, benefits and legislative changes! Prime Minister unveils priorities for the next three months! This week’s key developments for property investors
Long-awaited personal income tax relief is set to be legislated, with further developments also expected on the family childcare subsidy scheme.
On Tuesday morning, New Zealand Prime Minister Christopher Luxon released his priorities for the next three months. Plans relating to property and construction include:
Implementing the Going for Housing Growth plan; making MDRS (rapid residential development areas) optional for local councils; responding to the independent financial review of Kāinga Ora; introducing legislation to improve the rental market; seeking public feedback on plans to ease restrictions on importing building materials; legislating amendments to the Resource Management Act; and introducing reforms to the CCCFA (Credit Contracts and Consumer Finance Act) regime to help homebuyers access credit.
Long-awaited personal income tax relief is also set to be legislated, with further developments expected on the family childcare subsidy scheme. The Government will also decide whether to reinstate the three strikes legislation.
Last week, the Reserve Bank of New Zealand released its latest breakdown of mortgage lending. The figures show that 59% of existing loans will be repriced within the next year. Based on current interest rate trends, these borrowers could face another rate increase, potentially of around 1%. More significantly, many borrowers in this group will still be moving from low fixed rates to higher ones, meaning many homeowners will continue to face substantial mortgage repayment risks. Some data suggest this pressure is set to rise again after a prolonged period of stability.
The Reserve Bank’s figures also show that in February, new lending totalled NZ$4,900,000,000, up NZ$1,100,000,000 year on year, marking the seventh consecutive month of growth. Overall, total new lending continues to rise steadily.
Looking more closely, the share of low-deposit mortgages has not declined, while lending to investors with deposits below 35% remains very low. In February, around 8% of owner-occupier lending was issued with deposits below 20%, still well below the Reserve Bank’s 15% limit. Notably, among owner-occupier borrowers, most mortgage lending still went to first-home buyers.
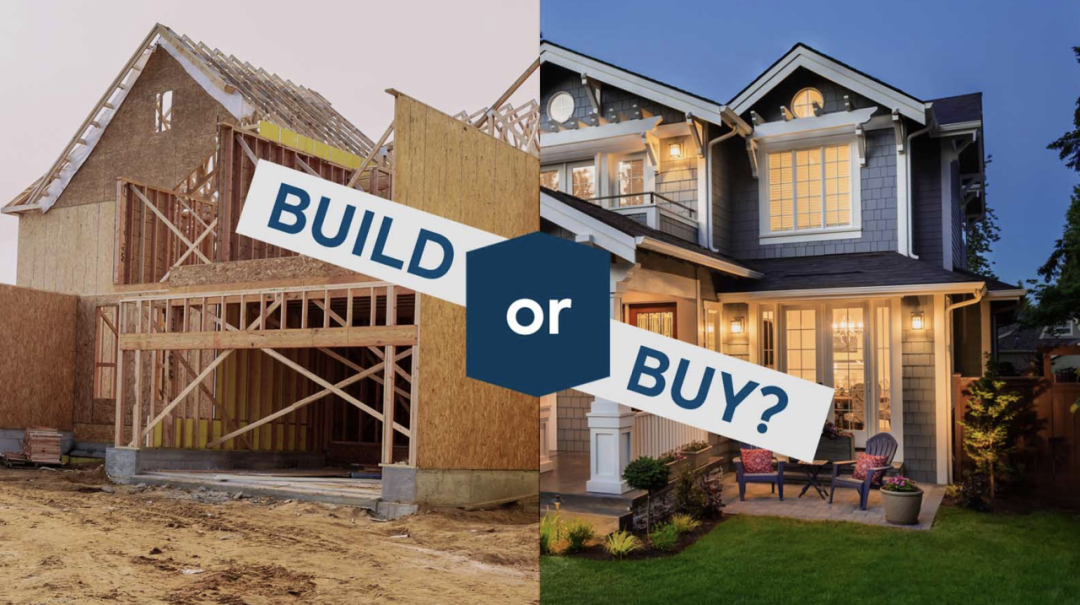
The price gap between new builds and existing properties has widened over time and currently stands at around 6%. In theory, new homes offer better quality, such as insulation, than typical existing homes, along with lower maintenance costs, so their higher prices are understandable.
However, the tax and lending advantages enjoyed by new builds in recent years have helped them perform better in the property market, with more demand shifting towards new homes. This trend may not last. As property investment cools and tax rules change, new builds may gradually become less popular. Once mortgage interest deductibility is fully restored, some investors may return to buying existing properties. Meanwhile, with many developers struggling to secure presales, discounts on the final selling prices of new builds are also likely to grow.
Last week, ANZ’s March business and consumer confidence indices both fell, an unwelcome result. At least inflation is still moving in the right direction, particularly in business input costs, pricing intentions and overall inflation expectations. Overall, there is little evidence that the Official Cash Rate will be cut in the near term or that mortgage rates will fall substantially. The encouraging prospect is that this moment is gradually drawing closer.
This Wednesday, Stats NZ will release employment figures for February, which are likely to show further job growth, providing some support for a property market recovery. Figures on new dwelling building consent applications for February will also be released this Thursday. These may be less encouraging, with application volumes likely to decline further.