
Good news! Construction cost pressures continue to ease. National house prices edge down, but are these buyers still keen? This week’s key events for property investors
New Zealand’s latest net migration figures will also be released this week. Although migration has passed its peak, the April figures are likely to show a net gain of more than 100,000 people over the past 12 months, roughly three times the long-term average. In other words, new migrants are still having a substantial influence on supply and demand in the local property market.
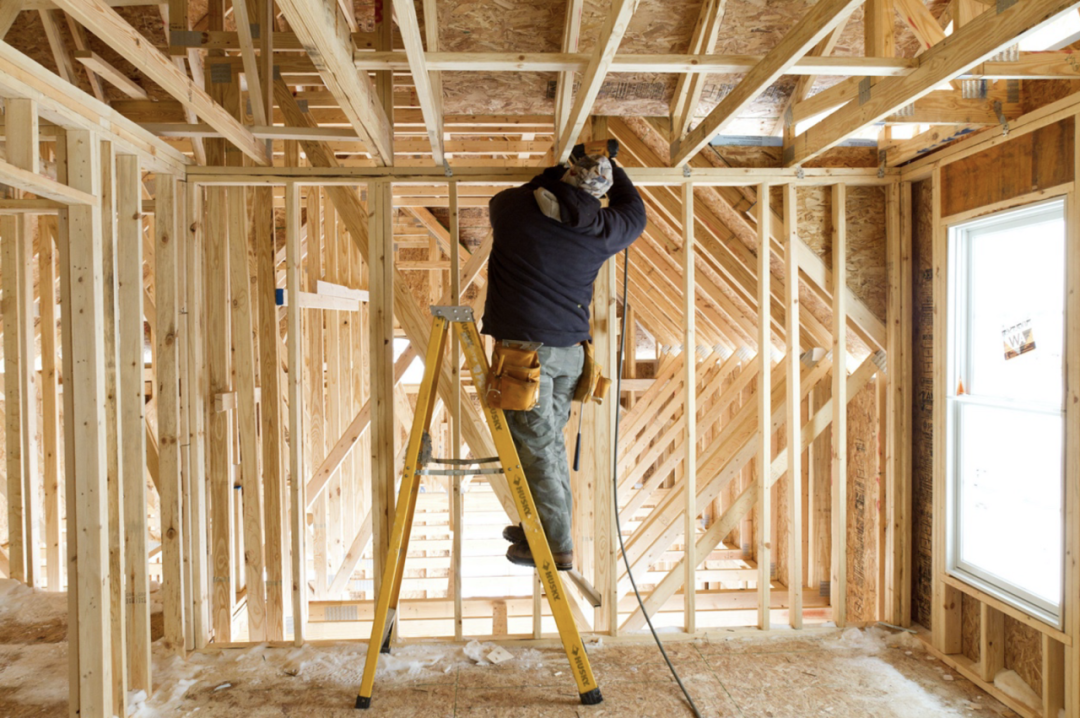
Construction cost pressures continue to ease
The latest figures from QV’s CostBuilder database show that upward pressure on New Zealand construction costs is continuing to ease.
After tracking changes in more than 60,000 individually priced construction items, CostBuilder reportedly found that the average cost of building a three-bedroom home rose just 1.8% in the 12 months to the end of May. This was well below the 4.9% rise over the whole of 2023 and the 9.5% increase in the 12 months to June 2023. These figures suggest price growth could slow further. QV CostBuilder spokesperson and quantity surveyor Martin Bisset said falling construction cost inflation was good news for everyone currently considering or pricing new building projects.
Notably, overall construction costs rose just 0.3% in the three months to the end of May. Exterior wall costs recorded the largest increase, rising an average of 0.8%. Meanwhile, framing costs fell 0.7% over the same period as structural steel prices declined. Foundation preparation costs fell 1.6% overall.
Non-residential construction cost growth is also slowing, with an average increase of 0.9% in the 12 months to the end of May this year, down from 4.7% in the 12 months to December 2023.
Will the Reserve Bank of New Zealand cut rates sooner?
Last week, the central banks of two major developed economies began cutting interest rates ahead of the US Federal Reserve. First, the Bank of Canada announced on the 5th, local time, that it would cut its benchmark rate by 25 basis points, from 5% to 4.75%. This was its first cut since the end of March 2020. Then, on the 6th, the European Central Bank announced a 25-basis-point cut after maintaining high rates for 22 consecutive months. Many analysts also expected the Bank of England, which would hold its rate-setting meeting a week later, might follow the European Central Bank and the Bank of Canada.
Meanwhile, ANZ announced last Friday that it had revised its Official Cash Rate (OCR) forecast, bringing its expected first cut forward from May next year to February. Chief economist Sharon Zollner also said that before cutting the OCR, the Reserve Bank of New Zealand would need to be confident not only that CPI (Consumers Price Index) inflation was heading towards 2%, but also that it would subsequently remain within the 1%–3% target range.
National house prices edge down
CoreLogic’s May house price figures showed national prices fell 0.2%, following a 0.1% decline in April. Although small, the declines indicate that the property market has stalled. Mortgage rates remain a major challenge, listings are elevated, and pricing power has shifted back to buyers. There are some regional differences: prices fell in Auckland, Wellington and Tauranga, but rose in Hamilton, Christchurch and Dunedin.
CoreLogic chief economist Kelvin Davidson cautioned that recent housing policy changes would have mixed effects on the market. Easing loan-to-value ratio (LVR) rules would clearly support a stronger property market, but removing the First Home Grant and introducing debt-to-income rules could have some negative effects. Upcoming changes to the bright-line test would also help keep listings relatively high.
Needs-driven buyers maintain their share of the buyer’s market in May
CoreLogic’s May buyer figures showed first-home buyers continued to account for 25% of purchases, still close to a record high. Relocating owner-occupiers’ share hovered around 27%, while mortgaged multiple-property investors accounted for 21%. First-home buyers and investors always attract market attention, but relocating owner-occupiers also deserve consideration. They have moved relatively infrequently over the past few years, so there may be some pent-up demand to change homes.
Are short-term fixed rates still the most popular?
This week, the Reserve Bank of New Zealand will release its latest housing lending figures, showing the fixing terms borrowers chose in April when buying a home, switching banks or topping up their mortgages. More borrowers have recently chosen shorter fixing terms of 6 months or 1 year, which seems reasonable given expectations of substantial mortgage rate cuts. Borrowers should bear in mind that cuts may not arrive until 2025, and current short-term fixed rates are considerably higher than longer-term rates.
Has net migration growth passed its peak?
New Zealand’s latest net migration figures will also be released this week. Although migration has passed its peak, the April figures are likely to show a net gain of more than 100,000 people over the past 12 months, roughly three times the long-term average. In other words, new migrants are still having a substantial influence on supply and demand in the local property market.
Is rental growth slowing too?
The forthcoming rental price figures, covering May, are likely to show a continuing slowdown. This is good news for tenants, but less welcome for landlords. Slower rental growth may partly reflect easing wage growth, which limits tenants’ ability to pay, alongside an increase in the supply of rental homes.