
Housing stock hits a 12-year seasonal high and asking prices keep falling: why has New Zealand’s construction industry not collapsed?
As New Zealand’s housing market enters spring, are homes becoming harder to sell?
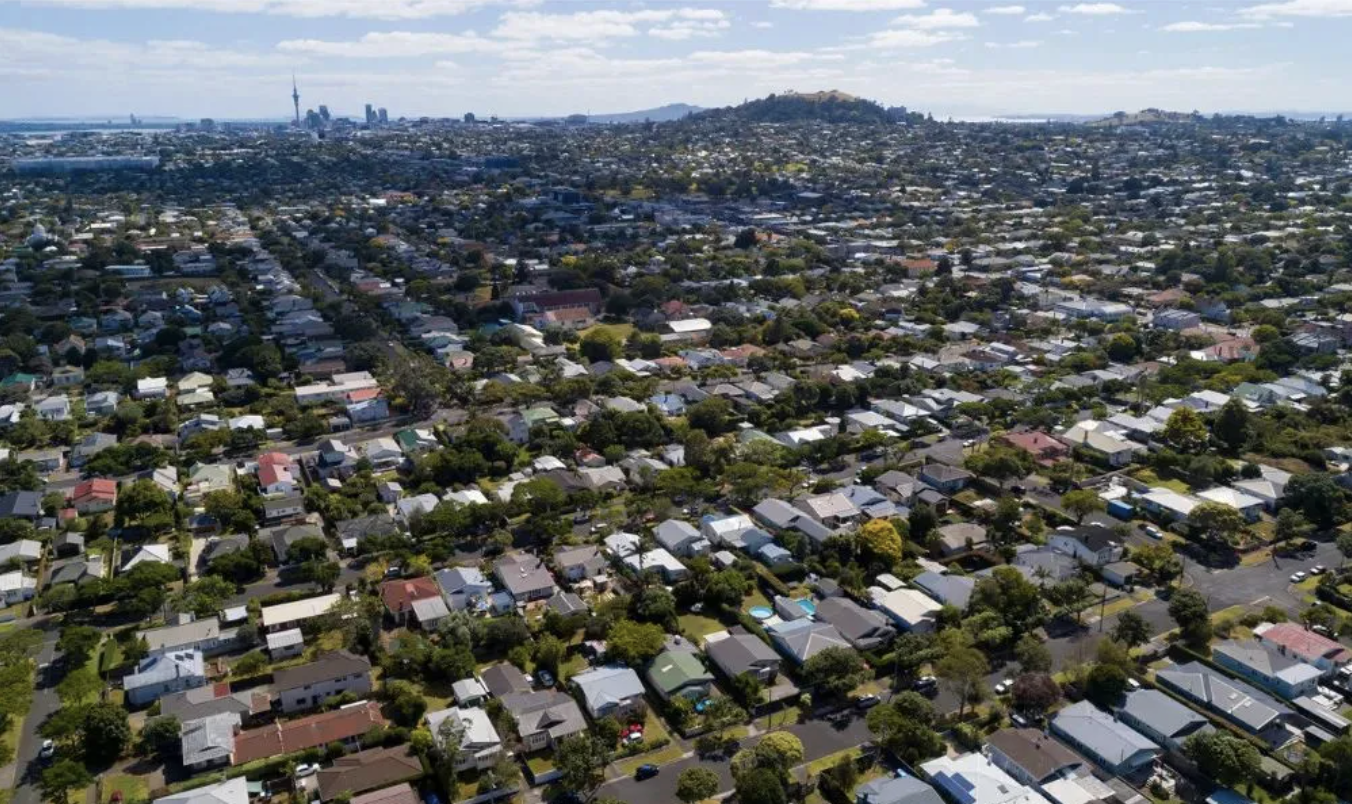
At the end of August, Realestate.co.nz had 32,908 residential properties for sale, up 9.7% from the same time last year. This was the highest level for this time of year in 12 years and more than twice the stock available during the 2021 housing market peak.
The increase in stock is not the result of a sudden influx of listings. There were just 8,326 new listings nationwide in August, down 5.1% year on year. Falling new listings alongside rising total stock indicate that many homes have been on the market for some time, with sales slowing markedly.
Sellers are also adjusting their expectations. The national average residential asking price was NZ$824,144 in August, down 2% year on year. Asking prices have fallen for six consecutive months, dropping NZ$74,533, or 8.3%, from February this year.
Auckland’s adjustment has been more pronounced. Its average asking price fell to NZ$986,827 in August, down NZ$110,921 from February, a decline of 10.1% in just half a year.
By the usual logic, high stock levels, falling asking prices and buyers waiting on the sidelines would quickly affect new housing development and construction. This time, however, another set of figures tells a different story.
In the year to July this year, 40,908 new homes were granted building consent nationwide, up 21% year on year. Meanwhile, 68% of builders reported stable or strong project pipelines for the coming year, up from 64% last year. The proportion describing their order books as “severely diminished” fell from 11% to 6%, almost halving.
Homes are becoming harder to sell, yet the construction market has not continued to collapse. A seemingly contradictory picture is emerging in New Zealand’s housing market.
New home consents rise 21% as construction activity shows signs of stabilising
Stats NZ figures show that 3,579 new homes were consented nationwide in July this year alone, up 10% from the same month last year.
Over the 12 months to July, 40,908 new homes were consented nationwide, up 21% year on year. That equates to 7.7 consented homes per 1000 residents, also above the previous year’s 6.4.
This growth was not confined to a single housing type. Over the past year, 18,884 standalone houses were consented, up 20% year on year. Townhouses and units reached 17,829, up 23%; apartments rose 11% to 2,509; and retirement village units increased 14% to 1,686.
Regionally, Auckland remained the largest new housing market, with 17,260 homes consented, up 20% year on year. Canterbury reached 8,732, up 33%, with growth mainly coming from Christchurch and Selwyn. Waikato, Otago and Wellington also all recorded double-digit growth.
These figures show that new housing development has not ground to a halt across the board as existing-home stock rises. After several years of project cancellations, business failures and shrinking order books, construction is showing signs of stabilising.
Master Builders’ annual industry survey reflects a similar trend: 68% of builders reported stable or strong project pipelines for the coming year, while the proportion of businesses severely short of work fell significantly.
Master Builders chief executive Ankit Sharma said no one denied that conditions remained difficult, but this was an industry in transition rather than one collapsing. Construction businesses were adapting to market changes, and the industry retained its accumulated experience and resilience.
Why can construction hold steady while the housing market remains cool?
Construction and the market for existing homes do not move entirely in step.
Available stock and asking prices reflect current sales conditions. Building consents and project pipelines are more indicative of construction plans for the coming months or longer. Homes consented today will not immediately enter the market. Some are owner-commissioned builds, some are developments with land and funding already secured, and others still await finance, presales and construction arrangements.
Meanwhile, the existing-home market is still absorbing accumulated stock. New listings fell in August, yet total stock continued rising, indicating that the most pressing issue is slow sales of existing listings rather than sellers entering the market en masse.
In other words, construction is preparing for the future while the property market is still dealing with stock left over from the past. Their temporary divergence is not contradictory.
Clients with a clear need to build and the funds to do so have not entirely withdrawn from the market either.
Master Builders surveyed about 600 homeowners who had recently built a new home or completed a major residential project. Of these, 91% said they would recommend building to others, up from 88% last year. Meanwhile, 75% reported no serious project delays, and 57% of projects were completed within or below budget.
Stable order books do not guarantee projects will proceed
Recovering consents and order books are positive signs, but neither directly equates to construction starting, nor do they mean construction businesses have returned to profitability.
Sharma specifically cautioned that stable project pipelines did not mean those projects were commercially viable. Clients still needed sufficient confidence in finance, costs and timeframes before signing contracts and moving projects into construction.
A project must clear several hurdles between consent and construction: whether the developer can secure bank finance, whether presales meet requirements, whether construction quotes remain stable, and whether the eventual sale price covers land, interest, labour and material costs.
A problem at any stage could delay, reduce or even cancel the project.
This also explains why industry confidence has not recovered alongside builders’ improving pipelines. The survey found that only 46% of builders expected the overall economy to improve over the coming year, down from 59% last year. Meanwhile, 54% expected their own business conditions to improve, also down from 62% last year.
They can see potential workloads increasing, but remain concerned about whether those projects will actually translate into revenue and profit.
Costs and approvals remain two major industry hurdles
The absence of a construction industry collapse does not mean the business environment is now secure.
In the survey, 93% of respondents identified rising costs as the industry’s biggest challenge, one of the highest proportions since 2022.
QV’s latest CostBuilder data shows that average residential construction costs per unit in New Zealand rose 1.1% in the three months to August, taking annual growth to 3.3%. Rebounding diesel prices are also starting to affect earthworks, demolition and transport. For projects with already narrow margins, even a cost movement of a few percentage points can change the final return.
Approval delays bring another hidden bill.
The survey found that 68% of builders said their projects had been affected by approval delays. Of these, 40% bore the associated costs themselves, 24% shared them with clients, and 18% ultimately passed them on to clients.
While waiting, businesses may still need to pay staffing, equipment, insurance and financing costs. If contracts do not clearly specify responsibility for delays and how costs will be adjusted, these expenses can easily become disputes between builders and clients.
The industry’s current challenge therefore goes beyond whether work is available. It is also whether projects can start on time, costs can be locked in, margins protected and payments collected.
This does not prove that all consumers are ready to enter the new-home market, but it at least shows that building remains attractive to those who already have land, funding and clear housing needs.
High housing stock could still affect the construction supply chain
Although construction is showing signs of stabilising, stock pressures in the existing-home market cannot be ignored.
When developers see comparable homes selling slowly and buyers continually pushing prices down, they may reduce land purchases, delay subsequent construction or revise their projects’ layouts, scale and prices.
If sale prices keep falling without corresponding declines in land, interest and construction costs, project margins will be squeezed further. Some developments dependent on presales or short-term finance may also be unable to start because they fail to meet bank requirements.
These pressures could eventually reach main contractors, subcontractors and material suppliers. Project delays, longer payment cycles and repeated budget adjustments all increase cash flow risks for small and medium-sized businesses.
For builders, returning to aggressive expansion simply because consents and order books are recovering would still be overly optimistic. Before accepting a project, they need to look beyond the contract value to its financing, presales, payment milestones and the developer’s payment history. Contracts should also clearly specify quote validity periods, material price adjustment mechanisms, responsibility for approval delays and late-payment terms.
Consents represent potential opportunities. Only projects that actually start and pay on time can become real revenue for construction businesses.
No collapse, but a full recovery remains some way off
Centrix data shows that in the year to July, construction company liquidations stopped rising but remained steady at a high level.
This matches the industry’s current position: the sharpest downward momentum has eased and project pipelines are starting to recover, but cost, financing, approval and sales risks remain.
New Zealand’s construction industry has not collapsed as housing stock has risen, demonstrating its resilience. But that resilience owes more to businesses adjusting their size, changing how they operate and strengthening risk management than to the housing market entering another boom.
The construction market is moving from a survival crisis of “no projects to work on” to the business challenge of “having projects but needing to choose carefully”.
Growth of 21% in new home consents offers the industry more potential work, while 68% of builders having stable or strong pipelines also indicates continuing market support. At the same time, housing stock at its highest seasonal level in 12 years and six consecutive months of falling asking prices remind everyone that end demand still determines whether projects can be realised.
New Zealand’s construction market has not collapsed, but it is still far too early for blind optimism.
What truly determines the industry’s direction next will be more than the number of homes approved: it will be how many can secure finance, begin construction, finish on schedule and find buyers.
Homes are becoming harder to sell, yet construction has steadied for now. Do you think this is the start of another recovery, or a brief buffer before the next wave of pressure?
After the cost surges and supply chain disruption of recent years, clients are paying closer attention to prices, timeframes and builders’ ability to deliver. Construction businesses have also begun reducing their scale, selecting projects more carefully and strengthening cash flow management. The industry is shifting from pursuing expansion to seeking greater project certainty.