
Are you suited to investing? Are you ready? Is now the best time to enter the property market?
COVID-19 is sweeping the world, countries have shut down to varying degrees, and global markets have been hit hard. An economic downturn has become an unstoppable overall trend. Is this a suitable time to invest? Lockdown has given us ample time to calmly review our finances and understand ourselves better. In fact, any time can be a good time to invest, provided you are ready.
Assessing your circumstances: are you suited to investing?
Whether we approach the investment market on foot with caution or drive boldly towards it, we need to ask ourselves before setting off: am I ready?
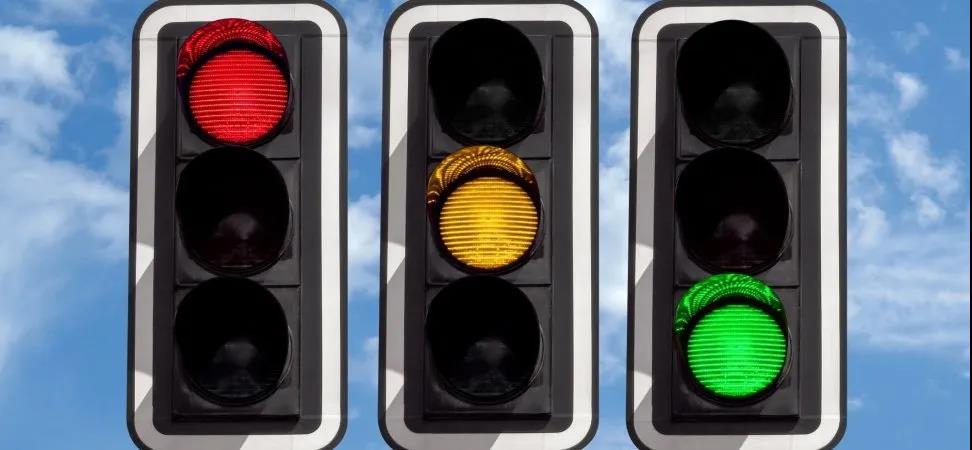
- You have high-interest debt such as credit cards or personal loans, have bought several properties with mortgages, and have virtually no savings to pay bills.
Red light: you will probably have to put on the brakes. Unfortunately, your finances no longer allow further investment. What you may need to do now is sacrifice some existing investments to repay debt.
- You can currently meet your mortgage repayments, have a stable job and some savings, though not much, and can manage your living costs if you avoid major expenses.
Green light: you have some funds, an awareness of risk and a willingness to invest. You have the capacity and circumstances to adjust your direction and move towards your goals at a suitable pace.
- You have had a reasonably well-paid job and have enough savings to meet loan repayments and make some investments, but your employment or income could be significantly affected in the period ahead.
Amber light: assess the future stability of your employment and income, and how long your emergency fund will last. If you intend to invest, strictly limit the proportion you commit.
- You have money in the bank, no major expenses and no credit cards, and could support yourself even with no income for 6 months to a year after entering the investment market.
Amber light: congratulations, you may be among those with the fewest worries at present. Yes, you have ample funds, but this may also suggest that your personality or psychological tolerance is not suited to entering an uncertain market. You therefore face an amber light: whether to stop or go is entirely your decision.
{ad}
Assessing yourself: are you ready to invest?
Given Chinese cultural traditions and financial habits, most of us probably face green or amber lights on the road to investing. But are you ready to decide whether to enter the market, which direction to take and how fast to go? Start by answering a few questions.
Question one: do you have debt?
No: excellent. Skip to question three.
Yes: what kind?
- High-interest debt, such as credit cards or personal loans. Do not invest; consider setting a repayment timetable first.
- Low-interest debt, such as a mortgage. Redirecting some savings from regular debt repayment towards investment may be a good option. But keep three essential principles in mind:
- Always make the minimum required debt repayments;
- Choose investments whose potential returns exceed the interest rate on your current debt;
- Your answer to question two below must be yes.
Question two: do you have an emergency fund?
Yes: good. Move on to question three.
No: start building one promptly.
Tips for building an emergency fund:
An emergency fund is money set aside for unexpected events in life.
- Sources for an emergency fund:
Talking about extra savings now may seem implausible, but it is not as difficult as you might imagine. Social distancing has removed many opportunities to dine out and spend money. Apart from living essentials and necessary debt repayments, your spending has fallen almost to a minimum.
- Consider putting some previously regular expenses into your emergency fund: a weekly restaurant meal, a set of cosmetics, fees for children's suspended sports classes, or seasonal clothing purchases for the family;
- Review all everyday spending and eliminate anything non-essential, even expenses as small as NZ$5 or NZ$10.
- The ideal emergency fund amount varies from person to person, depending on what gives you peace of mind:
- 1-3 months' net income;
- Enough to cover 3–6 months of loan repayments or rent, plus minimum living costs;
- Or, using the corresponding 3–6 months of household spending last year as a reference, 70%–80% of that amount.
- Using an emergency fund:
Draw up a budget listing all essential expenses and when the money will be needed, and follow it strictly.
Question three: how should you choose your investments?
If you have reached question three, you are ready to enter the investment market.
If you are not a risk-loving speculator but want to invest towards future goals such as retirement, the following options depend on when you will need the money:
- You need it in the short term. Consider a portfolio combining high-yield savings accounts and government bonds.
The benefits are low risk, protection against major short-term losses and ready access to your money. The unavoidable drawback is lower investment returns, which may fail to outpace the inflation that will inevitably arrive.
- You need it within 10 years. You could consider taking some risk, for example by investing a portion in low-cost options such as index funds and ETFs, or lower-risk securities such as dividend-paying shares and preference shares.
- You can invest for more than 10 years. This is undoubtedly the best investment scenario. It means you have greater capacity to take risks and, whatever your portfolio, can take your time choosing how to maximise returns from that sector's future market.
Whichever option you choose, investing regularly each week or month in a diversified portfolio is undoubtedly the most successful strategy. Property is a good portfolio option for both the second and third categories above.
Eric Wei Bin, General Manager of Asian Wealth Management at Jarden Securities Limited, said: “Although the Reserve Bank Governor announced today that New Zealand would not introduce negative interest rates over the next 12 months, in the medium to long term, the Reserve Bank's quantitative easing and the Government's fiscal stimulus measures will lead to inflation.”
From an economic perspective, cash savings and fixed-interest debt products cannot protect against inflation. Risk investments such as shares also fail to hedge against inflation if listed companies' earnings cannot keep pace with it. However, fixed assets such as gold and property, particularly scarce resources, are undoubtedly good options for resisting inflation. New Zealand's geography and local government planning policies mean land available for development and construction is very limited. Eric also offered two reminders about property investment:
• Total property investment returns depend on rental returns plus capital gains. Commercial property investors, especially those signing long-term fixed leases, could therefore include provisions for rent increases linked to the Consumer Price Index (CPI).
• Property's disadvantage relative to other investments is its lower liquidity, making it suitable for investors planning to hold it for the long term.
The property market: is now the best time to enter?
Over the past month, property has certainly been one of the most closely watched markets, even if it is not among those hit hardest by the pandemic and economic downturn. Unless you live and work in your own mortgage-free home and own no additional property, you are either a landlord worried about unpaid rent, a homeowner worried about mortgage repayments, a tenant worried about paying rent, or an employee worried about losing your office because your employer cannot pay the rent. At present, the mere mention of property probably strikes fear into most people. But Warren Buffett famously said: “Be fearful when others are greedy and greedy when others are fearful.” Perhaps this is the best time to enter the property investment market.
- Interest rate cuts will make property investment more affordable
Compared with a year ago, banks' mortgage rates have generally fallen by around 1 percentage point. This means a substantial reduction in both total borrowing costs and regular repayments, making it cheaper to become a landlord.
- Record numbers of returning Kiwis create underlying demand
Figures to February this year show an annual net migration gain of 800 New Zealand citizens, the first time returning citizens have outnumbered those leaving. Research by UK think tank DKG ranks New Zealand sixth among the top 10 countries and territories for the most effective pandemic responses. There is reason to believe more New Zealanders will return once the pandemic ends here. A 2008 Department of Labour research report found that returning New Zealanders have a stronger effect on house prices than new migrants: for every 1 increase in population, house prices rise by 6%–9%.
- Limited market supply and an expected fall in prices
Housing demand has consistently exceeded supply across New Zealand, particularly in Auckland. The latest REINZ report shows that in March, before the pandemic broke out, New Zealand's median house price rose by 13.7% to a record high. Unless under financial pressure, some prospective sellers may therefore postpone listing their properties in the hope of securing a satisfactory price once wider social and economic conditions improve.
Any lower-priced homes that appear on the market may come from three groups: construction companies keen to sell completed projects to release cash; homeowners needing to sell their existing homes to fund a necessary upgrade; and small investors forced to sell because they can no longer afford mortgage repayments.
This suggests that after the pandemic, the property market may offer good opportunities to find homes at lower prices despite limited supply. As the market recovers, house prices can be expected to resume a sustained rise.
- Expectations of potentially lower mortgage rates and deposit requirements
In a recent assessment of the property market outlook, independent economist Tony Alexander identified several possible government measures to support the market. These included extending mortgage terms, banks lowering the interest rates used to test borrowers' ability to repay, and reducing deposit requirements, particularly the last of these. If any one of these measures becomes reality, it will push house prices higher.